How to Read an Insurance Declarations Page (Dec Sheet)
Learn how to read an insurance declarations page dec sheet. Understand listed coverage limits, deductibles, endorsements, and what to verify before renewing.
Could your homeowners insurance summary answer some questions while leaving the most important ones open? That’s common: unfamiliar terms, coverage amounts, and deductibles can make a declarations page feel harder to understand than it should. Learning how to read an insurance declarations page dec sheet starts with treating it as a snapshot of your policy, not the full policy itself.
This guide explains how to identify the policy, insured home, and coverage dates, then make sense of the listed limits, premium, deductibles, and endorsements. Those figures tell you what’s recorded, but they don’t guarantee how a future claim will be handled. The policy itself contains the terms, conditions, and exclusions that shape coverage. Before renewal, check whether the home details and listed coverage still reflect your circumstances. With more than 25 years of insurance experience, Chris Lewis helps Central Texas homeowners understand policy language. We’ll walk through what the dec sheet can tell you, what it can’t, and how to prepare useful questions for a review.
Key Takeaways
- Follow a clear sequence to learn how to read an insurance declarations page dec sheet, starting with the policy details and moving through the property and listed coverages.
- Compare limits, deductibles, and premiums by what each figure represents, without treating them as a promise about how a claim will be handled.
- Review the address, named insureds, mortgage information, and home characteristics for changes before renewal.
- Mark unclear entries, look for related wording in the policy, and prepare focused questions for a policy review.
What an Insurance Declarations Page Shows, and What It Leaves Out
A homeowners insurance declarations page, often called a dec sheet, is a short summary of selected details about your policy. It can help you identify the insured home, policy period, and listed coverages, but it isn’t the full contract. A useful way to think about it is this: A dec sheet is a snapshot of selected policy details, not a promise that a particular claim will be paid.
If you’re learning how to read an insurance declarations page dec sheet, keep that distinction in mind. The summary points you toward key information; the full policy and any endorsements explain the terms that apply. Endorsements are documents that may change, add to, or clarify policy terms. Their effect depends on the wording in your documents.
Why homeowners receive a dec sheet
The summary gives you a practical way to identify your homeowners policy and review details without searching through every page first. You might consult it when policy documents arrive, when you’re preparing for renewal, or when you want to check the information associated with your home. It’s a starting point for review, not a substitute for reading the policy.
For example, a homeowner in Central Texas might use the page to locate the listed dwelling coverage and deductible before reviewing the related policy wording. That helps focus questions, especially before renewal, when home details or household circumstances may have changed.
What the dec sheet cannot tell you on its own
A summary has limits. Exclusions, conditions, and definitions that affect coverage may appear in the policy or an endorsement rather than on the dec sheet. Those sections explain how the policy applies, including requirements or restrictions that may matter in a particular situation. Coverage depends on the actual policy, its endorsements, and the circumstances of a loss.
A listed coverage limit tells you the amount shown for that part of the policy. By itself, it doesn’t establish whether a specific loss is covered, how damage will be evaluated, or what a claim payment might be. For instance, a listed dwelling limit alone can’t answer whether a particular roof loss is covered or how the policy would apply. Those questions depend on the policy language and the facts of the claim, and the insurer makes the claim determination.
- The dec sheet: A quick reference for selected policy details.
- The policy: The terms, conditions, exclusions, and definitions that provide context.
- Endorsements: Additional documents that may alter or clarify terms, depending on their wording.
Read the summary as a guide to where to look next. If an entry raises a question, find the related wording in the policy and review both documents together. This keeps a listed figure in perspective and gives you a clearer basis for asking informed questions.
How to Read the Policy, Property, and Coverage Details on a Dec Sheet
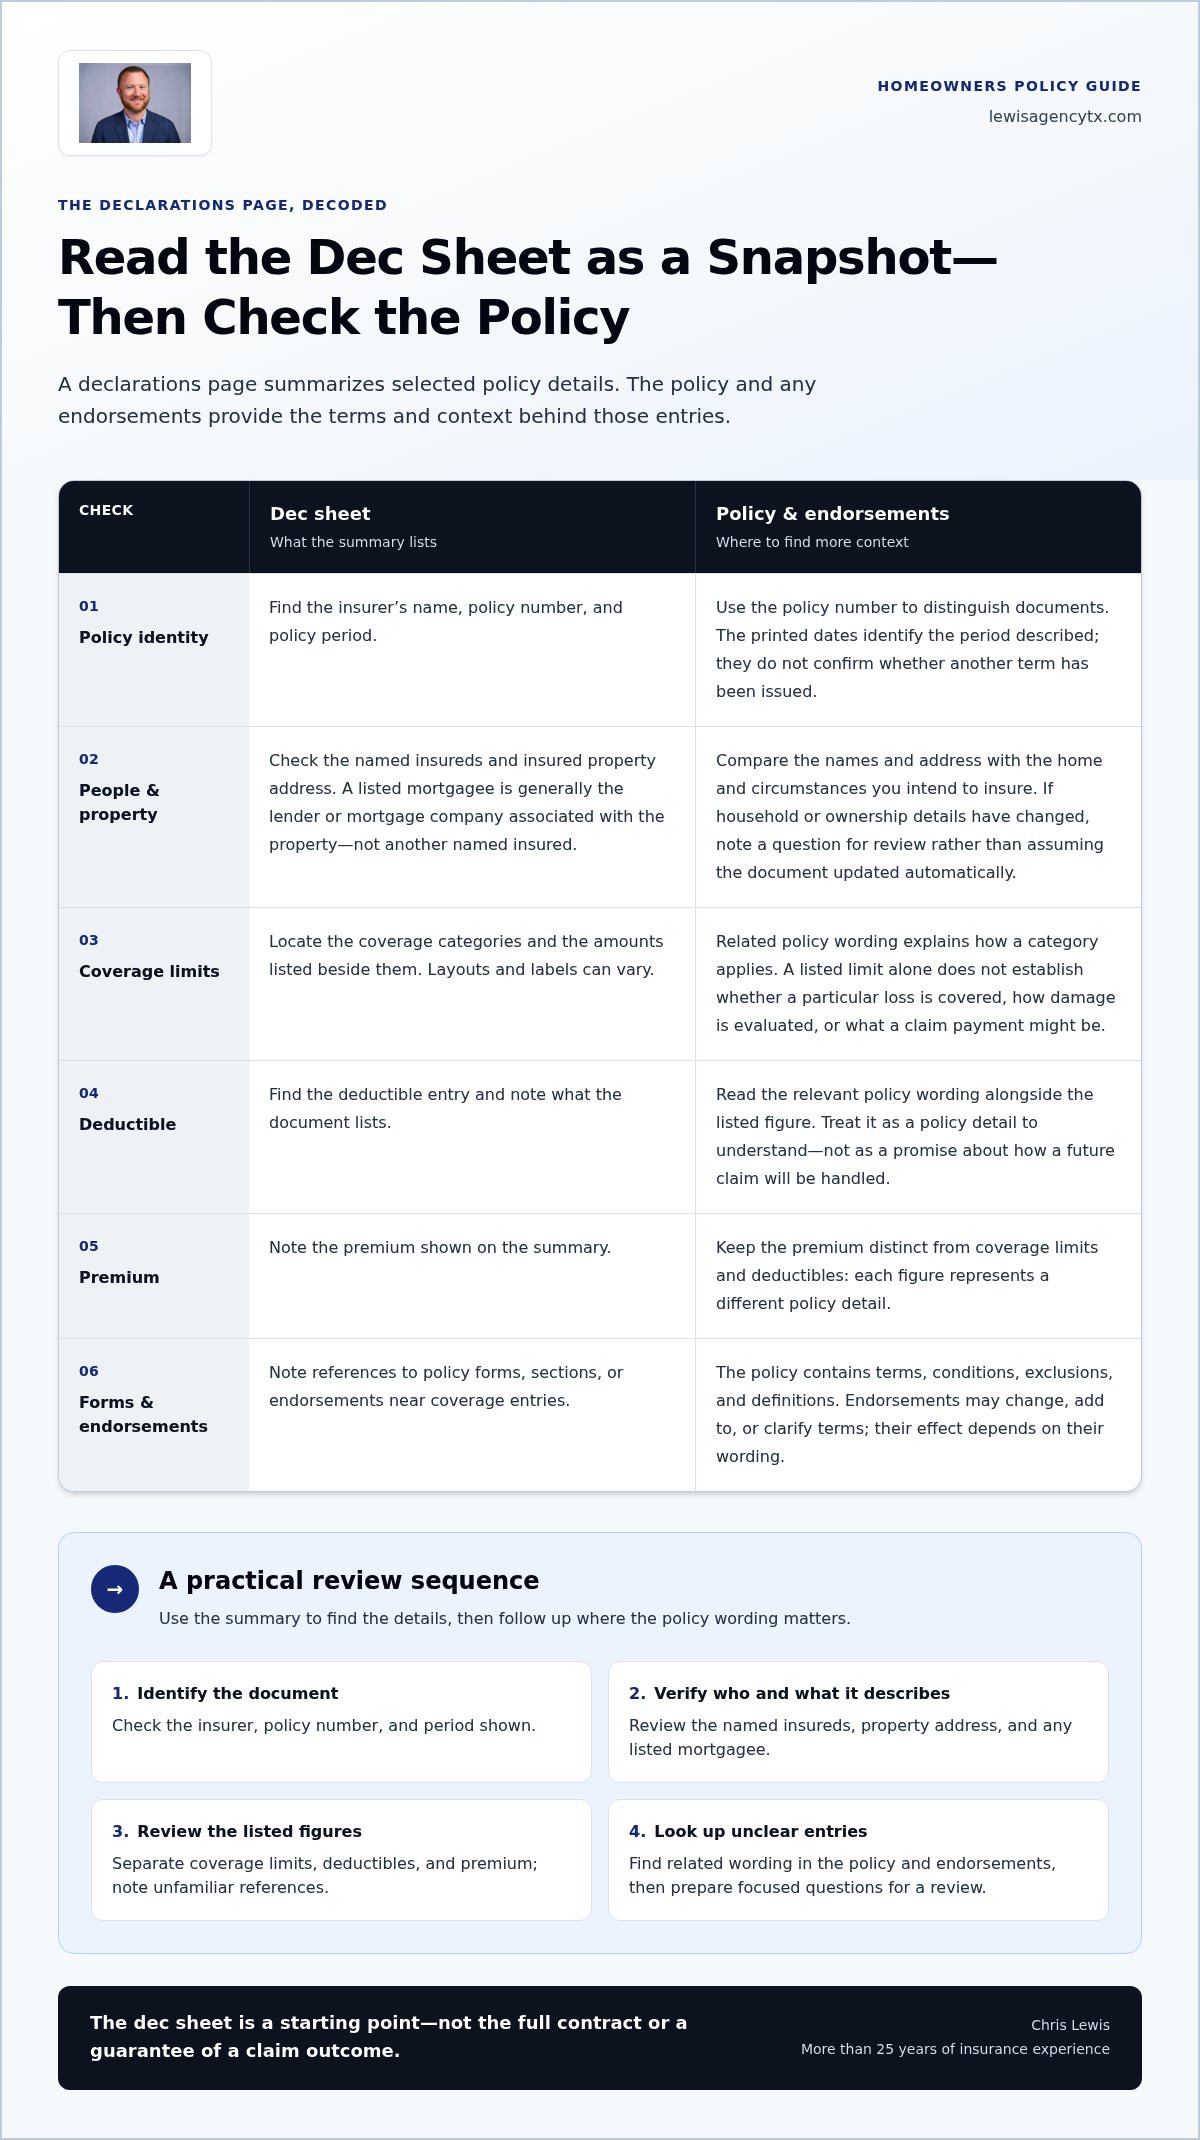
Start with the identifying details before looking at coverage amounts. This helps confirm which policy document you’re reading and which home it refers to. When learning how to read an insurance declarations page dec sheet, connect each listed detail to the right property and policy period, then note anything that needs a closer look.
Start with the people, property, and policy dates
Find the policy number, named insureds, insured location, and policy period. These details help distinguish one document from another, especially if you have copies from different dates. The policy number is the insurer’s reference for the policy. Named insureds are the people identified on it. The insured location is the home the document describes. Check the dates printed for the policy period rather than assuming a document is current because you recently received it.
- Identify the policy. Locate the policy number and the insurer’s name. Use the number to distinguish this document from other policy paperwork.
- Check the named insureds. Review the names as printed. If a household or ownership change has occurred, note it as a question for your policy review rather than assuming the document updated automatically.
- Verify the insured property address. Compare the listed location with the home you intend to insure. The property address identifies which home the policy details refer to. For example, a homeowner in Round Rock should check that the page names the intended Round Rock property, not a previous residence.
- Read the policy period. Note the start and end dates shown. These dates help you compare documents and identify the period each one describes; they don’t, by themselves, confirm whether another term has been issued.
Locate the listed coverages and policy references
After checking the identifying details, look for the coverage section. It may appear as a table or schedule, with coverage categories alongside listed amounts. Labels and categories can vary, so read your own document rather than expecting every Texas policy to use the same layout. The mortgagee, if listed, is generally the lender or mortgage company associated with the property, not another named insured.
Note any references to policy forms, sections, or endorsements near the coverage entries. These references point to wording that explains how a category applies or whether an endorsement changes the terms. Don’t assume a coverage label alone answers questions about a specific loss. Keep a short list of unfamiliar references so you can find them in the accompanying policy documents.
For instance, a hypothetical homeowner in Cedar Park might find the correct address and policy dates, then see a coverage label followed by a form reference. The useful next step is to record that reference and locate its wording, not to draw a conclusion from the label alone. If you’d like help understanding your policy documents, you can discuss your homeowners policy with The Lewis Agency.
How to Understand Home Insurance Limits, Deductibles, and Premiums
Coverage amounts, deductibles, and premium may sit close together on a declarations page, but they describe different parts of the policy. To understand how to read an insurance declarations page dec sheet, consider each figure separately, then check how the policy wording connects it to a particular coverage or loss.
Read coverage limits as listed amounts, not claim promises
A limit is the amount shown for a particular coverage category. Your dec sheet may display several categories and their amounts in a table or schedule. Labels and layout vary by policy, so don’t assume every homeowners policy uses the same categories or structure. A listed limit helps you understand what the document states, but it doesn’t independently determine whether a specific loss is covered or how a claim will be settled.
Policy wording, exclusions, endorsements, and the facts of a loss all matter. A listed dwelling limit, for example, doesn’t by itself explain how the policy would respond to damage from a particular event. For roof questions, check how the policy describes settlement and which roof coverage applies. The distinctions in actual cash value versus replacement cost for a Texas roof can help you identify what wording to look for.
Check deductibles and premium without assuming why they changed
A deductible is the amount or share you’re responsible for under the policy when a covered loss applies. The premium is the amount charged for the policy period shown in the documents. Neither figure has one universally suitable value. Review what your own documents say, and don’t infer the reason for a premium change from the declarations page alone.
Pay attention to the deductible’s label and which coverage it applies to. A policy may list more than one deductible, with different terms or applications. If a deductible is shown as a percentage, check the policy wording to understand what it is calculated against rather than assuming the percentage applies to the cost of repairs. Don’t assume one listed amount applies to every kind of loss. If the wording or calculation is unclear, note the question and locate the relevant policy language.
| Figure | What it represents | What it doesn’t establish by itself |
|---|---|---|
| Coverage limit | The amount shown for a coverage category | Whether a particular loss is covered or what a claim will pay |
| Deductible | Your stated share or amount under applicable policy terms | Which deductible applies without checking its label and wording |
| Premium | The policy charge for the stated period | Why the price is at that level or how it may change later |
If the premium differs from an earlier document, compare the policy periods and listed details before drawing conclusions. A rate change can have several possible explanations, and the dec sheet alone may not explain them. For broader renewal context, see Texas home insurance rate increases in 2026. Use the figures as prompts for review, then consult the policy wording for the terms that govern your coverage.
How to Review a Dec Sheet for Home Details, Changes, and Questions
A policy review is a chance to check whether the information on your declarations page still reflects your home and household. Keep the current page beside an earlier one, if you have it, and list anything that looks different or unclear. Learning how to read an insurance declarations page dec sheet also means knowing when a detail deserves a follow-up question instead of guessing what it means.
Check whether the listed information still matches your home
Compare the page with your current circumstances. Pay attention to the insured address, named insureds, mortgage information, and property characteristics shown on the document. Details such as construction or roof information may appear, depending on the policy documents. If something seems outdated or inaccurate, write it down for a policy discussion. Don’t assume that changing a detail will necessarily change coverage or premium.
- Address: Does the insured location match the home you’re reviewing?
- Named insureds: Are the listed names consistent with the current household and policy documents?
- Mortgage information: Is the mortgage company information shown, if applicable, consistent with your records?
- Property details: Do listed characteristics appear to match the home as you understand it?
Use the checklist to identify questions, not to decide whether a claim would be covered. For example, imagine a homeowner in Georgetown notices hail damage to a roof and sees a roof-related entry on the dec sheet. The summary may help identify a coverage label or endorsement to look up, but it can’t answer on its own how the policy applies to that damage. The policy wording and circumstances of the loss matter. Broader policy topics are covered in this Austin homeowners insurance coverage guide.
Compare the current page with prior policy documents
Look for changes in the policy dates, listed amounts, deductibles, or endorsements. Mark each difference and note what you want clarified. A changed entry is a reason to investigate, not proof of why it changed or what effect it has. If the premium is different, keep that question separate from the other entries; the declarations page may not explain the reason.
Before a review, gather relevant records, such as an updated mortgage statement or information about changes to the home. Keep your questions specific: “What does this listed property detail refer to?” or “Where can I find the wording for this endorsement?” Focused questions make it easier to connect a summary entry with the policy language that explains it.
If several entries have changed, review them one at a time rather than trying to infer a single cause. The Lewis Agency can help explain homeowners policy documents and clarify questions about listed information. Reviewing the details calmly before renewal gives you time to understand what the documents say and identify anything that needs attention. This review approach applies whether your home is in Austin, Leander, Cedar Park, Georgetown, Round Rock, or Liberty Hill.
What to Do After Reading Your Home Insurance Dec Sheet
Once you’ve reviewed the summary, turn anything unclear into a specific question. Mark the entry, find the related wording in your policy documents, and ask for help understanding how the documents fit together. Knowing how to read an insurance declarations page dec sheet means knowing when to look beyond the summary, too.
Prepare focused questions about unclear entries
Keep your questions neutral and tied to the wording you see. Instead of asking whether a loss is covered based only on a label, ask what that term or figure refers to in your specific policy and where its full explanation appears. That keeps the discussion grounded in your documents, rather than assumptions about what the policy might say.
- Mark the entry. Note the label, amount, date, or reference that prompted your question.
- Find related wording. Check the policy sections or endorsements connected to the entry. Look for relevant definitions, exclusions, and conditions.
- Ask a focused question. For example: “Where does the policy explain this term?” or “What wording applies to this listed coverage?”
If two documents seem to use different terms, bring both into the review and ask how they relate. If a deductible or coverage entry is unclear, ask what the specific wording says about when it applies. These questions don’t assume a particular answer or claim outcome. They help you understand which policy language is relevant.
Use a policy review to clarify next steps
A policy review can help you make sense of the documents, identify details you may want to discuss, and understand what to read next. An insurance agent can explain policy language and help you follow the claims process, but doesn’t decide whether a claim is covered or control coverage terms. Coverage interpretations and claim decisions depend on the policy and the circumstances involved.
Chris Lewis has more than 25 years of insurance experience and helps Central Texas homeowners better understand coverage and policy language. A conversation can clarify what a listed entry means and where to find its context, without treating the summary as a decision about a future claim.
Bring the declarations page and related policy documents, along with the questions you marked. You don’t need to resolve every detail at once. Start with the entries that matter most to your understanding of the home’s policy, then work through the related wording one question at a time. That steady approach can make a policy review more useful and help you know what follow-up, if any, makes sense.
If you’d like to talk through questions about your homeowners policy, you can ask The Lewis Agency about your homeowners policy.
Make Your Next Policy Review More Useful
Set aside time before renewal to make policy review a regular part of caring for your home. A brief note of questions as they arise can help you approach that review with a clearer sense of what you want to understand. Knowing how to read an insurance declarations page dec sheet isn’t about finding every answer on one page. It’s about being ready to follow up thoughtfully.
Keep your policy documents together in a place you can find them, and note when you last reviewed them. If your circumstances change, add that to your list for the next review. Small habits like these can make it easier to stay engaged with your coverage over time.
Take the process one question at a time. Understanding your policy is ongoing, and steady attention can help you feel more prepared for future decisions.
Frequently Asked Questions
What is an insurance declarations page, or dec sheet?
It’s the declarations page, a document homeowners can use to identify which contract and policy period they’re looking at. A practical way to learn how to read an insurance declarations page dec sheet is to compare its dates and policy number with the paperwork you’re reviewing. That check can help prevent mixing up current documents with older copies when you organize records or prepare questions.
Is a declarations page the same as an insurance policy?
No. Think of the declarations page as one document within the broader set of policy materials, not a replacement for them. If you’re trying to understand a particular term, note any section or form references near it and use those as clues for where to look next. Keeping the related pages together can make it easier to follow how the documents connect.
Can a declarations page prove that my home is insured?
It can provide policy information, but the organization requesting proof decides what documentation it will accept. If a mortgage lender asks for evidence, clarify whether it needs a declarations page or another document, and whether it requires a specific policy period or delivery method. Then provide the current paperwork that matches the request. This avoids assuming that one document will meet every organization’s requirements.
What should I do if my homeowners declarations page has incorrect information?
Describe the issue clearly when you contact your insurance agency or insurer. For example, identify the exact field and explain what you believe it should say, using relevant records if helpful. Ask how the discrepancy should be handled and whether updated documentation will be provided if a change is made. Keep any response with your policy records so you can refer to it during a later review.
How often should I review my insurance declarations page?
Review it when you receive new policy documents and when a change in your household or home prompts a question. Keep dated copies together and make a brief note of changes you want to discuss. That record can help you track what you noticed and when, without relying on memory at renewal. The right review timing depends on your circumstances and policy documents.
Where can I get a copy of my homeowners dec sheet?
Look through the documents provided by your insurer or its customer account tools, if available. If you can’t find the page, contact your insurance agency or insurer and specify the policy period you need. Save the copy with your other homeowners records and label it by date. That makes it easier to distinguish the current document from earlier versions when you’re discussing your policy.
Does a dec sheet show whether hail damage to my roof is covered?
It can help you identify which roof-related terms to ask about, but don’t use it alone to predict a claim result. For a Central Texas hail concern, note the deductible label and look for any roof settlement wording or related endorsement in the policy documents. An insurance professional can explain where those terms appear and how to read them; claim decisions depend on the policy and loss circumstances.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.
Texas Home Insurance Rate Increases in 2026: What Homeowners Should Know
Understand Texas home insurance rate increases 2026 beyond headlines. Learn how to review your renewal declarations page, deductibles, and coverage limits.
Did your renewal arrive with a higher premium, but little explanation of what changed? Headlines about texas home insurance rate increases 2026 can offer context, but they can’t tell you why your own policy changed or whether its coverage changed along with the price.
It’s reasonable to want clear answers before adjusting your household budget or deciding what to do next. A premium change may reflect factors tied to your home, location, policy, or insurer. Rate trends alone don’t explain how those details apply to you, and coverage and rates vary by insurer, policy form, endorsements, and individual circumstances.
This article explains what rate information can and can’t tell you, which renewal details deserve a careful review, and where to find reliable guidance, including resources from the Texas Department of Insurance. You’ll learn how to compare dwelling coverage, deductibles, endorsements, and property details rather than premium amounts alone. For homeowners in Austin and Central Texas, a document-by-document review can put a surprising renewal into perspective and help you ask informed questions.
Key Takeaways
- Learn what reports on Texas home insurance rate increases in 2026 can tell you, and why statewide averages don’t predict your individual renewal.
- Understand why storm losses and rebuilding costs may be relevant market pressures without assuming they explain a specific premium change.
- Compare your current and prior declarations pages to spot changes in premium, coverage limits, deductibles, endorsements, and property details.
- Use a straightforward renewal review process to gather documents, verify home details, and prepare focused questions before renewing.
- Find reliable general guidance from the Texas Department of Insurance and learn how a local agent can explain policy language.
What 2026 Texas Home Insurance Rate Hikes Really Mean
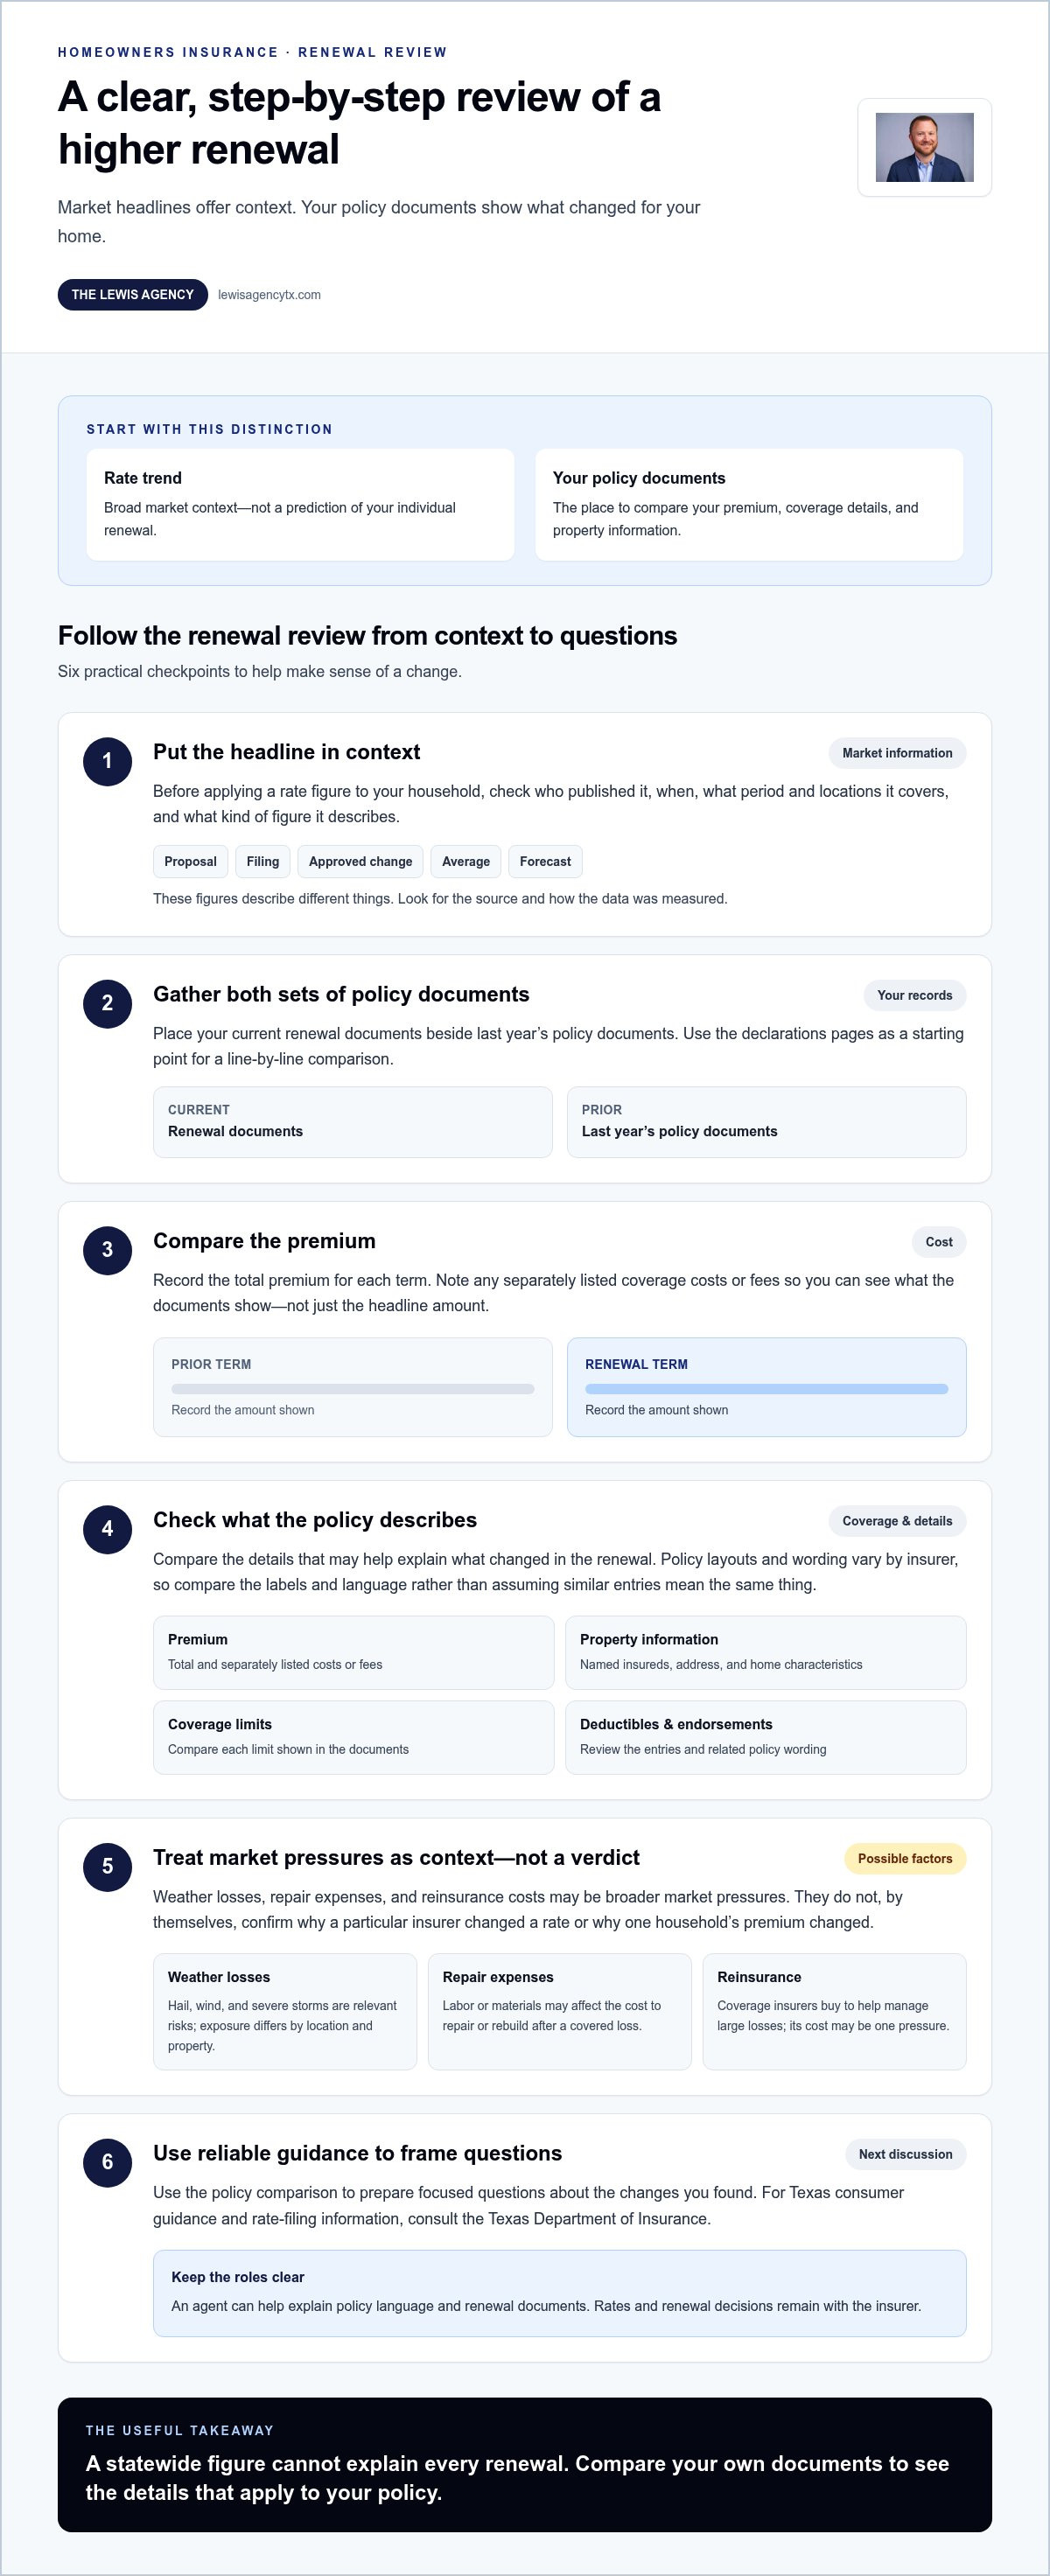
A “rate increase” describes a change an insurer makes to its rates, whether reflected in a filed rate or an offered price. It doesn’t mean every homeowner’s renewal premium rises by the same amount. Your renewal reflects the terms and details of your own policy, so reports on texas home insurance rate increases 2026 provide context, not a prediction of your next bill.
A useful rate figure needs more than a percentage. Check who published it, when it was published, what period it covers, and whether it describes a proposal, a filing, an approved change, an average, or a forecast. Also look for an explanation of the data being measured, including the locations and types of policies represented.
How to read 2026 Texas rate figures
Those distinctions matter. An insurer’s filing is not automatically the same thing as the change applied to every policy, and an industry estimate is not an official statewide average. For Texas-specific information, use the Texas Department of Insurance for consumer guidance and rate-filing information. If a report doesn’t name its source or explain its method, treat the number cautiously rather than applying it to your household.
When you see a rate headline, check the source, date, geographic scope, and type of figure before drawing conclusions. A filing, a forecast, and an average describe different things. For a general introduction to home insurance, see What is home insurance?
Why a statewide trend is not your renewal quote
A statewide average combines many policies and circumstances. Your premium may depend on details such as the home’s location and characteristics, the coverage selected, and the insurer’s rating approach. Policy forms and endorsements also vary. A statewide percentage can’t account for all those differences, so applying it directly to one renewal may give a misleading impression.
For example, a report might describe an average change across a defined group of policies. That figure wouldn’t tell you whether your own renewal changed by the same amount, or whether changes to limits, deductibles, or endorsements affected the total. The declarations page and renewal documents show the details that apply to your policy. Compare those documents instead of predicting your premium from a broad market estimate.
Why might Texas homeowners insurance rates rise in 2026?
A higher renewal can prompt a fair question: what is behind the change? Weather losses, repair expenses, and the cost of reinsurance are possible pressures on the wider insurance market. Treat them as factors to investigate, not confirmed explanations for every Texas rate change in 2026.
A market-wide pressure may affect insurers’ costs, while an individual renewal also reflects the property, selected coverage, and the insurer’s rating and underwriting approach. The phrase texas home insurance rate increases 2026 describes a broad topic, not one explanation that fits every household. The Texas Department of Insurance offers consumer guidance on understanding Texas home insurance and rates.
How severe weather may factor into insurance costs
Hail, wind, and severe storms are relevant risks to consider in Central Texas, but exposure differs by location and property. A home’s condition and characteristics may also matter. Without reliable evidence connecting a particular event or loss trend to a specific rate change, it would be misleading to say that a storm caused an individual homeowner’s increase. A regional risk is context, not a verdict on a particular renewal.
Repair costs, reinsurance, and other market pressures
When labor or materials become more expensive, repairing or rebuilding after a covered loss may cost more. Reinsurance is coverage that insurers buy to help manage large losses. Changes in its cost may be one pressure insurers consider. These concepts help explain why the broader market can shift, but they don’t establish what caused a particular insurer’s rate action or a household’s premium change.
To assess a claim about market pressures, look for a named source, publication date, defined time period, and clear explanation of the data. A reported statewide trend may not describe Austin or another Central Texas community equally, and it cannot substitute for the details of a specific renewal. Use state guidance for general context, then focus on the insurer’s explanation and the policy documents for your own home.
The Lewis Agency can help homeowners understand policy language and renewal documents. An explanation can clarify what the documents say, while rates and renewal decisions remain with the insurer.
How can you tell what changed on your 2026 renewal?
Put your current renewal documents beside last year’s policy documents and compare the declarations pages line by line. This helps separate a higher premium from changes to what the policy describes or how a loss may be handled. Rate headlines can’t show those individual details; your own documents can.
Start with the total premium, then note any separately listed coverage costs or fees. Compare the named insureds and property information, including the home’s address and characteristics. Check each coverage limit, endorsement, and deductible. Document layouts and terms vary by insurer, so compare labels and policy wording rather than assuming two similar-looking entries mean the same thing.
Which renewal details deserve a side-by-side review?
- Premium: Record the total for each term and any separately listed components or fees.
- Property and policy details: Check the address, named insureds, and other listed home information for accuracy.
- Coverage and endorsements: Compare limits and note endorsements that were added, changed, or removed.
- Deductibles: Read the wording carefully, including whether different loss types have separate deductibles.
If a line is unclear, mark it and ask for an explanation before deciding what the change means. For broader policy context, review this Austin homeowners insurance coverage guide.
Could a roof or deductible change affect the picture?
It may. Depending on the policy, roof coverage terms can affect how a covered loss is evaluated, while the deductible affects the amount the homeowner may pay toward a covered claim. Don’t assume that a particular roof valuation method or deductible applies to every Texas policy. Compare the actual wording in both terms, and ask what a change means for your circumstances. This Texas roof coverage comparison explains two terms you may encounter.
For example, imagine a Central Texas homeowner whose renewal premium rises and whose documents also show a change in roof-related wording. The premium difference alone wouldn’t reveal whether the roof term changed, whether the deductible changed, or whether both are unchanged. A side-by-side comparison helps identify the questions to ask, but it doesn’t determine how a future claim would be handled.
If you still need help interpreting a document, the Texas Office of Public Insurance Counsel provides resources to get help understanding a renewal. An experienced agent can also explain policy language and renewal documents, while the insurer makes its own rate and coverage decisions.
What should Central Texas homeowners do before renewing?
A renewal review is easier when you take it in order. Rather than making a quick change based on rate headlines, understand what your own renewal says, check that the home details are current, and ask about anything that could affect your coverage or out-of-pocket costs.
A simple renewal review sequence
- Gather the documents. Set out your current policy, renewal offer, declarations page, and endorsements. If available, keep the prior term’s documents nearby for comparison.
- Check the property information. Confirm the address and listed home details. Note meaningful renovations, such as a roof replacement or other work that may affect the home, and tell your insurer about relevant changes.
- Mark what changed. Flag differences in premium, coverage limits, deductibles, endorsements, and property details. Keep questions beside the specific line or wording that prompted them.
- Ask for a plain-language explanation. Before making a decision, clarify unfamiliar terms and how a proposed change could affect the policy. The Texas Department of Insurance consumer guide is a resource for general questions about homeowners coverage and rates.
Also consider whether household needs have changed. A renovation, new belongings, or a change in who lives in the home may be worth discussing as part of the review. The details that matter depend on the policy and circumstances, so don’t assume a change automatically alters coverage.
How to weigh premium against protection
A lower premium may come with a tradeoff, depending on the policy. Changing a deductible can affect what you pay out of pocket for a covered loss. Reducing a coverage limit may leave less available for a covered need. Before choosing a change, consider the home’s rebuilding needs, the household’s finances, and the amount you could manage yourself after a loss.
There isn’t one deductible or coverage limit that suits every homeowner. Ask what each proposed adjustment changes, and review the actual policy wording rather than deciding on price alone. The insurer determines its rates, renewal terms, and coverage decisions. An agent can help explain documents and policy language.
The Lewis Agency helps homeowners understand their homeowners policy and renewal documents.
Where can Austin and Central Texas homeowners get help understanding a renewal?
A renewal document can raise questions that aren’t answered by the premium figure alone. An experienced agent can help explain policy wording, identify what the documents say about listed coverage, and clarify which changes deserve follow-up. For homeowners reading about texas home insurance rate increases 2026, a policy-specific explanation is more useful than assuming a statewide trend predicts an individual renewal.
What an insurance agency can help clarify
The Lewis Agency is an Allstate agency serving Austin and Central Texas. Chris Lewis has more than 25 years of insurance experience and helps homeowners understand policy language, renewal documents, and the claims process. Questions might include what a term means, where a coverage detail appears, or what changed between policy periods.
That guidance has clear limits. The agency doesn’t control rates, underwriting, renewal decisions, coverage determinations, or claim outcomes. Those decisions are made by the insurer and depend on the policy and individual circumstances. An agent can help you understand the documents and process, but can’t promise a particular rate or claim result.
A practical next step for your renewal
Bring specific questions to the conversation. For example, point to a changed premium, deductible, limit, endorsement, or home detail and ask what the wording means. Having the current and prior renewal documents nearby can make it easier to focus on the exact change rather than trying to interpret the whole policy at once.
Homeowners in Austin and nearby Central Texas communities, including Round Rock, Cedar Park, Georgetown, Leander, and Liberty Hill, can review their questions before renewal. You don’t need to resolve every detail from a headline. Start with what your documents say, ask for an explanation where the wording is unclear, and consider how the policy fits your home and circumstances. Chris Lewis and The Lewis Agency can help Allstate homeowners understand policy language and renewal paperwork, without promises about the insurer’s decisions.
Make your next renewal easier to understand
Statewide reports can provide useful context, but they can’t explain every household’s renewal. That’s the key point behind texas home insurance rate increases 2026: your own documents show whether the premium, coverage limits, deductibles, endorsements, or property details changed.
Before renewing, compare the current and prior documents, check that the home information is accurate, and write down questions about unfamiliar wording. Consider both the premium and what the policy says about coverage and potential out-of-pocket costs. Changes that make sense for one household may not fit another, so understand the tradeoffs before making a decision.
Chris Lewis has more than 25 years of insurance experience, and The Lewis Agency is an Allstate agency serving Austin and Central Texas. The agency can help explain policy language and renewal documents, though the insurer makes rate, renewal, coverage, and claim decisions. If you have questions about your Allstate homeowners policy, contact The Lewis Agency to discuss your policy.
Frequently Asked Questions
Are Texas home insurance rates increasing in 2026?
There isn’t one increase that applies to every Texas homeowners policy. Insurers may change rates, but filings, estimates, and statewide averages describe different things and don’t establish what any one household will pay. To understand texas home insurance rate increases 2026, check the source, publication date, time period, and measurement behind a reported figure. The Texas Department of Insurance provides state-specific consumer information and rate-filing resources.
Why did my Texas homeowners insurance premium go up at renewal?
Your premium may have changed for reasons tied to the home, selected coverage, policy endorsements, or the insurer’s rating approach. A statewide trend alone can’t explain your individual renewal. Compare this term’s documents with the prior policy and look for changes to the premium, limits, deductibles, endorsements, and listed property details. If the documents don’t explain the difference clearly, ask the insurer or your agent to clarify the change.
Will my Austin or Central Texas home insurance rate increase in 2026?
No statewide trend can predict your individual renewal. Rates and renewal terms depend on the insurer, policy, property, and individual circumstances. Homeowners in Austin, Leander, Cedar Park, Georgetown, Round Rock, and Liberty Hill should review their own renewal documents rather than assume a regional headline applies directly. Compare the current and prior terms, and ask about specific changes. An agent can explain policy language, but the insurer makes rate and renewal decisions.
Can a hailstorm or older roof affect my homeowners insurance renewal?
They may be relevant, depending on the insurer, policy, home, and circumstances. A storm risk or an older roof doesn’t by itself tell you whether your premium or coverage will change. Read the renewal documents for roof-related wording, endorsements, deductibles, and any listed property details. If something is unclear, ask what the specific language means for your policy. Don’t assume one roof valuation method or deductible applies to every Texas homeowner.
What should I compare on my homeowners insurance renewal?
Compare the total premium, listed coverage limits, deductibles, endorsements, named insureds, and property details with the prior term. Pay attention to changes in wording, not just changes in dollar amounts. Policy documents may look different across insurers, so review each term’s definitions and explanations. Mark unclear items and ask focused questions before making a decision. This helps distinguish a premium change from a change in what the policy says.
Should I reduce my coverage to lower my Texas home insurance premium?
Don’t reduce coverage based on premium alone. A lower limit or changed deductible may affect what you would need to manage after a covered loss, depending on the policy. Consider your home’s rebuilding needs, finances, and potential out-of-pocket costs together. Ask what a proposed change means before deciding, and review the policy wording. No single limit or deductible is right for every household, and coverage terms vary by insurer and policy.
Where can I check reliable information about Texas homeowners insurance rates?
Start with the Texas Department of Insurance consumer guide for Texas-specific information about homeowners coverage and rates. For a reported rate figure, check its source, date, time period, and whether it describes a filing, estimate, or average. The Office of Public Insurance Counsel also provides consumer resources. Use official guidance for general context, then review your own policy documents for renewal details.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.