Home Insurance in Leander, TX: How Much Coverage Costs
Find new home insurance information for Leander, TX: learn what shapes premiums and compare policy details for roof, wind, hail, and flood coverage options.
A Leander homeowners policy has no single set price. The premium depends on the home and the coverage selected, so new home insurance information for Leander, TX, is most useful when it explains what shapes a quote rather than promising one rate for every homeowner.
It’s reasonable to want to understand what affects the cost before choosing coverage. This article explains how dwelling coverage, roof condition, home construction, claims history, and policy details can affect the price, and what to consider when reviewing coverage. You’ll also learn how Texas insurance options differ and where to find local agency contact information.
Key Takeaways
- Estimate costs in context: dwelling coverage and details about the home affect the premium, while personal property coverage helps protect belongings.
- When reviewing Texas insurers, look beyond the quoted price and consider how the policy’s coverage and terms fit your needs.
- Understand how your policy treats wind, hail, and flooding; these protections can differ, so review the specific policy terms.
- Use local agency guidance to clarify coverage options and make an informed decision about your home insurance.
How Much is Home Insurance in Leander, TX?
Leander premiums vary with the dwelling coverage selected and the home’s details.
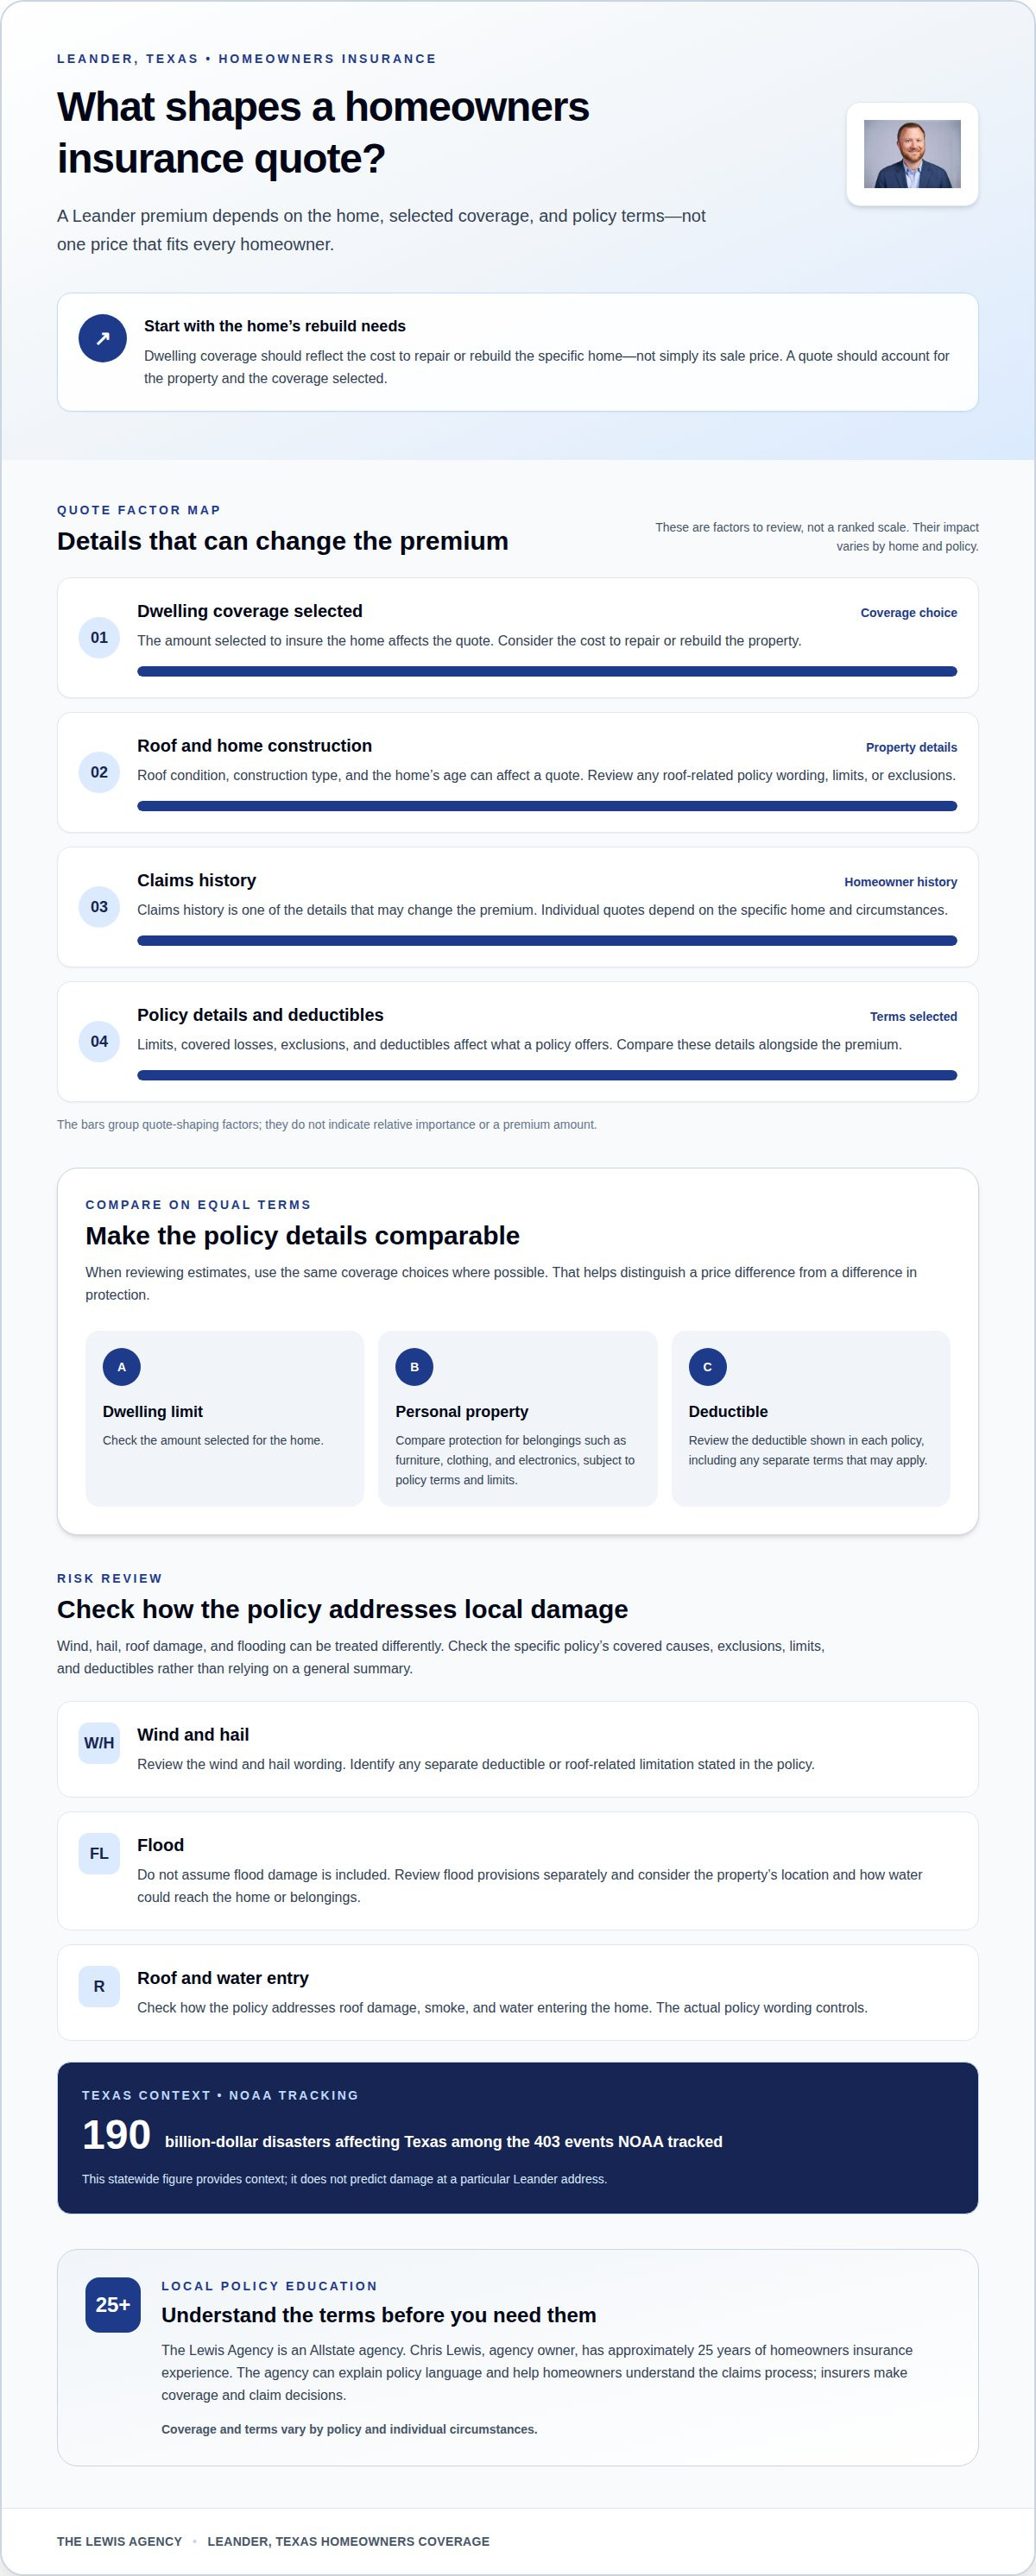
These figures are market averages, not insurer-by-insurer quotes. The estimates use a Leander homeowner with average credit, no claims in the past five years, and a brick home aged 10-34 years. A different roof, construction type, claims history, or coverage selection can change a home’s premium. A quote should reflect the cost to repair or rebuild the specific home, not simply its sale price.
For a new home, review the lender’s loan documents for its insurance conditions, including any required proof and timing. The premium averages above describe costs, not Texas legal requirements or lender-set coverage amounts.
Personal property coverage applies to belongings such as furniture, clothing, and electronics, subject to policy terms and limits. Other structures, such as a detached shed, are usually limited to 10% of dwelling coverage. Actual limits vary by policy.
Also review loss-of-use, liability, and medical payments coverage. Loss-of-use coverage typically equals 20% of dwelling coverage and is usually limited to 12 to 18 months after a covered event. Confirm how each part of the insurance policy applies to your property and expenses.
Comparing Texas Homeowners Insurance Policies
These figures provide context, not a quote for a particular home.
Leander Insurance Costs
The Leander average can help with initial budgeting, but it doesn’t show what an insurer will charge for a specific home. Quotes depend on the property, selected coverage, and policy terms. Compare estimates using the same dwelling limit, personal property protection, and deductible. That makes it easier to see whether differences reflect price or coverage.
Comparing and Shopping for Policies
Review each policy’s covered loss provisions, exclusions, deductibles, and limits before comparing premiums. Check how the insurer values the home and belongings, and whether the terms address features such as your roof. Ratings can offer another point of comparison, but they don’t explain what a policy covers. Ask how combining homeowners and auto insurance would affect your quote; don’t assume it guarantees savings. A homeowners coverage resource can help you understand policy details.
Coverage for Local Damage Risks
Does homeowners insurance cover hail, tornado, wildfire, or flood damage in Leander? Hail, tornado, and wildfire losses depend on the policy’s covered causes, exclusions, and applicable deductibles. Don’t assume flood damage is included; review flood provisions separately. Before choosing coverage, check how the policy addresses roof damage, smoke, and water entering the home. Those details can affect whether repairs are covered after a specific event.
What optional home insurance coverage is recommended in Leander, such as flood or wind and hail coverage?
Start with the events that could damage your Leander home, then check how the policy handles each one. Wind and hail protection, flood coverage, and roof terms deserve separate attention because a policy can treat each risk differently. Review covered causes, exclusions, limits, and deductibles before deciding whether added protection is appropriate.
Hail and strong winds can damage roofing, siding, windows, and outdoor property. Read the wind and hail wording and identify any separate deductible or roof-related limitation stated in the policy. NOAA tracked 190 billion-dollar disasters affecting Texas among the 403 events it tracked. That statewide figure gives context, but it does not predict damage at a particular Leander address.
Flood deserves its own review. Don’t assume your homeowners policy addresses flood damage in the same way as sudden water damage from another cause. Read the exclusions and consider whether separate flood protection is appropriate for the home. Consider the property’s location and how water could reach the structure, garage, or belongings. Keep your notes with your policy documents.
Before adding an option, compare its limit, deductible, and covered events with the loss you’re trying to address. For example, confirm whether a hail claim involving roof damage is subject to special terms, rather than relying on a general summary of coverage. The actual policy wording controls. Ask a coverage question about wind, hail, or flood protection to clarify how the policy addresses those risks.
The Lewis Agency: Homeowners Insurance Policies
The Lewis Agency is an Allstate agency that helps Leander homeowners understand their homeowners insurance options and policy details. Chris Lewis, the agency owner, has approximately 25 years of homeowners insurance experience. He can explain how policy language, limits, exclusions, and deductibles relate to your home and belongings.
Consider a policy review when buying a new home, updating the property, or reconsidering protection for personal belongings. The agency can answer coverage questions and help you understand the claims process, but insurers make coverage and claim decisions. Homeowners insurance is written through Allstate, not through a multi-carrier comparison service.
If you’re ready to talk through your new home’s coverage, contact The Lewis Agency.
Make Your Next Coverage Decision with Confidence
Use your move as a chance to match your insurance details to the home you’re buying and the belongings you’re bringing. Keep policy documents, property details, and questions about specific risks together so you can discuss them clearly. New-home insurance information for Leander, Texas, is most useful when it helps you understand the decisions behind your own policy, not just a general estimate.
The Lewis Agency is an Allstate agency offering homeowners, auto, and landlords insurance policies. If you’re unsure how your home’s features or selected coverage fit together, a conversation can help clarify the policy language and questions to consider. Coverage and terms depend on the policy and individual circumstances.
Contact The Lewis Agency to discuss your home insurance questions. Take the next step at a pace that feels right for you.
Frequently Asked Questions
How much homeowners insurance do I need?
For new home insurance information in Leander, TX, base dwelling coverage on the estimated cost to rebuild, not the sale price. Include permanent upgrades, attached features, and construction details in that estimate. A lender’s minimum may meet loan terms without reflecting your rebuilding needs. Ask how the estimate accounts for custom finishes or additions.
Home policies: Replacement cost or actual cash value?
Replacement cost is based on current repair or rebuilding costs; actual cash value accounts for age and condition. For belongings, consider an older item you would need to replace, such as a sofa or television. Its current replacement price may differ from its depreciated value. Review which valuation method applies to the dwelling and personal property.
What is the average homeowners insurance cost in Leander, TX?
Leander averages depend on the coverage amount and household profile used in each estimate, so a citywide figure won’t predict every homeowner’s premium. For a more useful budget, request an estimate based on the specific property and compare it using the same coverage assumptions. Treat averages as context, not a quote for your address.
What factors affect home insurance rates in Leander?
How the home is used can affect the type of policy and coverage needed. An owner-occupied home and a property rented to tenants have different insurance needs. Have the intended occupancy, purchase details, and construction information ready when arranging coverage. If your plans change from living in the home to renting it, revisit the policy details.
Which home insurance companies serve Leander, Texas?
Company availability depends on the property and insurer. If homeowners can’t obtain coverage from regular insurers, the Texas FAIR Plan provides limited coverage for one- and two-family homes, townhouses, and condominiums. Eligibility requires refusals from at least two insurance companies. This option is intended for qualifying homeowners who cannot obtain insurance through regular insurers.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.