Homeowners Insurance Quotes and Costs in Round Rock, Texas
Explore what shapes a homeowners insurance quote Round Rock TX, how Texas and Austin costs compare, and what details to prepare for an online estimate.
A Texas cost average can provide context, but it can’t tell you what a homeowners insurance quote in Round Rock, TX, will cost. Your estimate depends on the home’s features, its location, and the coverage you choose. Statewide and Austin figures are reference points, not substitutes for a quote based on your property.
It’s reasonable to want a clear number before making a decision. But homes in the same area can have different insurance needs and rating factors, including roof age, construction, and policy details. A local estimate is more useful when it reflects the home you’re actually insuring.
This article explains what Texas and Austin cost comparisons can indicate, which details may affect rates in Round Rock, and how to get an online estimate. It also covers coverage choices to understand as you compare an estimate with your home’s needs, helping you make an informed decision without treating a broad average as a personal quote.
Key Takeaways
- Use Texas and Austin cost comparisons as context, not as a prediction of what your home will cost to insure.
- Prepare details about your home, roof, and desired coverage to make an online estimate more relevant.
- Consider how construction, roof condition, and local storm exposure may influence a Round Rock rate.
- Review what a policy says about property damage, belongings, temporary living expenses, and liability before choosing coverage.
- Ask questions about the estimate and policy details so you can make an informed decision about your home’s protection.
How Much Does Texas Home Insurance Cost?
A Texas average offers context, but it doesn’t predict the cost for a particular Round Rock home. A quote reflects the property details provided, the coverage selected, and the insurer’s underwriting.
Premium Factors
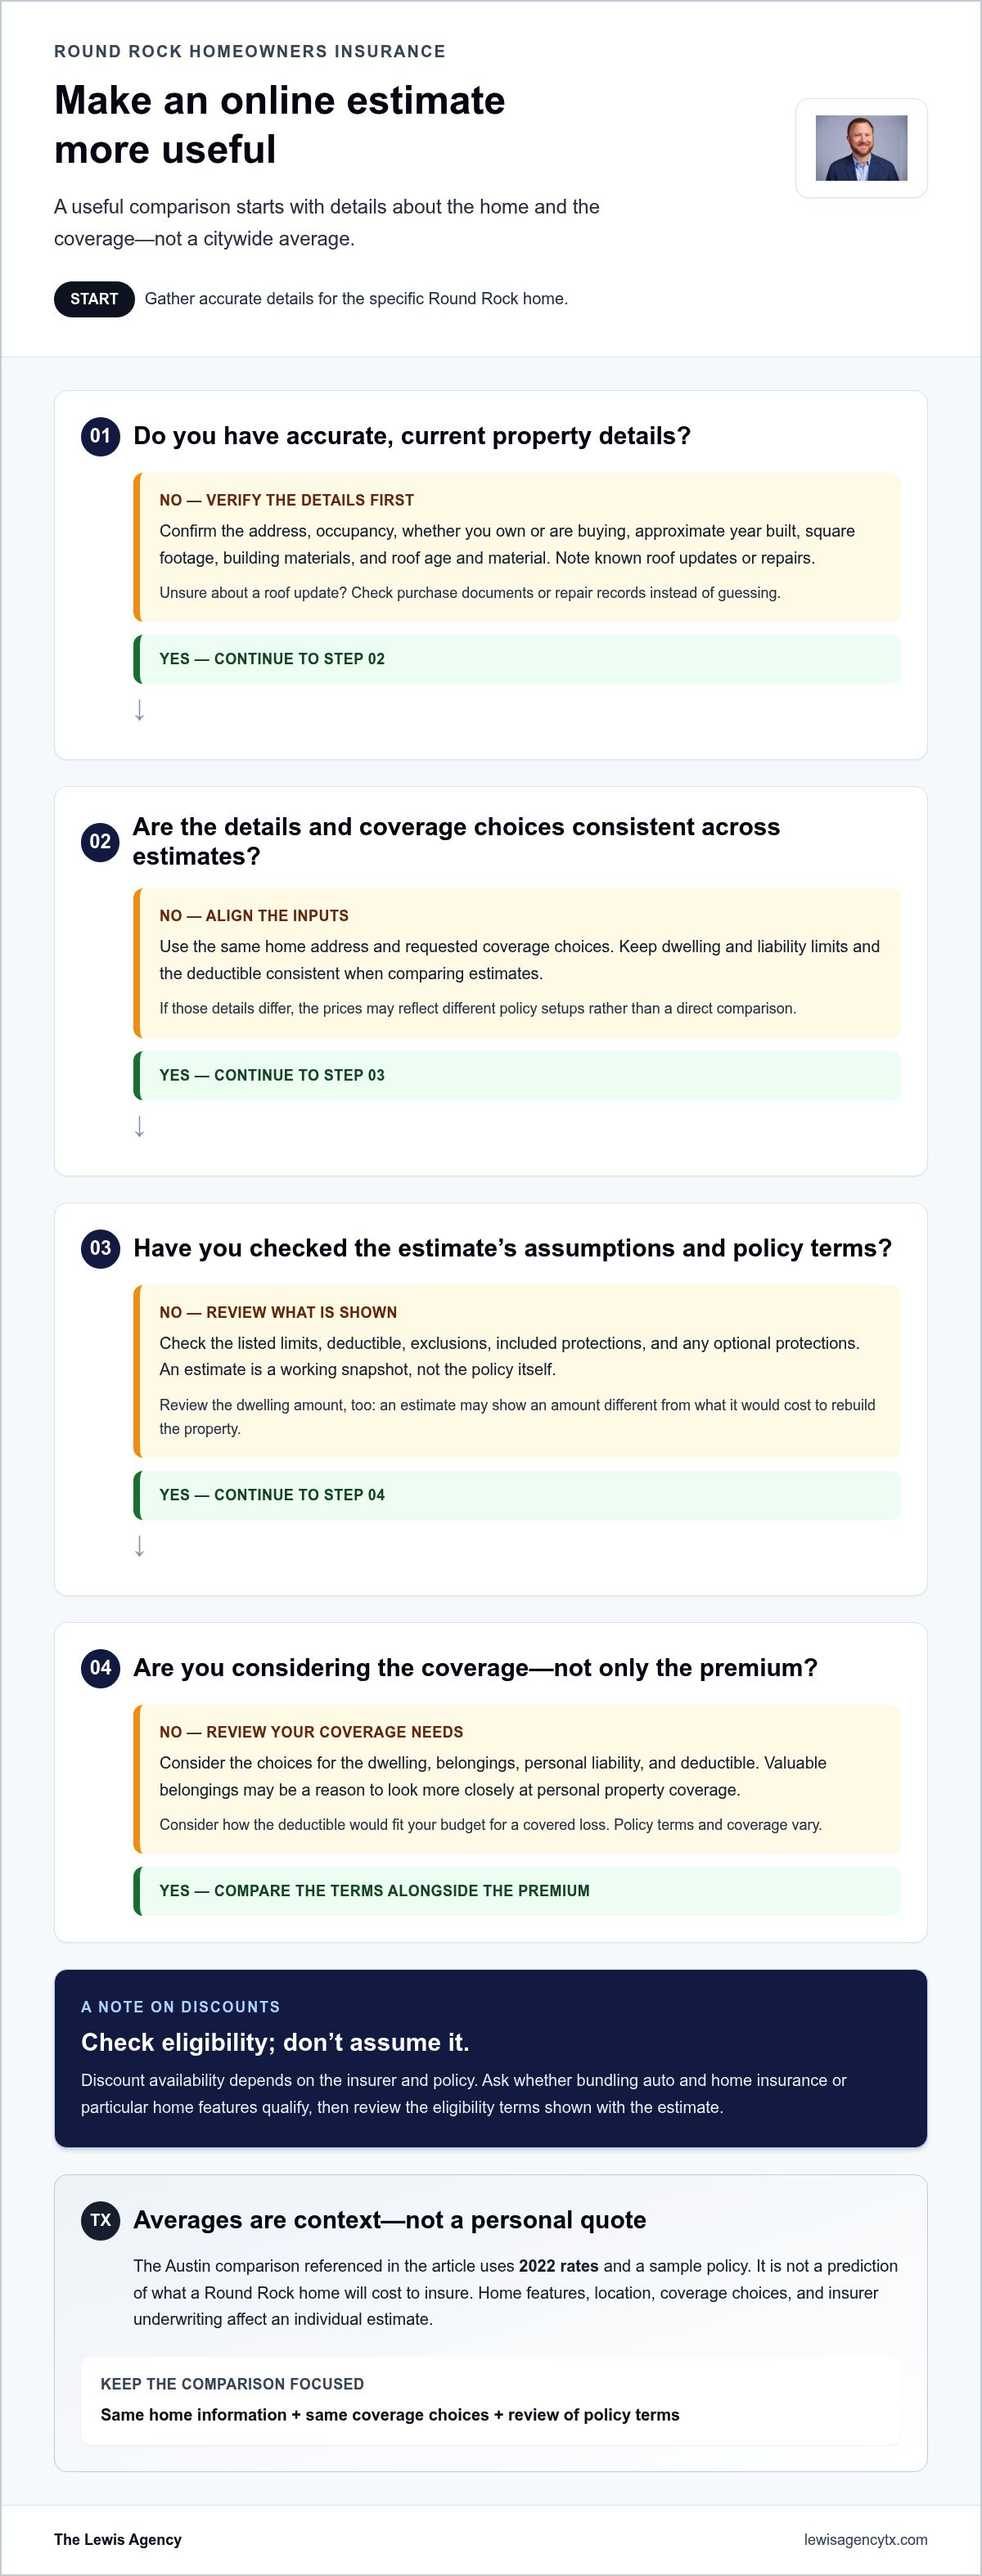
When preparing an estimate, gather accurate details about the home’s age, construction, roof condition, and address. This information describes the property being insured, though its effect on the premium depends on the insurer’s underwriting. Coverage choices matter, too, including dwelling and liability limits and the deductible.
Review those details before submitting a request. For example, note a roof replacement or major home update so the estimate reflects the property as it is now. Then check that the coverage choices reflect what you want insured, rather than choosing options based on premium alone.
Insurer Rate Comparisons
Comparing insurance estimates is most useful when each uses the same home information and coverage choices. If deductibles, limits, or selected protections differ, the prices may reflect different policy setups rather than a direct comparison.
Read the policy terms alongside the premium. Check limits, deductibles, exclusions, and included options. “Home insurance” and “homeowners insurance” are commonly used for owner-occupied homes, but the policy wording determines the coverage.
ZIP Code Rate Differences
Use the Round Rock home’s actual address when requesting an estimate. A nearby ZIP code can’t substitute for the property’s details, and estimates for different addresses may not be directly comparable.
For a useful review, keep the address and requested coverage choices consistent across estimates. This makes it easier to identify differences in quoted terms without assuming that a citywide or ZIP-code average predicts an individual premium.
Discounts and Policy Rules
What discounts can Round Rock homeowners get on insurance? Discount availability depends on the insurer and policy. Ask whether bundling auto and home insurance or particular home features qualify, then review the eligibility terms shown with the estimate.
A deductible is the amount the policyholder pays under the applicable terms for a covered claim. The declarations page lists the deductible, while exclusions describe losses or circumstances the policy doesn’t cover. Claims procedures explain steps such as reporting a loss and providing information. Read these terms together because coverage and claims rules vary by policy.
Online homeowners insurance estimates
An online estimate is a starting point for understanding coverage and price. For a Round Rock property, gather its address, construction details, roof information, and preferred coverage before you begin.
Online Estimate Details
An online estimate uses the information you enter to outline possible home insurance coverage and pricing. It may also show choices for protecting the dwelling, belongings, and personal liability. Read the assumptions carefully: incorrect details may make the estimate inaccurate for the home you intend to insure.
Think of the result as a working snapshot, not the policy itself. For example, an estimate may use a dwelling amount that differs from what it would cost to rebuild the property. Review the displayed coverage choices and note questions about limits, deductibles, exclusions, or optional protections.
Some online forms also ask whether you want to include auto insurance. That information can help assess a home-and-auto request, but bundle terms depend on the insurer and eligibility. Compare the home coverage details separately rather than focusing only on a combined estimate.
Information for a Quote
What information do I need to get a homeowners insurance quote in Round Rock, TX? Start with the property address and details about the home’s age, size, construction, and roof. You’ll also need to consider the coverage you want for the dwelling, belongings, liability, and deductible.
Before opening an online form, collect details that describe the specific house. Useful information includes:
- Property: street address, occupancy, and whether you own or are buying the home.
- Construction: approximate year built, square footage, and primary building materials.
- Roof: age, material, and any known updates or repairs.
- Protection: desired dwelling and belongings coverage, plus liability preferences.
- Insurance history: current insurer details and information requested about prior claims.
Enter each answer consistently. If you’re unsure when the roof was updated, check purchase documents or repair records instead of guessing. Accurate property details make the estimate more useful for reviewing coverage options.
After receiving an estimate, compare its listed limits and terms with your needs. For example, valuable belongings may prompt a closer look at personal property coverage. Consider how the deductible fits your budget for a covered loss, too.
For a structured review of home coverage topics, explore these homeowners insurance resources as you prepare your questions. Keep the estimate and property details together, so the next conversation can focus on the choices that matter for your Round Rock home.
Average homeowners insurance cost in Austin
Austin provides a nearby reference for understanding homeowners insurance costs, but its average isn’t a Round Rock quote. The comparison used 2022 rates and a sample policy, so its assumptions matter as much as the location.
These figures describe the comparison’s setup, not a recommendation for every homeowner. Austin homeowners with different properties, coverage choices, or deductibles may receive different estimates. A Round Rock home has its own address and property details.
Dwelling coverage relates to the insured home’s structure, while liability coverage addresses a different risk. The deductible is the amount the policyholder pays under the policy terms for a covered claim. Changing any of these choices changes what the comparison represents. Before using an Austin figure as a benchmark, identify the assumptions behind it.
For a useful comparison, keep the home details and coverage choices consistent. An Austin homeowner comparing estimates should check:
- Whether the dwelling coverage reflects the home being insured.
- Which liability limit and deductible the estimate uses.
- Whether the policy includes the same coverage options and exclusions.
- Whether the property details, including roof information, are accurate.
These details can help clarify what each estimate includes. A lower premium alone doesn’t show whether two policies offer equivalent protection. For example, estimates may use different deductibles or coverage limits. Compare policy terms alongside the price, not just the totals shown on screen.
Austin is useful as a regional reference, but it can’t replace the address-specific details of a Round Rock property. Local conditions and individual home characteristics affect how insurers assess risk. A vehicle insurance quote uses its own rating details, so vehicle costs don’t establish a home’s expected rate.
Treat the Austin sample as a starting framework. Confirm the coverage amounts, deductible, and property information used for your own estimate. Then review how the policy addresses the home and its contents. This helps Round Rock homeowners understand what an estimate measures before deciding whether its coverage fits their needs.
Factors affecting Round Rock insurance rates
For a Round Rock home, an estimate reflects the property details and coverage choices in the request. Williamson County faces severe storms, hail, and high winds that can damage homes. A roof’s condition and the selected protection are useful details to understand when reviewing an estimate.
Roof condition and age: Roof age, material, and known repairs help describe the home accurately. Hail and high winds can damage roofs, so keep repair or replacement records with your home documents. If a quote request asks about the roof, provide details about the actual property rather than relying on information about a nearby home.
Construction and systems: Newer building codes, modern electrical and plumbing systems, and newer roofs may help new-construction homes qualify for insurance discounts. Eligibility depends on the policy and insurer’s terms. Keep construction and update records available so the information you provide about the home is clear and accurate.
Rebuilding needs: Dwelling coverage concerns the insured structure, not simply its sale price. The home’s size, materials, layout, and finishes help describe what rebuilding may involve. For example, two Round Rock homes with similar sale prices can have different construction features. Review the dwelling amount against the details of the specific home.
Coverage choices: An estimate reflects the coverage options selected for the dwelling, belongings, and liability. Different limits or optional protections mean estimates describe different setups. Before comparing premiums, check that the coverage amounts and options match the protection you want to consider for the home.
Deductibles and damage records: A deductible affects what the homeowner pays for a covered loss under the policy’s terms. Keep records of storm damage, repairs, and updates together. These records can help you provide accurate property information and understand details about the home’s current condition.
Use a consistent review process for a Round Rock estimate:
- Confirm the address, roof details, and construction information.
- Record known storm damage, repairs, and system updates accurately.
- Review dwelling, belongings, and liability coverage selections.
- Compare deductibles and policy terms alongside premiums.
This approach clarifies what each estimate describes without assuming a particular feature guarantees a particular price. A newer roof or modern systems may be relevant to discount eligibility for new-construction homes, while severe weather exposure makes accurate property details especially useful. Read the exclusions and claims terms, too. A premium alone doesn’t explain how a policy responds to a specific loss. Start by checking that the estimate represents the Round Rock home and the coverage options you want to review.
Homeowners insurance in Round Rock
For a Round Rock home, set dwelling coverage based on estimated rebuilding costs, not the home’s sale price. Don’t assume a standard homeowners policy covers flooding; review its exclusions and available flood protection.
Local Homeowners Coverage
A homeowners insurance policy can cover damage to the home, belongings, and liability, depending on its terms. In Round Rock, review how the policy treats weather damage, fire, theft, and vandalism rather than assuming the same coverage applies to every cause.
Check limits for household contents and temporary living expenses after major damage. If a storm makes the home unlivable, policy terms determine whether expenses such as hotel stays or meals qualify. Endorsements can change or add coverage, so read them alongside the base policy.
Flooding deserves careful review. Water entering a home from an overflowing creek or heavy rain may be treated differently from water damage caused by a plumbing leak. The policy wording, exclusions, and any additional flood protection determine how these situations are handled. Sewer backup coverage may also require separate consideration or an endorsement.
Dwelling Coverage and Rebuilding Costs
How much dwelling coverage does a Round Rock home need based on local rebuilding costs? Choose an amount informed by the estimated cost to rebuild the structure, rather than its market value or mortgage balance. Home size, materials, layout, and finishes affect that estimate.
For example, a house with custom finishes may require different materials and labor to rebuild than a similar-sized home with simpler finishes. Review the estimate when renovating, replacing major features, or correcting outdated property details. The dwelling limit should reflect the home being insured.
Use a practical review to identify coverage gaps before comparing policy options. Check the declarations page for limits and deductibles, then read relevant exclusions and endorsements. Ask how the policy addresses hail or wind damage, water losses, belongings, and liability. A named storm risk alone doesn’t establish whether a particular loss is covered.
Also consider what happens if repairs prevent you from living at home. Review any coverage for temporary relocation and understand its terms and limits. For personal property, check whether the policy’s settlement basis matches your expectations. Depending on the contract, replacement value and actual cash value can produce different claim calculations.
Round Rock homeowners can use the homeowners insurance resource center to prepare for a policy review. Bring questions about local weather exposure, dwelling limits, flood exclusions, sewer backups, and endorsements. A clear review connects the home’s rebuilding needs with the protections and limits written into its insurance policy.
The Lewis Agency: Homeowners Insurance Policies
The Lewis Agency is an Allstate agency offering homeowners insurance policies for Round Rock homeowners. If you’re weighing an estimate, reviewing dwelling limits, or trying to understand policy language, the agency can explain coverage options and answer questions about your policy.
Chris Lewis has more than 25 years of insurance experience and focuses on helping Central Texas homeowners understand their coverage before they need it. The agency can also help you understand the claims process, though claim decisions and payments are made by the insurer.
If you’re considering home and auto coverage together, ask how the available options apply to your situation. To talk through a homeowners policy or request a quote, contact The Lewis Agency.
Make your next coverage review count
Use your estimate as the starting point for a practical conversation, not as a decision based on one number alone. Before requesting a homeowners insurance quote in Round Rock, Texas, note home updates, changes in how the property is used, and questions about policy language. That preparation helps focus the discussion on what you want your coverage to do.
As your home and household change, revisit those questions. A renovation, new roof, or rental arrangement can change which details belong in your insurance review. The Lewis Agency offers homeowners insurance policies, Auto Insurance, and Landlords Insurance, so you can discuss related property and household coverage needs in one conversation.
For a quote or help understanding your policy options, contact The Lewis Agency. Take the next step at your own pace, with your questions ready.
Frequently Asked Questions
Are insurance rates higher in Round Rock than other areas?
A city name alone isn’t enough to conclude that Round Rock rates are higher or lower. A meaningful comparison requires estimates for the homes being considered, with comparable coverage choices and deductibles. For example, if you’re comparing your Round Rock home with a relative’s home in Austin, make sure both estimates describe the relevant property and policy terms before drawing a conclusion.
Which insurers offer homeowners insurance quotes in Round Rock, TX?
The Lewis Agency is an Allstate agency and offers homeowners insurance policies through Allstate. It doesn’t shop homeowners insurance among multiple carriers. If you request an estimate, have the Round Rock property details and coverage questions ready. Review the resulting policy documents for the insurer, limits, deductibles, and terms that apply to the specific offer before making a decision.
How do homeowners insurance rates in Round Rock compare with Austin and the Texas average?
The article’s Austin and Texas figures come from a comparison using 2022 rates, while a Round Rock quote is based on the specific home and requested policy details. The Austin sample and statewide average aren’t necessarily like-for-like measures for a particular property. Treat them as historical context, then use an estimate for the Round Rock address when making a current household decision.
What coverage limits and policy types are available for Round Rock homeowners?
Homeowners can review limits for the dwelling, belongings, liability, and additional living expenses, along with policy forms and endorsements offered for their needs. HO-3 is a commonly referenced homeowners policy form, but actual Texas forms and coverage vary by insurer. For example, a homeowner with a finished garage or custom interior features can pay particular attention to how the policy describes the insured property and applicable limits.
What factors affect homeowners insurance rates in Round Rock, including home age, roof, and claims history?
Home age, roof details, and claims history are useful topics when reviewing a home insurance estimate, but those details alone can’t determine their effect on a particular rate. Keep roof invoices, repair records, and relevant claim documents together. Accurate records help you describe the property and its history when completing a quote request or reviewing policy information.
How do hail, wind, tornado, and flood risks affect homeowners insurance in Round Rock?
Severe storms, hail, and high winds can damage homes in Round Rock and Williamson County. Review the policy wording for how it addresses storm-related damage, including applicable exclusions or deductibles. Flooding requires separate attention because coverage depends on the policy and any additional protection selected. Don’t assume a policy covering other water damage also covers floodwater entering from outside.
How can I compare homeowners insurance quotes and choose a policy in Round Rock?
Compare estimates using the same property information, requested limits, deductibles, and options. Then read the policy terms instead of choosing by premium alone. For example, check how each estimate describes the dwelling, belongings, liability, and relevant exclusions. If an estimate has an incorrect roof date or other home detail, correct it before relying on the comparison.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.