Dwelling Coverage Homeowners Insurance Texas: Complete Policy Guide (2026)
One of the most important numbers on a Texas homeowners insurance policy is the dwelling coverage limit—but it's also one of the easiest to misunderstand. Your home's insured value isn't necessarily the same as its market value, tax appraisal or purchase price.
In reality, market values and physical construction expenses are entirely different calculations. You don't want to pay high premiums for bloated protection, but you also cannot afford an unexpected shortfall when severe hailstorms strike. In this guide, you'll learn how Coverage A protects your home's structure, why rebuild expenses differ from market valuations, and how to establish accurate policy limits. We'll examine how replacement cost mechanics work, unpack percentage-based hail deductibles, and help you evaluate your coverage options with total confidence.
Key Takeaways
- Learn how dwelling coverage homeowners insurance Texas policies provide essential structural protection for your foundation, framing, and roof system after covered losses.
- Discover why real estate market value and property tax appraisals differ significantly from the actual labor and material costs required to reconstruct your home.
- Understand the vital financial distinctions between replacement cost settlements and actual cash value claim payouts, particularly for aging roof systems.
- Find out how evolving municipal building codes across Central Texas impact your repair requirements and why regular limit reviews prevent costly out-of-pocket shortfalls.
What Is Dwelling Coverage in Texas Homeowners Insurance?
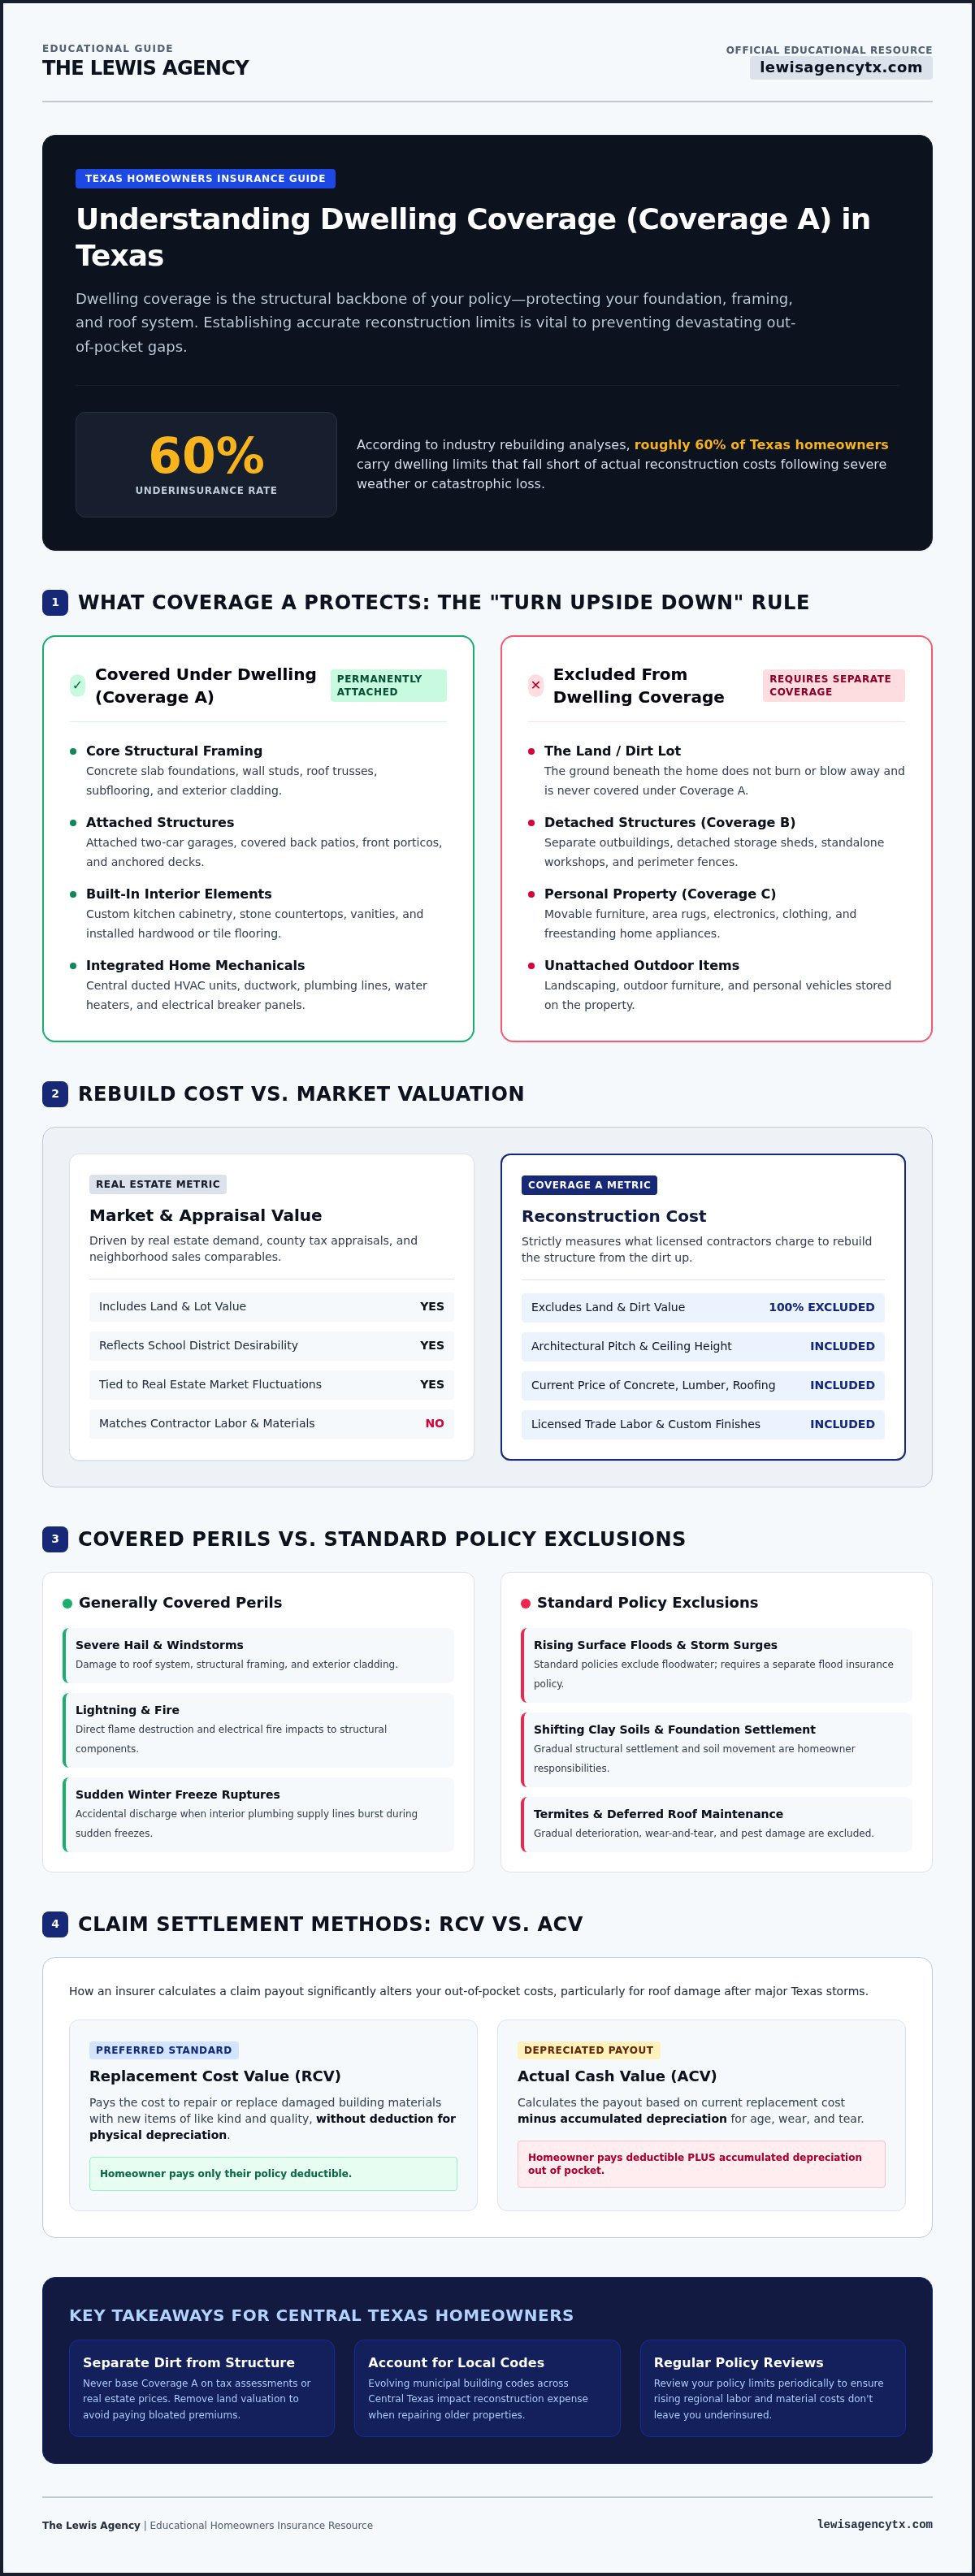
Dwelling coverage, officially designated as Coverage A, forms the structural backbone of your policy. It pays to repair or rebuild the physical structure of your primary residence if damaged or destroyed by a covered loss. Rather than protecting the land beneath your feet or the furniture inside your rooms, this specific coverage focuses entirely on the bricks, mortar, and framing that keep a roof over your head.
In standard homeowners insurance policies, the dwelling limit serves as the baseline for the rest of your protection. The dollar amount you select for Coverage A directly dictates the formulaic limits available for other structures, personal property, and temporary living expenses. That makes setting an accurate limit for your dwelling coverage homeowners insurance Texas policy one of the most critical decisions you will make as a homeowner.
What Dwelling Coverage Protects Inside and Outside
Coverage A extends beyond the exterior siding to include permanently installed fixtures that make the house functional. If you could turn the house upside down, anything that stays attached typically falls under dwelling protection:
- Core structural framing: Concrete slab foundations, wall studs, roof trusses, subflooring, and exterior cladding.
- Attached structures: Attached two-car garages, covered back patios, front porticos, and permanently anchored decks.
- Built-in interior elements: Custom kitchen cabinetry, stone countertops, vanities, and installed hardwood or tile flooring.
- Integrated home mechanicals: Central ducted HVAC units, ductwork, plumbing lines, water heaters, and electrical breaker panels.
Items not permanently joined to the structure fall outside this protection. Separate outbuildings like detached storage sheds, standalone workshops, and perimeter fences require separate other structures coverage, while furniture and rugs belong to personal property.
Common Covered Perils vs. Standard Policy Exclusions
Texas weather presents substantial hazards to residential framing and roofs. Understanding how your dwelling coverage homeowners insurance Texas policy responds to sudden regional weather events ensures you know where policy boundaries lie.
Most standard policies cover perils like lightning, fire, high winds, and severe hail damage. They also generally cover sudden, accidental water discharge, such as an interior supply line that ruptures during an unexpected winter freeze. However, standard policies carry strict exclusions. Rising surface floodwaters, river overflows, and storm surges are excluded, requiring separate flood insurance policies. Similarly, gradual structural issues, such as foundation cracks caused by shifting clay soils, termite damage, or deferred roof maintenance, remain the homeowner's responsibility.
Dwelling Rebuild Value vs. Market Value in Texas
One common mistake homeowners make is assuming market value equals reconstruction cost. When your county appraisal district sends its annual property valuation, that total reflects buyer demand, school district boundaries, and neighborhood appeal. Your policy's Coverage A limit, however, exists strictly to purchase physical materials and hire licensed trades to reconstruct your home from the dirt up. As highlighted in the Texas Department of Insurance Home insurance guide, your structural limits need to reflect true replacement expense rather than real estate transactions or outstanding mortgage balances.
Why Real Estate Market Valuations Mislead Homeowners
Real estate appraisals bundle the value of your physical home together with the raw land it occupies. When a total catastrophe strikes, the lot beneath your home does not burn away. Factoring land value into your dwelling limits results in purchasing unnecessary coverage and paying inflated premiums for dirt that cannot be destroyed. Conversely, if local property sales cool down, the price of concrete, roofing, and skilled trade labor does not suddenly drop alongside home prices.
Key Factors Driving Texas Reconstruction Expenses
Calculating accurate replacement limits requires looking directly at physical construction variables rather than neighborhood sales comparables. Several regional elements determine what contractors charge to restore a damaged property:
- Architectural complexity: Steep roof pitches, custom masonry, high ceilings, and non-standard floor plans require specialized installation labor.
- Interior finish tiers: Rebuilding basic builder-grade trim involves different material expenses than replicating custom hardwood cabinetry, imported tile, and solid stone surfaces.
- Suburban trade demand: Fast-growing Central Texas communities like Leander, Liberty Hill, and Pflugerville experience high competition for subcontracting crews, which directly affects local labor rates.
- Demolition and debris haul-away: Before a builder pours fresh concrete, heavy equipment must break down damaged structures, clear hazardous rubble, and haul away debris to designated landfills.
If you aren't sure whether your current policy accounts for these regional construction realities, sitting down with The Lewis Agency can help you evaluate your property's specific characteristics and verify your numbers against local building trends.
Replacement Cost vs. Actual Cash Value on Texas Homes
Setting an accurate limit is only half the equation; the claim settlement method written into your contract determines how disbursements are calculated after a loss. When damage occurs, insurance carriers settle structural claims under either Actual Cash Value (ACV) or Replacement Cost Value (RCV). Knowing which provision applies to your structure protects your household from unexpected out-of-pocket bills.
Industry guidance on calculating your home's replacement cost emphasizes meeting your insurer's coinsurance requirements. According to the Texas Department of Insurance, most insurers require homeowners to maintain coverage equal to at least 80% of the home's total replacement cost. Falling short of this threshold can trigger coinsurance penalties, meaning the carrier reduces claim payouts on partial losses proportionally, leaving you responsible for the remaining balance.
Comparing Actual Cash Value and Replacement Cost
Actual cash value subtracts physical depreciation, factoring in the age and prior condition of your building materials before issuing payment. If an older roof sustains severe damage under an ACV provision, the insurer subtracts years of normal wear, paying only its current value. Replacement cost coverage pays to rebuild or replace damaged property with new materials of like kind and quality, without deductions for deterioration. Because of this added financial security, mortgage lenders routinely require replacement cost coverage on residential loans.
Extended Replacement Cost and Inflation Guard Endorsements
Severe storm outbreaks frequently generate localized shortages of building materials and trade labor. When widespread hail damages hundreds of homes in a single community, local construction costs can surge overnight, occasionally exceeding initial estimates.
Adding an extended replacement cost endorsement gives your dwelling coverage homeowners insurance Texas policy an extra safety buffer. Depending on policy terms, this endorsement provides an additional percentage of structural coverage above your stated Coverage A limit if localized demand drives up reconstruction expenses. Pairing this buffer with an inflation guard endorsement helps ensure your base limits steadily adjust over time, preserving your financial protection against ongoing price increases.
Tailoring Dwelling Coverage to Texas Perils and Local Codes
Every region presents its own set of environmental threats, but the Lone Star State is notorious for volatile weather patterns. From severe straight-line winds and tornadoes to spring hail swarms and bitter winter freezes, your home's structural framing and roof endure extraordinary strain. Structuring your dwelling coverage homeowners insurance Texas policy requires tailoring your protections to these specific regional realities rather than settling for a generic policy template.
Managing Hail Risks and Percentage Deductibles
Severe convective storms, hail, and high winds generate over 60% of all Texas homeowners insurance losses. Because hail risk is so high across the state, Texas insurers commonly write separate wind and hail deductibles structured as a percentage rather than a flat dollar amount. Crucially, this percentage applies directly to your Coverage A dwelling limit, not the total amount of storm damage.
For example, if your dwelling limit sits at $400,000 and your policy includes a 2% wind and hail deductible, your out-of-pocket obligation is $8,000 before insurance proceeds cover a single dollar of roof repairs. Under Texas Business & Commerce Code § 27.02, it is illegal for roofing contractors to absorb, rebate, or waive this deductible, meaning policyholders must pay this amount themselves. Keeping your baseline dwelling limit accurate prevents your percentage deductible from inflating unnecessarily while still ensuring adequate reconstruction funds.
The Role of Ordinance or Law Coverage in Growing Communities
Standard home policies agree to rebuild damaged structures back to their original specifications. However, fast-growing municipalities across Travis and Williamson counties regularly update local building standards. Cities like Cedar Park, Buda, and Round Rock frequently adopt newer revisions of the International Residential Code (IRC) along with stricter energy conservation mandates.
If extensive repairs require upgraded electrical panels, modified roof decking fasteners, or modern plumbing pipe configurations, standard policies typically provide little or no funding for those mandatory improvements. Adding an Ordinance or Law endorsement bridges this financial gap, providing dedicated funds to cover the code-mandated upgrades required by municipal inspectors during reconstruction.
Taking time to review your policy details can save your family thousands of dollars after a storm. If you want a clear, personalized assessment of your structural limits and roof deductibles, contact The Lewis Agency to walk through your current homeowners coverage.
How to Review and Adjust Your Texas Dwelling Coverage Limits
Homes evolve over time, and regional construction expenses shift alongside them. Leaving a policy on autopilot for years creates a dangerous gap between your coverage limits and actual local building expenses. Maintaining the right dwelling coverage homeowners insurance Texas policy requires ongoing attention rather than a one-time estimate. Instead of relying on rough square-footage guesses, accurate structural evaluations utilize comprehensive replacement cost estimators that account for your home's unique layout, foundation, and interior craftsmanship.
Triggers That Require Adjusting Your Coverage A Limits
Everyday improvements and market shifts alter your replacement needs. You should reach out to adjust your Coverage A baseline whenever you experience one of these key milestones:
- Interior remodeling: Upgrading to custom solid wood cabinetry, luxury bathroom fixtures, or high-end stone countertops increases the physical cost required to restore damaged rooms.
- Added square footage: Finishing a bonus room over your garage, enclosing a back patio, or constructing an attached guest suite expands your total rebuild footprint.
- Mechanical installations: Adding permanent infrastructure like whole-home standby generators, multi-stage HVAC systems, or built-in water filtration systems adds substantial replacement value.
- Regional cost shifts: General changes in subcontractor availability and supply chain pricing across Williamson and Travis counties can quietly leave older policy limits behind.
Working with The Lewis Agency on Your Coverage
Having experienced local guidance makes evaluating structural protection straightforward and stress-free. As a dedicated Allstate agency serving Central Texas communities like Austin, Round Rock, Cedar Park, Leander, and Pflugerville, The Lewis Agency understands how regional weather exposures and municipal building standards affect your home.
Agent Chris Lewis takes the time to sit down with you, examine your home's specific building features, and ensure your structural limits and deductibles work together effectively. When you want clear answers and personalized attention, schedule a consultation with The Lewis Agency to review your Texas homeowners policy and ensure your coverage matches your family's needs.
Protect Your Central Texas Home with the Right Structural Limits
Securing adequate dwelling coverage homeowners insurance Texas policies offer isn't about matching your neighbor's policy or relying on county tax appraisals. It's about making sure your Coverage A limit realistically reflects the current materials, specialized labor, and building codes required to restore your home after an unexpected catastrophe. Balancing replacement cost provisions with manageable percentage deductibles ensures you aren't caught off guard when severe weather rolls across the state.
You don't have to decipher these complex structural details by yourself. As a dedicated local Allstate agency serving Austin, Round Rock, Cedar Park, Leander, and Pflugerville, The Lewis Agency provides personalized coverage reviews tailored to regional construction trends. Agent Chris Lewis brings experienced, neighborly guidance to every conversation, helping you evaluate your property's specific rebuild requirements with total clarity.
Take the uncertainty out of your homeowners policy. Review your Texas homeowners coverage with The Lewis Agency today, and enjoy the lasting confidence that comes from knowing your home is thoroughly protected.
Frequently Asked Questions
How do I know if my Texas dwelling coverage limit is high enough?
Your limit is high enough if it matches a professional replacement cost calculation rather than your home's purchase price. A detailed replacement cost estimate examines your square footage, roof pitch, custom finishes, and local trade wages across Central Texas cities like Round Rock and Leander. Annual reviews ensure your dwelling coverage homeowners insurance Texas policy limit keeps pace with shifts in material costs and regional building expenses.
Is dwelling coverage based on the county property tax appraisal value in Texas?
No, dwelling coverage is never based on county property tax appraisal numbers. County appraisals evaluate the market value of your property, which includes both the physical house and the underlying parcel of land. Rebuild insurance strictly covers the labor, equipment, and building materials needed to reconstruct the structural dwelling. Because your land doesn't disappear during a loss, tying your policy limit to tax records results in inaccurate coverage.
What happens if my home costs more to rebuild than my dwelling coverage limit?
If rebuild expenses exceed your limit, you must pay the remaining balance out of pocket. Standard policies pay claims only up to the stated Coverage A limit on your declarations page. However, adding an extended replacement cost endorsement provides an additional percentage buffer above your base limit if localized disasters cause sudden surges in labor and lumber costs. Reviewing your policy prevents catastrophic out-of-pocket shortfalls during major community rebuilding phases.
Does dwelling insurance cover roof damage caused by severe Texas hailstorms?
Yes, standard policies generally cover hail damage to roofs, but specific settlement terms depend on your policy language. Hail is typically a covered peril, but your claim payout depends on whether your policy pays replacement cost or actual cash value based on roof age. Texas policies also apply separate wind and hail deductibles, which require an out-of-pocket percentage payment based on your total dwelling limit before claim funds are released.
Can I lower my dwelling coverage to reduce my homeowners insurance premium?
You shouldn't artificially lower your Coverage A limit simply to reduce your premium. Insurers generally require coverage equal to at least 80% of replacement costs to avoid coinsurance penalties on partial claims. Dropping your structural limit below true rebuild expenses exposes your family to major out-of-pocket liabilities. Instead of cutting essential dwelling protection, explore adjusting your policy deductibles or reviewing eligible policy credits with your local agent.
Does dwelling insurance cover foundation damage caused by shifting Texas soil?
Standard policies exclude foundation damage caused by normal soil expansion, contraction, or settling. The expansive clay soils common across Austin, Pflugerville, and Williamson County frequently cause ground movement, but standard Texas home policies treat this as gradual wear. However, if foundation cracking results directly from an accidental, sudden plumbing freeze or interior pipe rupture, limited coverage may apply depending on your specific policy endorsements and water damage riders.
What is the difference between dwelling coverage and other structures coverage?
Dwelling coverage protects your primary residence and permanently attached features, while other structures coverage protects unattached outbuildings. Your dwelling limit pays for repairs to your house, roof, foundation, and attached garage. Other structures coverage, known as Coverage B, specifically covers separate physical assets on your property grounds, such as detached storage sheds, standalone workshops, gazebos, and perimeter fencing, typically set as a default percentage of your dwelling limit.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.