Water Sewer Backup Coverage and What It May Cost You
Learn what can cause a water sewer backup, how homeowners insurance may respond, and what affects optional endorsement costs for Austin and Central Texas homes.
What if a sewer backup damages your home and your homeowners policy does not cover the cleanup? Water or sewer backup can leave you facing repair costs, and coverage may depend on whether your policy includes a relevant endorsement. In Austin and across Central Texas, understanding your policy before a backup happens can help you spot potential gaps.
It is reasonable to expect homeowners insurance to help after water damage, but backup coverage may differ from coverage for other sudden, accidental losses. This article explains common causes of sewer backups, what homeowners insurance may cover, and how an optional endorsement could help. It also explains what can affect the endorsement’s cost and why its limits and terms matter.
Key Takeaways
- Learn how tree roots, blocked pipes, and heavy rain can contribute to sewage backups, and which everyday habits may reduce blockage risk.
- Understand why standard homeowners coverage may not include sewer backup damage and what policy details can affect coverage.
- See how an optional backup endorsement may help with certain losses, and why its terms and limits matter.
- Get a clearer sense of what can affect endorsement costs and when reviewing your policy may help you spot a coverage gap.
What Causes a Sewage Backup?
A sewage backup occurs when wastewater cannot move through the sewer system and returns through household drains. In Austin, heavy rain, blocked pipes, or damage to a sewer line can contribute to the problem.
Common Sewer Backup Causes
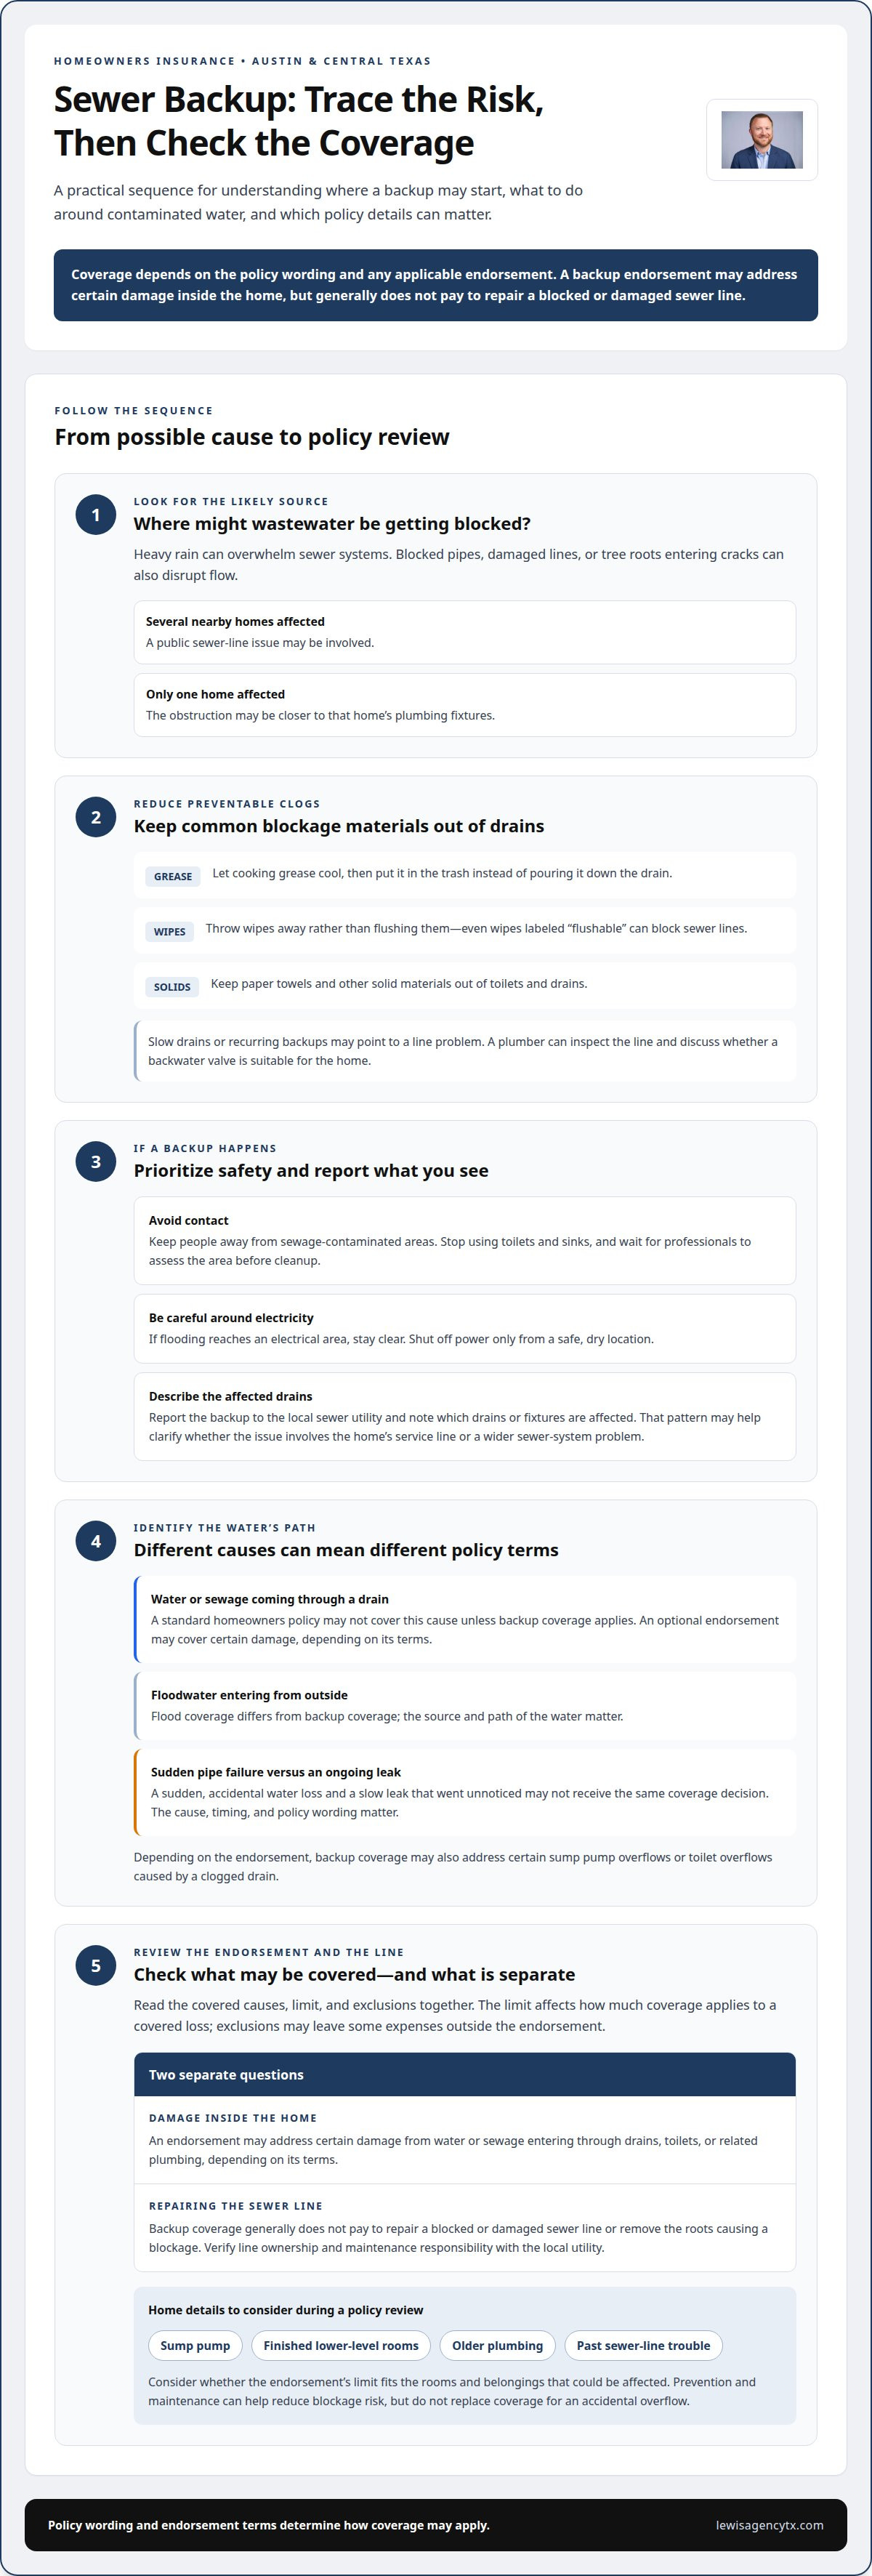
Backups can start in a home’s service line or in a municipal sewer main. Heavy rainfall may overwhelm sewer systems, while blockages can stop wastewater from flowing away. If several nearby homes report similar symptoms, a public-line issue may be involved. If only one home is affected, the obstruction may be closer to its plumbing fixtures. Noting this pattern can help direct your report.
Clogs From Grease and Wipes
Cooking grease can cool and harden inside pipes, while wipes can collect with other waste and obstruct flow. Paper towels and other solid materials can also contribute to clogs. Even wipes labeled flushable can block sewer lines. Let grease cool before putting it in the trash, and throw wipes and paper towels away instead of flushing them. These habits help reduce preventable drain clogs.
Pipe Damage and Tree Roots
Cracks or aging pipes can let tree roots enter sewer lines and restrict wastewater flow. A damaged pipe can also trap debris or disrupt drainage. Slow drains or recurring backups may point to a line problem that needs assessment. A plumber can inspect the line and discuss whether a backwater valve is suitable for your home.
After a backup, avoid contact with contaminated water and stop using toilets and sinks. If flooding reaches an electrical area, stay clear. Shut off power only from a safe, dry location.
Keep people away from sewage-contaminated areas until professionals assess them. Wait to clean up until the source is corrected and sewage has drained. Contaminated areas need appropriate disinfection.
To help prevent backups, keep grease, wipes, paper towels, and other solids out of drains, and address noticeable tree roots near sewer lines.
If a backup occurs at your Austin home, report it to the local sewer utility and describe which drains or fixtures are affected. Those details can help clarify whether the issue may involve your home’s service line or a wider sewer-system problem.
Does Homeowners Insurance Cover Sewer Backup Costs?
Homeowners insurance may not cover sewage entering through a drain unless the policy includes backup coverage. The policy wording and any applicable endorsement determine what a covered loss may include.
Homeowners Policy Coverage
Water backup coverage is optional protection that may cover certain damage from water or sewage coming through drains. It matters because a clogged sewer line can send contaminated water into a home, while a standard policy may not cover that cause of damage. Coverage may also apply to some sump pump overflows or toilet overflows caused by a clogged drain.
A backup endorsement generally addresses water entering from plumbing fixtures or drains, rather than outside flooding. That distinction matters in Austin and Central Texas, where the water’s source and path affect which policy terms apply. Review the wording for covered causes, limits, and exclusions.
Standard Policy Exclusions
A standard homeowners policy may exclude damage from a sewer backup if no backup endorsement applies. As a result, cleanup and repairs to flooring, walls, furniture, and other belongings may fall outside the coverage available for that loss. Read the exclusion carefully, including how the policy treats water forced through a toilet, shower, or floor drain.
Backup coverage generally does not pay to repair a sewer line or remove tree roots that caused a blockage. Depending on the location and circumstances, a homeowner may be responsible for maintaining the private service line, while the utility may handle its own main. Verify line ownership and maintenance responsibility with your local utility. Coverage for resulting damage and responsibility for pipe repairs are separate questions.
Water Damage Coverage
Homeowners insurance may cover water damage that is sudden and accidental, while ongoing leaks or damage related to poor maintenance are generally treated differently. For example, a sudden pipe failure and a slow leak that went unnoticed may not receive the same coverage decision. The cause, timing, and policy wording all matter.
Flood coverage also differs from backup coverage: floodwater enters from outside, while backup water comes through drains or related systems. For help understanding the wording in a homeowners policy, you can ask a coverage question.
Optional water and sewer backup endorsements
A water backup endorsement adds protection that a standard homeowners policy may not provide for certain backup losses. It may be relevant for Austin-area homes with a basement, sump pump, older pipes, or a sewer lateral vulnerable to blockages.
Depending on its terms, the endorsement may cover damage when sewage or water enters through drains, toilets, or related plumbing. Coverage may also include a sump pump overflow or failure of a system that removes subsurface water near the foundation. These situations differ, so consider which systems your home has. For example, a finished basement may contain flooring and belongings that need attention after an overflow.
Review the endorsement’s covered causes, limit, and exclusions together. The limit affects how much coverage applies to a covered loss, while exclusions may leave some expenses outside the endorsement. Backup coverage generally addresses damage inside the home, not repairs to a blocked or damaged sewer line. If roots block the service line between your house and the utility main, repairing that pipe is separate from covering damage to your home.
For a practical review, list your home’s risk factors: a sump pump, finished lower-level rooms, older plumbing, or a sewer line with a history of trouble. Then consider whether the endorsement’s limit fits the rooms and belongings that could be affected. Keep maintenance and prevention separate from insurance: clearing debris from a sump pump pit and keeping grease and wipes out of drains can help prevent blockages, but does not replace coverage for an accidental overflow.
Use the homeowners insurance resources to understand policy terms and prepare focused questions about backup protection.
The Lewis Agency
The Lewis Agency helps Austin and Central Texas homeowners understand how their policies address sewer backups and optional endorsements. If you are unsure whether backup protection is included, what limits apply, or how the wording treats a sump pump overflow, a policy review can clarify what your documents say. The agency explains coverage language and the claims process, while the insurer makes coverage and claim decisions.
Bring questions about how a specific backup scenario relates to your policy, including whether damage to belongings and repairs to a private sewer line are treated separately. Clear answers can help you understand your coverage before a loss and identify points that may need attention.
Contact The Lewis Agency to discuss your homeowners coverage questions.
Make Your Next Policy Review More Useful
Use your next policy review to connect coverage questions to how you use your home. Note changes, such as finishing a room or adding equipment that handles water, so the review can focus on what matters to your household. Ask how water and sewer backup coverage is described, what the endorsement costs, and which terms affect the price. The Lewis Agency can explain policy wording and the claims process; coverage and claim decisions remain with the insurer.
The Lewis Agency offers Homeowners Insurance Policies, Auto Insurance, and Landlords Insurance. If you’d like to talk through your homeowners coverage, contact The Lewis Agency. A thoughtful conversation can help you take your next step with greater clarity.
Frequently Asked Questions
What does water backup coverage include?
Water backup coverage may help with certain damage and cleanup expenses after water or sewage backs up into a home. The endorsement wording determines which property and expenses qualify. For example, a claim involving damaged flooring may be handled differently from one involving personal belongings. Review the covered costs, exclusions, and limit together to understand how the protection applies to your home.
What affects the cost of water removal and sewage remediation?
Cleanup and remediation costs depend on the affected area, how far contaminated water spread, and which materials need removal or treatment. A small area with hard surfaces may require different work from a finished basement with contaminated carpet and furnishings. The time before cleanup begins and the steps needed to address odors can also affect the work involved.
What Does it Mean When Your Sewer Backs Up in the basement?
It means wastewater is entering the basement through a drain or other plumbing connection instead of flowing away from the home. Because basements often have low-lying drains and finished materials, the source and route of the water matter. A drain backup differs from water entering through basement walls, so noting where water appeared can help clarify what happened.
What are signs of a potential sewer backup?
Gurgling drains, water rising from a floor drain, or water backing up in a shower or bathtub can signal a developing problem. Water coming from the sewer cleanout is another warning sign. Note which fixtures are affected and whether the symptoms occur together. That information can help distinguish a localized fixture issue from a wider sewer-line concern.
What is a water or sewer backup?
A water or sewer backup occurs when wastewater or water reverses direction and enters a home through drains or connected plumbing. It may involve sewage from a sewer line or water from a sump pump system. This differs from outside floodwater entering the home. Identifying the source can help you understand which policy terms and protections may apply.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.

Austin Homeowners Insurance: Complete 2026 Coverage Guide
Need reliable homeowners insurance Austin coverage? Explore 2026 policy insights on hail deductibles, roof schedules, and protecting your Central Texas home.
What if the deductible on your policy doesn't work the way you expected when a severe hailstorm hits your neighborhood? For many Central Texas residents, shopping for reliable homeowners insurance austin coverage through generic national websites often creates more questions than answers. Online algorithms routinely overlook regional realities, leaving homeowners to untangle separate percentage-based storm deductibles, unexpected roof depreciation schedules, and confusing rules around freeze damage on their own.
It can feel overwhelming to sort through policy fine print, but protecting your biggest investment shouldn't involve guesswork. You can protect your Central Texas home against hail, storms, and local property risks with tailored homeowners coverage designed for our specific climate. In this guide, we'll walk through how local reconstruction expenses shape your dwelling limits, how wind and water claims are handled under Texas guidelines, and the key coverage details you should review to keep your household secure.
Key Takeaways
- Understand what standard policies protect and identify the common Central Texas weather perils that require closer policy attention.
- Learn how regional storm patterns influence homeowners insurance austin coverage, particularly regarding roof settlement terms and depreciation schedules.
- Demystify percentage-based wind and hail deductibles so you clearly understand your out-of-pocket responsibilities before severe weather strikes.
- Establish an accurate dwelling coverage limit based on local reconstruction expenses rather than fluctuating real estate market values.
- Discover how tailored guidance from a dedicated local Allstate agent helps you safeguard your home without the guesswork of generic quote tools.
What Does Homeowners Insurance in Austin Actually Cover?
Most single-family homes across Central Texas rely on an HO-3 special form policy. Under the standard homeowners insurance policy structure, coverage splits into distinct categories for your physical structure, personal belongings, liability risks, and living disruptions. Choosing the right homeowners insurance austin policy requires understanding where baseline protections end and where local regional conditions demand closer attention. A baseline policy provides essential safeguards, but it works best when tailored to the specific risks of your property.
Dwelling Protection and Extended Replacement Cost
Coverage A dwelling protection covers the physical structure of your house after sudden, covered events like fire, hail, or lightning. Detached fences, sheds, and detached garages fall under separate other structures coverage. Your dwelling limit must reflect regional labor and rebuilding expenses rather than local real estate market valuations.
Central Texas soils present unique structural challenges. Standard policies routinely exclude earth movement and settling, meaning slab leaks and foundation shifts often require specific policy endorsements. Adding an extended replacement cost endorsement gives your dwelling limit an extra buffer, helping absorb sudden surges in local contractor pricing and materials following widespread severe weather.
Personal Property, Liability, and Additional Living Expenses
Inside your home, personal property coverage helps repair or replace belongings like furniture, clothing, and electronics damaged by covered perils. Policy terms determine whether these items are settled at actual cash value or full replacement cost, with specialty endorsements available for high-value items.
Personal liability coverage safeguards your family's financial assets if a visitor is injured on your property or if you accidentally cause damage to someone else's property. If a covered peril renders your home uninhabitable, loss of use coverage, also known as Additional Living Expenses, reimburses temporary lodging and meal expenses while repairs take place. Because policy forms and endorsements vary between carriers, reviewing these limits carefully ensures your family avoids unexpected out-of-pocket gaps.
Central Texas Weather Hazards: Hail, Freezes, and Severe Storms
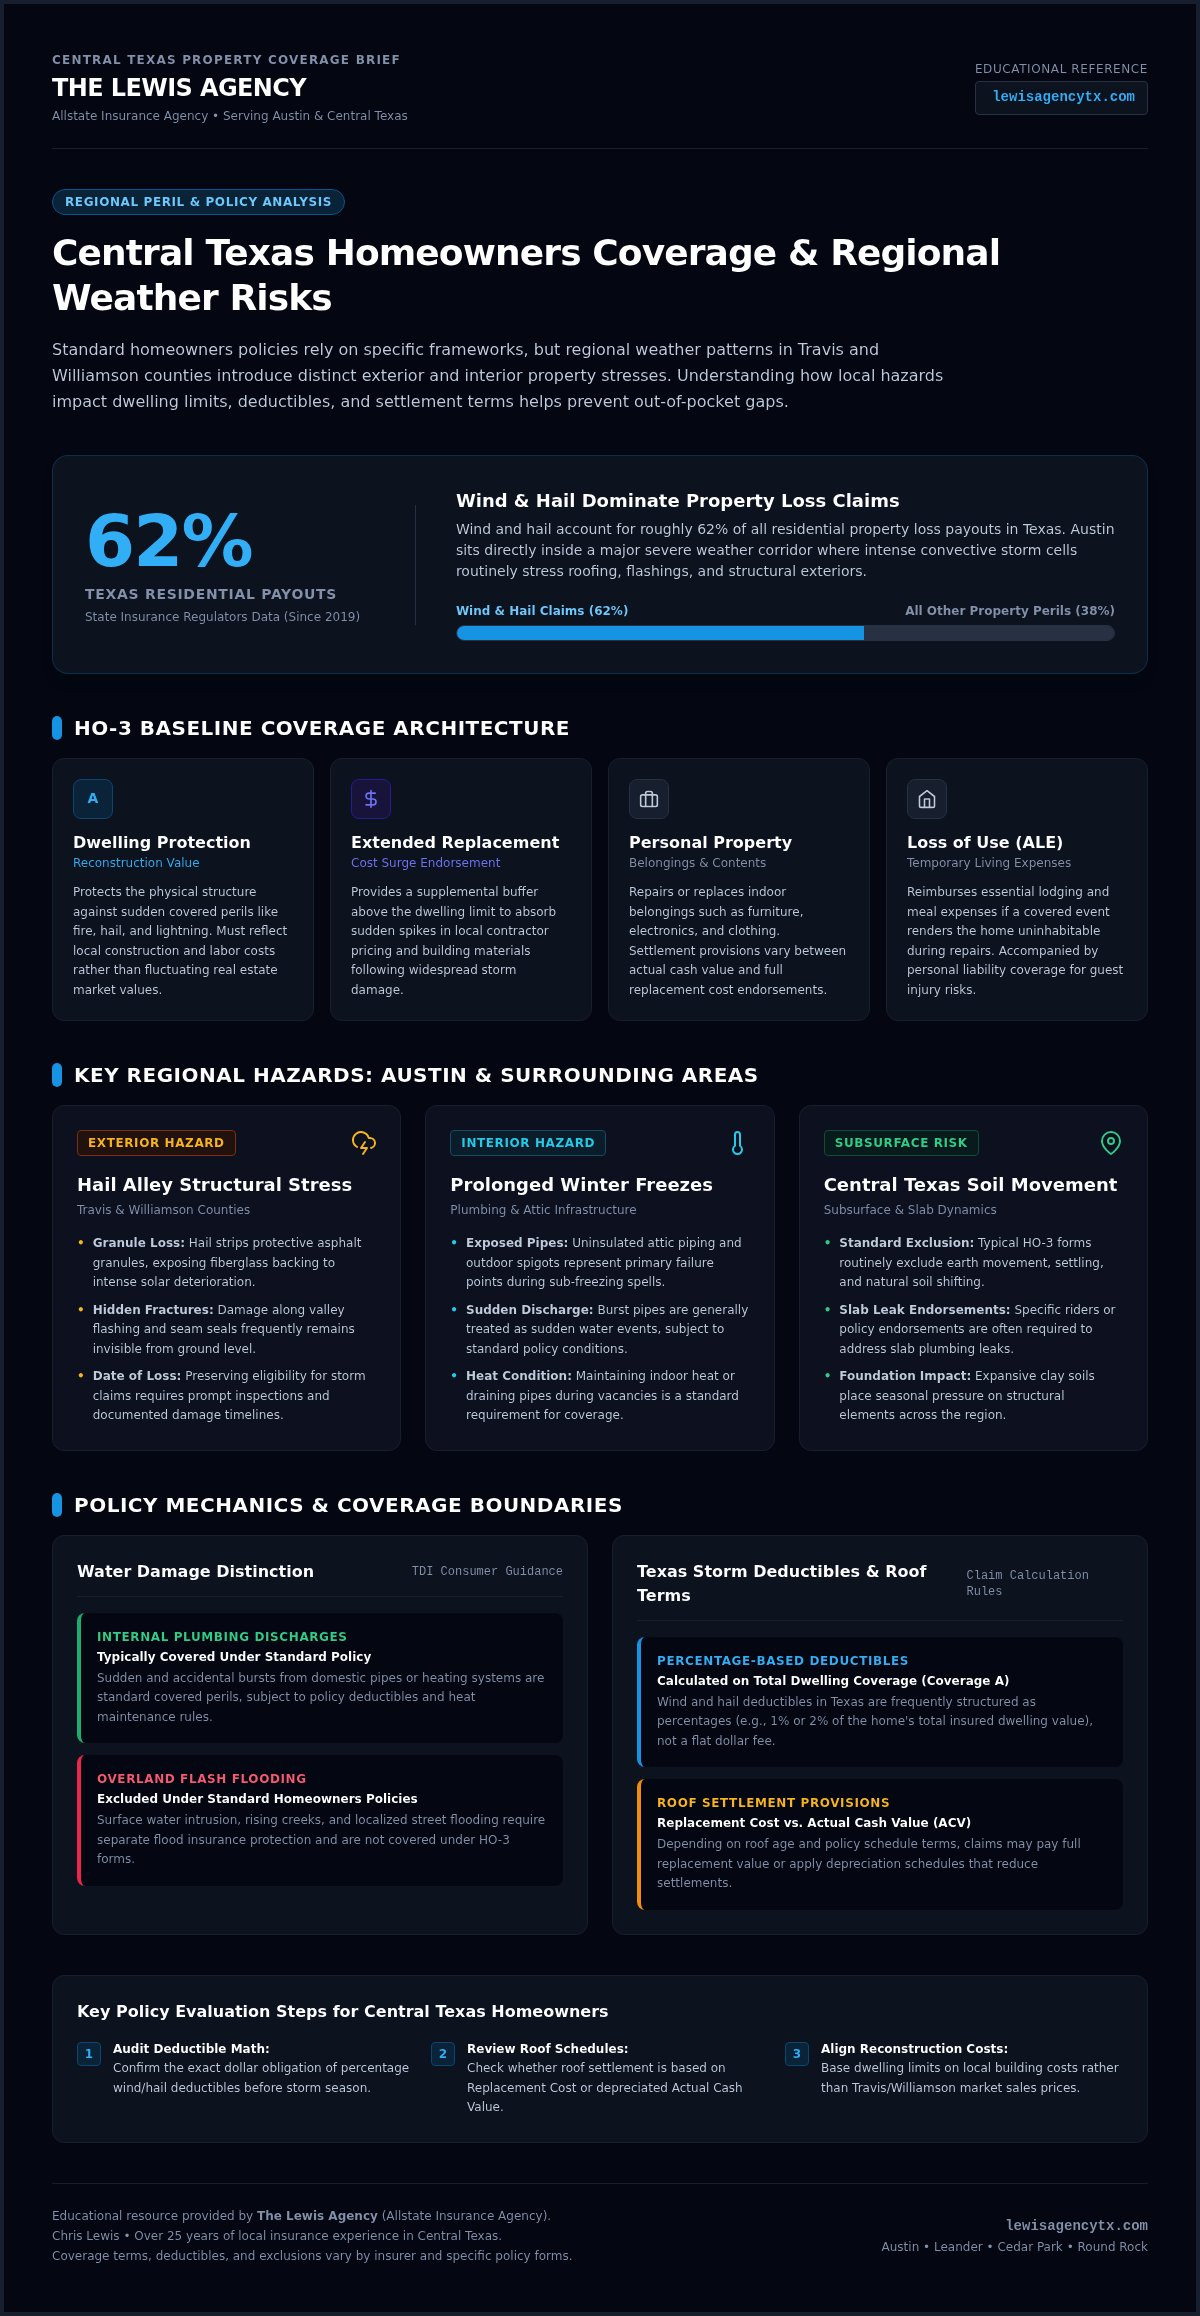
Austin sits directly inside a major severe storm corridor where spring cold fronts regularly trigger heavy convective cells. According to data tracked by state insurance regulators, wind and hail events account for roughly 62% of all residential property loss payouts in Texas since 2019. Securing reliable homeowners insurance austin coverage means preparing your household for rapid weather shifts that can batter your exterior or disrupt indoor plumbing within hours.
Hail Alley Activity and Structural Roof Stress
Hail represents the primary exterior threat across Travis and Williamson counties. Large hail bruises asphalt shingles, strips away protective granules, and leaves the fiberglass mat exposed to the intense Texas sun. Metal roofing panels can suffer denting that compromises seam integrity or seam seals over time.
Many roof fractures remain invisible from your driveway. Impact marks often hide beneath tile overlaps or along vulnerable valley flashing. Because storm claims depend on establishing an accurate date of loss, tracking local hail occurrences and arranging regular inspections helps preserve timely filing eligibility. If you want a clear picture of how regional storm risks affect your current policy structure, a quick consultation with The Lewis Agency can help you identify potential coverage gaps before storm season begins.
Winter Freeze Damage and Critical Flood Exclusions
While hail impacts the exterior, Central Texas winter freezes threaten the inside of your home. Hard freezes routinely cause exterior spigots and uninsulated attic pipes to burst once temperatures drop below freezing for extended stretches. Standard policies generally treat burst pipes as sudden and accidental water discharges, provided the homeowner maintained heat in the home or properly drained the plumbing lines before an absence.
The Texas Department of Insurance Home Insurance Guide emphasizes a vital distinction between interior pipe bursts and surface water intrusion. Key coverage boundaries include:
- Sudden internal plumbing breaks: Typically covered under standard property policies, subject to regular policy deductibles and heat maintenance conditions.
- Overland flash flooding: Excluded entirely under standard homeowners policies, whether water flows from a swollen creek or pools in your yard.
- Sewer and drain backups: Excluded by baseline forms unless you add a specific water backup endorsement.
Austin features significant micro-risks near waterways like Shoal Creek, Onion Creek, and the Colorado River. Because standard homeowners policies never cover rising outdoor water, securing separate flood insurance remains necessary for homes near low-lying terrain.
Deciphering Texas Deductibles: Hail Percentages and Roof Terms
Many homeowners assume a storm deductible works like a standard flat-dollar charge. In Central Texas, property policies handle severe weather very differently. According to Insurance Information Institute hail loss data, Texas consistently leads the country in severe hail events. Because storm frequency is elevated here, carriers separate wind and hail deductibles from other property perils, making deductible structure a vital consideration for your homeowners insurance austin coverage.
How Wind and Hail Percentage Deductibles Function
Rather than a fixed dollar fee, wind and hail deductibles are typically structured as a percentage, commonly 1% or 2%. This percentage applies directly to your total dwelling coverage limit, not the specific repair estimate. For example, a 2% deductible on a home with a $400,000 dwelling limit requires an $8,000 out-of-pocket responsibility before policy benefits disburse. Under Texas law, contractors cannot legally waive, absorb, or rebate your deductible, making it essential to keep an accessible emergency fund matched to your chosen tier.
Replacement Cost Value vs. Actual Cash Value Roof Terms
How an insurer calculates roof damage determines how much you pay out of pocket after a severe storm. Replacement Cost Value (RCV) pays to replace damaged roofing materials with new equivalents at current market labor rates, minus your deductible. In contrast, Actual Cash Value (ACV) subtracts depreciation based on the age and condition of your roof before issuing payment.
Many carriers add endorsements that shift roofs older than 10 to 15 years onto ACV depreciation schedules. Homeowners with metal roofing should also review whether their policy includes a cosmetic damage waiver, which restricts claims if hail dents metal panels without causing structural water penetration.
Water Backup and Foundation Endorsement Options
Central Texas expansive clay soils expand during wet seasons and shrink during summer droughts. This movement puts continuous pressure on concrete slabs and sub-surface pipes. Because standard policies exclude foundation settling and backed-up sewer lines, you should consider optional endorsements:
- Water backup endorsements: Cover interior damage caused by backed-up drains or failed sump pumps.
- Foundation and slab leak riders: Help pay the tear-out and repair expenses required to fix sub-surface plumbing pipes under the foundation.
Aligning these optional protections with your core homeowners insurance austin policy ensures you are prepared for both regional weather hazards and local soil conditions.
Evaluating Your Coverage Needs: A Practical Austin Buying Framework
Setting up proper coverage requires moving past automated online calculators. National quote engines often base recommendations on broad national metrics, leaving homeowners vulnerable when severe regional weather strikes. Building a dependable homeowners insurance austin policy begins with an honest evaluation of your specific structure, local construction realities, and personal property requirements.
Calculating Reconstruction Costs Versus Real Estate Market Value
Real estate market value is not the same as reconstruction cost. In Austin, a significant portion of your home's sales price reflects the underlying land and neighborhood demand. You don't insure dirt. Dwelling coverage must strictly reflect the actual expense of clearing debris, purchasing materials, and hiring licensed local trades to rebuild from the slab up.
Local construction expenses can surge quickly, especially after widespread storms strain trade availability. Rebuilding also triggers modern municipal building codes. If your home was built decades ago, full reconstruction may require updated wiring, enhanced insulation, or new plumbing standards. Setting your coverage limit solely to match a purchase price or mortgage balance can leave you underinsured during a total loss.
Reviewing Policy Endorsements and Risk-Mitigation Discounts
Auditing the physical details of your home helps uncover hidden coverage gaps before you sign a contract. Older homes in central neighborhoods often feature legacy plumbing materials that warrant closer attention, while newer builds in growing suburbs demand clear terms around roof wear and hail exposure. Tailoring endorsements to these realities keeps your coverage grounded in how you actually live.
You can also offset your overall insurance costs through practical risk-reduction steps. Insurers routinely offer premium credits for proactive safeguards, including:
- Bundling your homeowners insurance policy with auto insurance under one carrier.
- Installing monitored burglar and fire alarm systems.
- Adding automatic water shutoff valves to prevent catastrophic plumbing leaks.
- Installing qualified impact-resistant roofing shingles.
Partnering with a knowledgeable local advisor helps you identify these opportunities while structuring your coverage limits properly. Rather than leaving your structural protection to an impersonal national website, reach out to The Lewis Agency to schedule a policy review and secure peace of mind for your Central Texas household.
Navigating Homeowners Insurance with The Lewis Agency in Central Texas
When severe weather strikes, having a direct line to someone who knows your neighborhood makes a tremendous difference. Automated chat portals and out-of-state call centers treat your home as a collection of generic data points. Securing the right homeowners insurance austin coverage works best when you collaborate with a professional who lives and works right here in Central Texas.
The Value of a Dedicated Local Allstate Agency
The Lewis Agency is a dedicated Allstate agency led by Chris Lewis. Instead of leaving you to navigate complex policy forms alone, Chris serves as an approachable neighborhood advisor focused on protecting what you've built. Working with a dedicated agency allows you to structure proven Allstate insurance products around your property's specific physical needs.
Distant phone representatives rarely understand how local hail corridors, regional roof repair challenges, and soil shifts influence your coverage requirements. Having an accessible advisor means you can discuss your questions directly across a desk. When property damage happens, you have a steady, dependable resource in your corner to guide you through the initial steps of the claims process with clarity and patience.
Proactive Policy Reviews for Austin and Surrounding Communities
Property values, local rebuilding costs, and household situations evolve constantly across Central Texas. Whether your home is located in Austin, Cedar Park, Leander, Round Rock, Pflugerville, Buda, or Kyle, an unexamined policy can slowly fall behind reality over time. Regular policy audits help identify coverage shortfalls before severe convective storm seasons arrive.
A comprehensive review examines your current dwelling limits against local construction trends, confirms your storm deductibles align with your household budget, and checks that your personal property safeguards remain sufficient. It also provides an opportunity to evaluate related protections, such as auto insurance or landlords insurance, ensuring seamless coverage across all your assets.
Protecting your household begins with a straightforward, informative conversation. Connect with The Lewis Agency to schedule your personalized homeowners coverage review and ensure your Central Texas home has the reliable protection it deserves.
Protecting Your Central Texas Home with Confidence
Securing dependable homeowners insurance austin coverage comes down to understanding your specific property risks. When you base your dwelling limits on regional reconstruction costs rather than real estate market swings, you avoid serious shortfalls after a loss. Knowing how your wind and hail percentage deductibles function also ensures you aren't caught off guard when spring hailstorms roll across Travis or Williamson County.
You don't have to decipher policy provisions or roof settlement schedules alone. As a dedicated local Allstate agency, Chris Lewis and the team bring deep familiarity with Central Texas weather patterns and structural challenges. Whether your home is located in Austin, Cedar Park, or Round Rock, we are here to provide steady, plainspoken guidance. Connect with The Lewis Agency for a personalized Austin homeowners policy review, and ensure your home has the dependable protection your family deserves.
Frequently Asked Questions
How much dwelling coverage do I need for my home in Austin?
Your dwelling coverage limit should reflect the full estimated cost to rebuild your home's physical structure from the slab up, separate from your land value or market selling price. Local construction expenses, architectural materials, square footage, and regional trade labor rates determine this figure. Establishing an accurate limit ensures your policy absorbs local rebuilding costs and municipal building code requirements rather than fluctuating real estate values.
How does a percentage hail deductible work on a Texas home insurance policy?
A percentage hail deductible calculates your out-of-pocket cost as a fixed percentage of your home's total Coverage A dwelling limit, not the total repair estimate. For example, a two percent deductible on a four hundred thousand dollar dwelling limit requires an eight thousand dollar out-of-pocket responsibility. Under Texas law, contractors cannot legally waive, rebate, or absorb this deductible on your behalf.
Does standard Austin homeowners insurance cover flood and water backup damage?
Standard homeowners policies exclude damage caused by rising surface water, flash flooding, and backed-up municipal drains or sewers. Sudden and accidental internal plumbing line bursts, such as those caused by hard winter freezes, are typically covered under baseline terms. Protecting your home from rising creek water or sewer lines requires separate protection through a dedicated flood policy and an optional water backup endorsement.
How does the age and condition of my roof affect coverage terms?
As your roof ages, carriers often adjust coverage terms to account for wear and tear. Roofs older than ten to fifteen years may trigger mandatory roof inspections, underwriting restrictions, or policy endorsements that transition storm settlements from full replacement cost to an actual cash value schedule. Maintaining documentation and addressing minor wear promptly helps preserve broader settlement terms on your homeowners insurance austin policy.
What is the difference between replacement cost and actual cash value on roofs?
Replacement cost coverage pays the necessary amount to repair or replace damaged roofing materials with new equivalents at current market labor rates, minus your deductible. Actual cash value, however, deducts physical depreciation based on the roof's age and preexisting condition before issuing payment. This depreciation deduction can leave property owners facing substantial out-of-pocket expenses during storm claim repairs if their roof is settled on cash value terms.
Can bundling my auto and home insurance policies help lower overall costs?
Bundling your homeowners insurance policy with auto insurance under a single carrier is one of the most practical ways to lower your overall insurance expenses. Carriers frequently provide multi-policy premium credits for households that combine personal coverages. Beyond financial savings, keeping policies with a dedicated agency like The Lewis Agency simplifies account management, streamlines billing, and ensures you have a single point of local contact.
Why do homeowners insurance premiums fluctuate across Central Texas?
Regional premium adjustments reflect changing claim volumes from severe convective storms, rising labor and construction materials expenses, and localized environmental risks. In high-growth communities like Austin, Round Rock, and Cedar Park, frequent hailstorms and regional contractor demand heavily influence market-wide claims payouts. Evaluating your homeowners insurance austin policy annually ensures your coverage limits remain aligned with actual regional reconstruction expenses without unexpected gaps.