Actual Cash Value vs. Replacement Cost for a Texas Roof
Compare actual cash value vs replacement cost roof Texas coverage to understand how depreciation affects roof storm claims in Austin and Central Texas.
Could two homeowners with similar hail damage receive very different roof claim payments? Policy wording, depreciation, and claim conditions may help explain the difference. If you’re searching “actual cash value vs replacement cost roof texas,” you’re likely trying to understand what those terms could mean for your roof in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, or Liberty Hill.
It’s easy to mix up the valuation method, the deductible, and a repair estimate, especially after a storm. Actual cash value generally accounts for depreciation, while replacement-cost coverage may handle depreciation differently. The exact terms and claim process depend on the policy.
This guide explains the basic difference, shows what policy language and conditions to check, and offers questions to ask before a storm. The Lewis Agency helps homeowners choose coverage limits and endorsements based on their dwelling and financial needs. The goal here is to help you read your policy with greater confidence, not predict a claim outcome.
Key Takeaways
- For “actual cash value vs replacement cost roof texas,” the key difference is how the policy treats depreciation when valuing roof damage.
- Check your declarations page and policy documents for roof valuation terms and endorsements that may affect coverage.
- Review the deductible separately from depreciation. They are distinct parts of a claim calculation.
- Look for payment conditions and claim requirements, and note what you want clarified before a storm.
- The Lewis Agency can help you understand homeowners coverage options, limits, and endorsements. The insurer makes claim decisions based on the policy and circumstances.
What ACV and Replacement Cost Mean for a Texas Roof
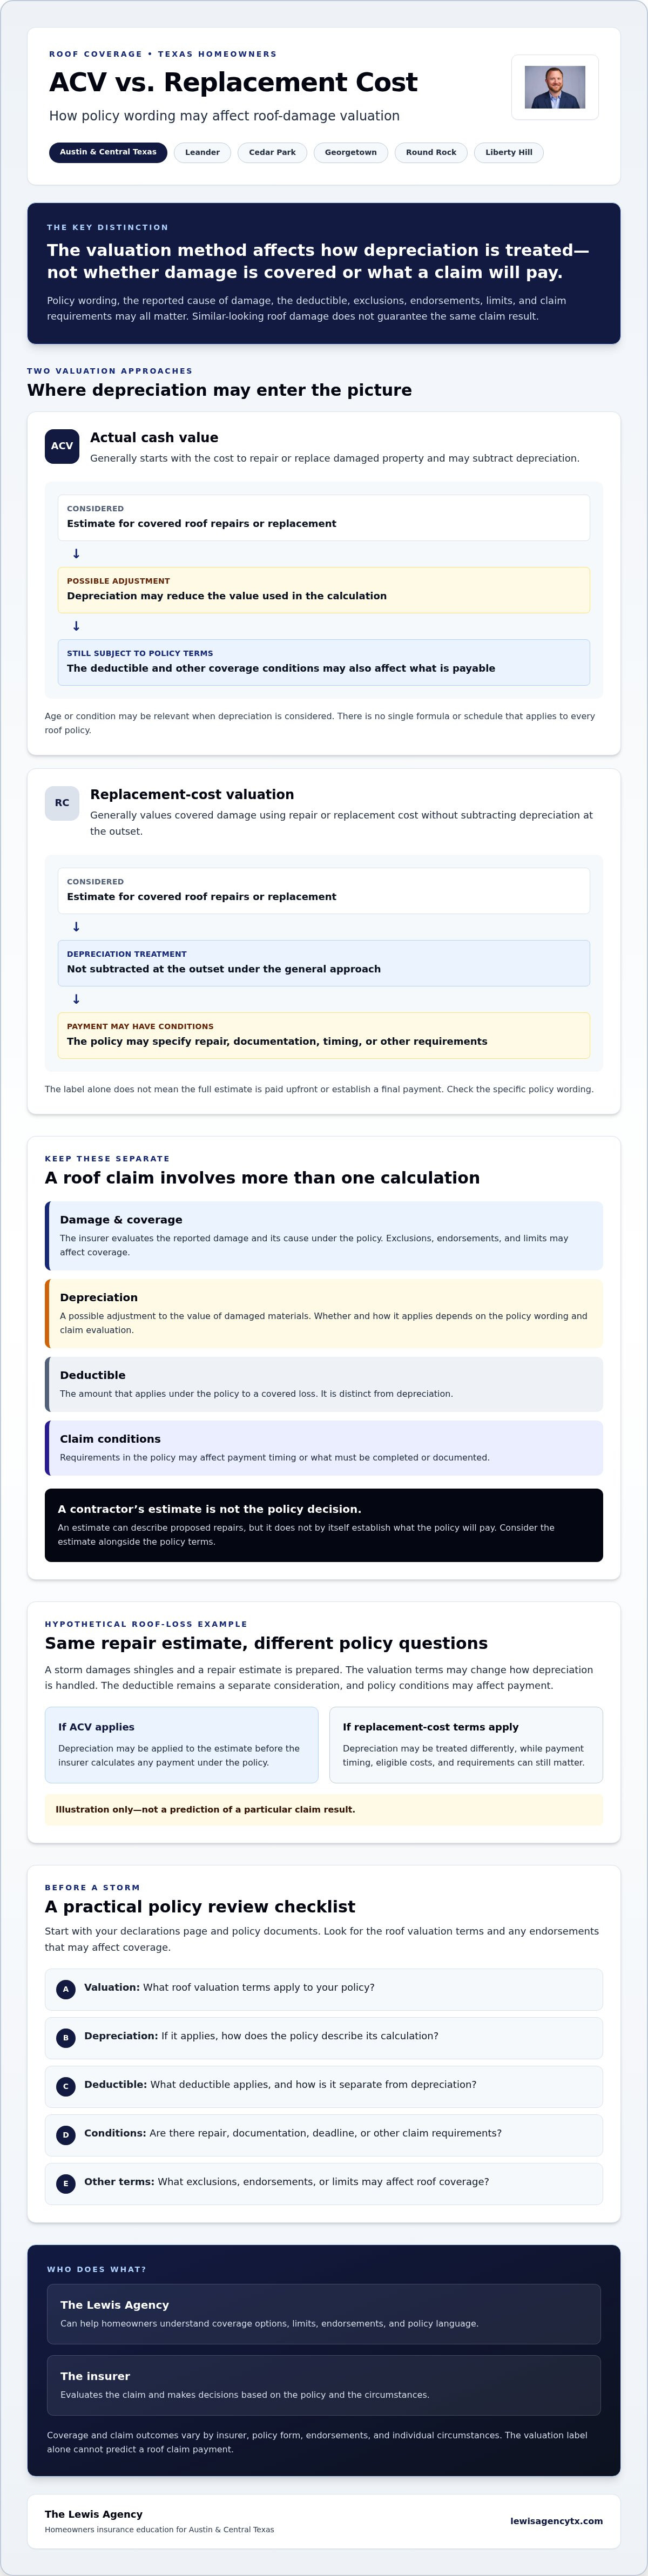
Actual cash value (ACV) and replacement cost are methods a policy may use to value covered roof damage. They describe how the insurer calculates a loss, not whether the damage is covered or exactly what a claim will pay. The question behind “actual cash value vs replacement cost roof texas” is how depreciation and other policy terms may affect the value assigned to roof damage.
In general, ACV starts with the cost to repair or replace damaged property and may subtract depreciation. Replacement-cost valuation generally does not subtract depreciation at the outset. For a neutral overview of the basic ACV concept, see Actual Cash Value (ACV). Your policy’s wording, endorsements, exclusions, deductible, and claim requirements still matter. Neither label alone guarantees that a roof will be replaced or establishes the final payment.
What does actual cash value mean for roof damage?
Depreciation is an adjustment that may reflect a roof’s age, condition, or wear, depending on the policy terms. It can reduce the value used to calculate a claim, but that estimated value is not necessarily the amount ultimately payable. Other terms, including the deductible and coverage conditions, may also affect the calculation.
Hypothetical example: A storm damages shingles, and an estimate is prepared for the covered repair. If the policy uses ACV, depreciation may be applied to that estimate before the insurer calculates any payment under the policy. The estimate, depreciation adjustment, and deductible are separate considerations. This example does not predict a particular claim result.
What does replacement cost mean for a roof?
Replacement cost generally values covered damage based on the cost to repair or replace it without subtracting depreciation at the outset. That does not necessarily mean the insurer pays the full estimate upfront or in every situation. The policy may set conditions for when or how replacement-cost benefits are paid, such as requirements to complete repairs or provide documentation. Check the specific wording rather than relying on the label alone.
For example, if a covered roof loss has a repair estimate, replacement-cost terms may treat depreciation differently from ACV terms. Payment timing, eligible costs, limits, and other requirements can still affect what is payable. Coverage and claim outcomes vary by insurer, policy form, endorsements, and individual circumstances.
How Depreciation and Policy Conditions Can Affect Roof Settlement
A roof claim involves more than choosing between ACV and replacement cost. The insurer evaluates the reported damage and its cause, applies the policy terms, and considers an estimate alongside those terms. Exclusions, endorsements, limits, and claim requirements may also affect the settlement. A contractor’s estimate can describe proposed repairs, but it does not by itself establish what the policy will pay.
The valuation method alone cannot predict a roof claim payment. Coverage, depreciation, the deductible, and policy conditions all matter.
Keep the deductible separate from depreciation. Depreciation is a possible adjustment to the value of damaged materials. A deductible is the amount that applies under the policy to a covered loss. They are different parts of a claim calculation, and the policy wording determines how they apply.
How is roof depreciation considered?
Age and condition may be relevant when depreciation is considered, but there is no single formula or schedule that applies to every roof policy. The policy wording and claim evaluation govern whether depreciation applies and how it is calculated. Do not assume that a particular roof age automatically produces a fixed reduction. Review the terms that apply to your policy and ask for clarification if the calculation is unclear.
Other coverage questions can matter just as much. The policy’s treatment of the reported cause of damage, any exclusions or endorsements, and applicable limits may affect a claim. A hail-damaged roof and a roof with deterioration may raise different coverage questions, depending on the policy and circumstances. Consider an estimate alongside the policy, not in isolation.
Why replacement-cost coverage may involve more than one payment
Some policies may initially withhold depreciation and make it available only after specified claim steps are completed. Conditions vary, so check your policy for deadlines, required documents, repair requirements, or other steps. Do not assume a particular reimbursement process or timeline applies to your roof.
Before authorizing repairs, understand what the insurer has evaluated, which estimate is being used, and whether any payment conditions remain. If the explanation is unclear, ask the insurer or your insurance professional to point out the relevant policy language. Homeowners can also review their homeowners coverage with The Lewis Agency and discuss policy options, limits, and endorsements. Claim decisions and payments are determined by the insurer.
ACV vs. Replacement Cost: What Texas Homeowners Should Compare
When comparing actual cash value vs replacement cost roof texas coverage, look beyond the label. Check how depreciation is handled, whether payment depends on completing repairs, and what the policy requires from you. Replacement-cost coverage does not automatically mean full reimbursement. The deductible, covered damage, limits, exclusions, and claim conditions may affect the final amount.
| What to compare | ACV | Replacement cost | What to verify |
|---|---|---|---|
| Depreciation | May be deducted based on policy terms and claim evaluation. | Generally is not deducted at the outset, but terms vary. | How does the policy define roof valuation and depreciation? |
| Payment conditions | Payment remains subject to coverage terms and the deductible. | Some policies may require certain steps before additional payment is available. | Are repairs, documents, or other claim steps required? |
| Potential out-of-pocket expense | Depreciation may affect the amount available for covered repairs. | Payment may still be affected by the deductible, limits, and policy conditions. | What expenses could remain your responsibility? |
Hypothetical comparison: Imagine the same covered roof damage and repair estimate under two different policy terms. Under ACV terms, depreciation may reduce the amount used to calculate payment. Under replacement-cost terms, depreciation may not be subtracted initially, though the policy could set conditions for receiving an additional amount. The estimate alone does not determine either outcome, and this example does not predict a claim result.
Which roof valuation method may fit your situation?
Consider your budget flexibility, the roof’s condition, and how you would handle a gap between repair costs and available claim funds. Compare the premium and roof coverage shown in your own policy documents. A lower premium by itself does not show whether coverage fits your needs, and neither valuation method is automatically right for every homeowner.
Does roof age decide whether coverage is ACV or replacement cost?
Roof age may affect underwriting or claim valuation, depending on the insurer and policy. But age alone does not establish which method applies or guarantee a change in coverage. Check the current declarations page and any endorsements for roof-specific terms, then ask what wording applies to your home. Do not rely on a general age cutoff instead of reviewing your policy.
How to Review Your Texas Roof Coverage Before a Storm
A policy review is easier before hail or wind damage creates time pressure. Use this sequence to find the roof terms that could shape a claim, then note anything you want clarified. Whether you own a home in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, or Liberty Hill, confirm what your own policy says instead of relying on a general description of coverage.
- Start with the declarations page. Review the listed property coverage and deductible information. Note whether a separate deductible may apply to wind or hail, then check the policy wording to understand when it applies.
- Confirm the policy form. Find the form identified in your documents and remember that forms and coverage vary by insurer. Do not assume a familiar policy label tells the whole story about roof settlement.
- Look for roof valuation language and endorsements. Search the policy and attached endorsements for terms such as “actual cash value,” “replacement cost,” “roof,” or “depreciation.” Check whether an endorsement changes terms shown elsewhere.
- Review exclusions and claim conditions. Note language that may affect the reported cause of loss, required documentation, repair steps, or deadlines. Ask for clarification if you are unsure what a condition means.
- Keep a record of roof condition. Save relevant inspection, repair, and maintenance records, along with dated photos if available. These records can help describe the roof’s condition, but they do not guarantee coverage or a particular claim payment.
Which policy documents and terms should you check?
Read the declarations page together with the full policy and endorsements. The declarations page can point you to listed coverage and deductible details, while the policy wording explains terms, exclusions, and conditions. The Texas Department of Insurance offers consumer information about homeowners coverage. Check its current guidance and compare it with your policy language.
What should you ask after hail or storm damage?
Record what you observe and preserve relevant maintenance or repair documents. Before authorizing work, ask the insurer how the policy describes roof valuation and which claim steps apply. Do not assume damage is covered based on appearance alone. Coverage depends on the policy and circumstances, and the insurer makes claim determinations.
If you want help discussing your homeowners coverage options, limits, or endorsements, ask The Lewis Agency about your roof coverage. Bring your policy documents and questions so the discussion can focus on the wording that applies to your home.
How The Lewis Agency Can Help You Understand Roof Coverage
Roof valuation language can be difficult to interpret on your own. The Lewis Agency works directly with clients to identify risks and match them with appropriate policies. For homeowners in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, and Liberty Hill, a conversation about homeowners coverage can help clarify which policy limits or endorsements may suit the dwelling and the homeowner’s needs.
Reviewing your coverage before a storm can help you identify questions while there is time to look up the relevant terms. This discussion does not determine whether damage is covered or how much a claim will pay. The insurer reviews the claim and makes coverage and payment decisions based on the policy and circumstances.
What an insurance agency can clarify about roof coverage
An agency can help you discuss homeowners policy options, limits, and endorsements. You might ask where your documents address roof valuation, which deductible information to review, or whether an endorsement changes the coverage terms. Having the declarations page, full policy, and endorsements available can make it easier to focus on the specific wording in your documents.
Those conversations are about understanding and choosing coverage. They do not replace the insurer’s evaluation of a particular loss or determine claim payments, underwriting, rates, or coverage decisions. If a question depends on how the insurer evaluates reported damage, the insurer is the source for a decision about that claim.
A practical next step for Austin and Central Texas homeowners
Before asking about actual cash value vs replacement cost roof texas, gather your declarations page, full policy, and any endorsements. Mark passages you have questions about and make a short list covering:
- How the policy describes roof valuation and depreciation
- Which deductible information applies to roof damage
- Any exclusions, endorsements, or conditions that may affect a claim
- What steps or documentation the policy requires during the claims process
Having these documents at hand makes it easier to discuss the language that applies to your home, rather than relying on general assumptions about Texas roof claims. Policy terms and coverage vary, so use your own documents as the starting point.
If you have a question about your homeowners policy, ask a question about your homeowners coverage. A conversation can help clarify your coverage options and which questions may need to be directed to the insurer.
Review Your Roof Coverage Before the Next Storm
Understanding actual cash value vs replacement cost roof texas coverage starts with knowing how your policy treats depreciation, which deductible applies, and whether payment depends on specific claim steps. The valuation label alone cannot tell you what a future claim will pay. Your policy wording, endorsements, and circumstances matter.
Review your declarations page and policy documents. Look for roof valuation language, exclusions, applicable deductibles, and claim conditions. If a term is unclear, write down your questions and ask for an explanation before you need to make decisions after a storm.
The Lewis Agency helps clients identify risks and choose appropriate coverage. Homeowners in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, and Liberty Hill can discuss homeowners policy limits and endorsements with the agency. The insurer makes coverage and claim decisions.
Bring your questions and policy documents together for a clearer conversation. Ask a question about your homeowners coverage and take the next step toward understanding what your policy says.
Frequently Asked Questions
What is the difference between ACV and replacement cost for a roof?
ACV generally values covered roof damage after accounting for depreciation, which may reflect age, condition, or wear under the policy. Replacement-cost valuation generally uses repair or replacement cost without subtracting depreciation at the outset. The phrase “actual cash value vs replacement cost roof texas” refers to this basic distinction, but neither label promises a particular payment. Your policy wording, covered cause of loss, deductible, and claim conditions determine how the terms apply.
Does replacement-cost coverage pay to replace the entire roof?
Not necessarily. Replacement-cost coverage does not guarantee approval of a full roof replacement or full reimbursement of an estimate. The insurer evaluates the reported damage under the policy, and covered damage, deductibles, limits, exclusions, and required claim steps may affect payment. Review your own policy for the applicable terms. If the wording is unclear, ask your insurer or agent to explain it without assuming a particular claim outcome.
How is depreciation calculated on a Texas roof claim?
There is no single depreciation formula or rate that applies to every Texas roof claim. How depreciation is considered depends on the policy wording and the insurer’s evaluation of the claim. Ask how the roof’s age and condition were assessed and where the relevant valuation terms appear in your policy or endorsements. That can help you understand the calculation being used, but it does not establish the final claim payment.
Can an insurer settle a roof claim using ACV in Texas?
The applicable policy and the circumstances of the loss determine how a roof claim may be valued. There is no one answer for every Texas homeowner. Review your policy’s valuation provisions and any roof-related endorsements to see which terms apply. For Texas consumer guidance, consult current information from the Texas Department of Insurance. You can also ask your insurer or agent to explain relevant wording without assuming a specific claim result.
Does roof age affect actual cash value or replacement-cost coverage?
Roof age may affect underwriting or claim settlement, depending on the insurer and policy, but it does not create one universal outcome. Age alone may not tell you which valuation method applies or how a future claim would be handled. Check your policy and any roof-specific endorsements for the terms that apply to your home. Ask your insurer or agent to clarify the wording rather than relying on a general age cutoff.
What should I check in my policy before filing a roof claim?
Look for roof valuation language, applicable deductibles, exclusions, endorsements, documentation requirements, and claim conditions. Your declarations page may identify some coverage and deductible details, but it may not contain every relevant term. Read it alongside the full policy and endorsements. If a provision is unclear, ask your insurer or agent to explain what it says and which claim steps may apply. That explanation can help you understand the process, but it cannot promise a claim result.
Can The Lewis Agency decide whether my roof claim will be paid?
No. The insurer makes coverage and payment decisions based on the policy and circumstances of the loss. The Lewis Agency can help clients identify risks and discuss homeowners policy options, limits, and endorsements, but it cannot control a claim determination or guarantee an outcome. Homeowners in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, and Liberty Hill can contact the agency with questions about their coverage.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.

Austin Homeowners Insurance: Complete 2026 Coverage Guide
Need reliable homeowners insurance Austin coverage? Explore 2026 policy insights on hail deductibles, roof schedules, and protecting your Central Texas home.
What if the deductible on your policy doesn't work the way you expected when a severe hailstorm hits your neighborhood? For many Central Texas residents, shopping for reliable homeowners insurance austin coverage through generic national websites often creates more questions than answers. Online algorithms routinely overlook regional realities, leaving homeowners to untangle separate percentage-based storm deductibles, unexpected roof depreciation schedules, and confusing rules around freeze damage on their own.
It can feel overwhelming to sort through policy fine print, but protecting your biggest investment shouldn't involve guesswork. You can protect your Central Texas home against hail, storms, and local property risks with tailored homeowners coverage designed for our specific climate. In this guide, we'll walk through how local reconstruction expenses shape your dwelling limits, how wind and water claims are handled under Texas guidelines, and the key coverage details you should review to keep your household secure.
Key Takeaways
- Understand what standard policies protect and identify the common Central Texas weather perils that require closer policy attention.
- Learn how regional storm patterns influence homeowners insurance austin coverage, particularly regarding roof settlement terms and depreciation schedules.
- Demystify percentage-based wind and hail deductibles so you clearly understand your out-of-pocket responsibilities before severe weather strikes.
- Establish an accurate dwelling coverage limit based on local reconstruction expenses rather than fluctuating real estate market values.
- Discover how tailored guidance from a dedicated local Allstate agent helps you safeguard your home without the guesswork of generic quote tools.
What Does Homeowners Insurance in Austin Actually Cover?
Most single-family homes across Central Texas rely on an HO-3 special form policy. Under the standard homeowners insurance policy structure, coverage splits into distinct categories for your physical structure, personal belongings, liability risks, and living disruptions. Choosing the right homeowners insurance austin policy requires understanding where baseline protections end and where local regional conditions demand closer attention. A baseline policy provides essential safeguards, but it works best when tailored to the specific risks of your property.
Dwelling Protection and Extended Replacement Cost
Coverage A dwelling protection covers the physical structure of your house after sudden, covered events like fire, hail, or lightning. Detached fences, sheds, and detached garages fall under separate other structures coverage. Your dwelling limit must reflect regional labor and rebuilding expenses rather than local real estate market valuations.
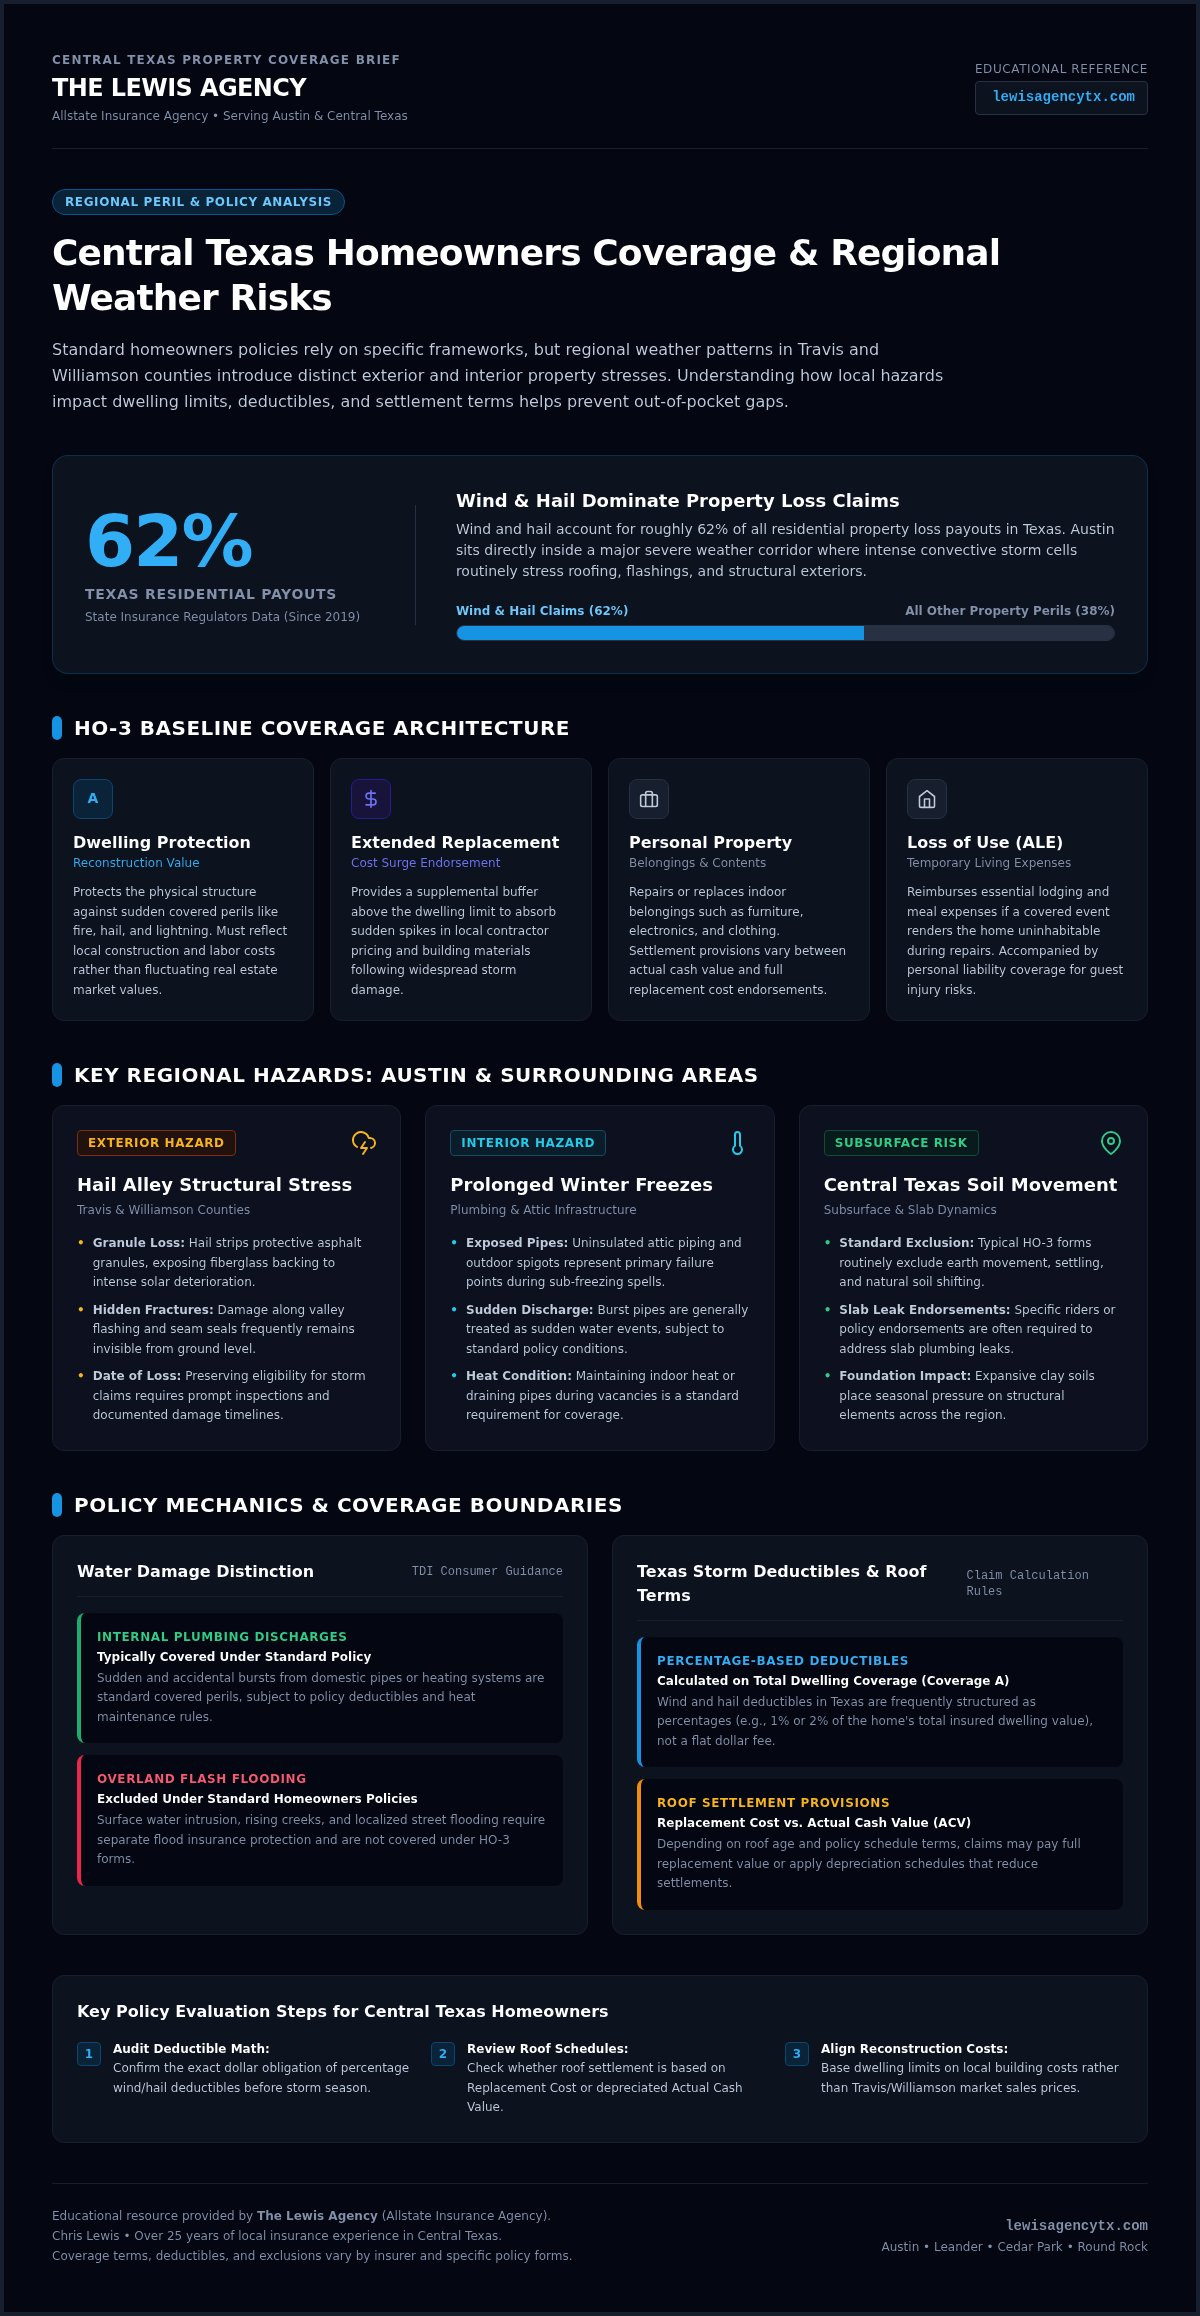
Central Texas soils present unique structural challenges. Standard policies routinely exclude earth movement and settling, meaning slab leaks and foundation shifts often require specific policy endorsements. Adding an extended replacement cost endorsement gives your dwelling limit an extra buffer, helping absorb sudden surges in local contractor pricing and materials following widespread severe weather.
Personal Property, Liability, and Additional Living Expenses
Inside your home, personal property coverage helps repair or replace belongings like furniture, clothing, and electronics damaged by covered perils. Policy terms determine whether these items are settled at actual cash value or full replacement cost, with specialty endorsements available for high-value items.
Personal liability coverage safeguards your family's financial assets if a visitor is injured on your property or if you accidentally cause damage to someone else's property. If a covered peril renders your home uninhabitable, loss of use coverage, also known as Additional Living Expenses, reimburses temporary lodging and meal expenses while repairs take place. Because policy forms and endorsements vary between carriers, reviewing these limits carefully ensures your family avoids unexpected out-of-pocket gaps.
Central Texas Weather Hazards: Hail, Freezes, and Severe Storms
Austin sits directly inside a major severe storm corridor where spring cold fronts regularly trigger heavy convective cells. According to data tracked by state insurance regulators, wind and hail events account for roughly 62% of all residential property loss payouts in Texas since 2019. Securing reliable homeowners insurance austin coverage means preparing your household for rapid weather shifts that can batter your exterior or disrupt indoor plumbing within hours.
Hail Alley Activity and Structural Roof Stress
Hail represents the primary exterior threat across Travis and Williamson counties. Large hail bruises asphalt shingles, strips away protective granules, and leaves the fiberglass mat exposed to the intense Texas sun. Metal roofing panels can suffer denting that compromises seam integrity or seam seals over time.
Many roof fractures remain invisible from your driveway. Impact marks often hide beneath tile overlaps or along vulnerable valley flashing. Because storm claims depend on establishing an accurate date of loss, tracking local hail occurrences and arranging regular inspections helps preserve timely filing eligibility. If you want a clear picture of how regional storm risks affect your current policy structure, a quick consultation with The Lewis Agency can help you identify potential coverage gaps before storm season begins.
Winter Freeze Damage and Critical Flood Exclusions
While hail impacts the exterior, Central Texas winter freezes threaten the inside of your home. Hard freezes routinely cause exterior spigots and uninsulated attic pipes to burst once temperatures drop below freezing for extended stretches. Standard policies generally treat burst pipes as sudden and accidental water discharges, provided the homeowner maintained heat in the home or properly drained the plumbing lines before an absence.
The Texas Department of Insurance Home Insurance Guide emphasizes a vital distinction between interior pipe bursts and surface water intrusion. Key coverage boundaries include:
- Sudden internal plumbing breaks: Typically covered under standard property policies, subject to regular policy deductibles and heat maintenance conditions.
- Overland flash flooding: Excluded entirely under standard homeowners policies, whether water flows from a swollen creek or pools in your yard.
- Sewer and drain backups: Excluded by baseline forms unless you add a specific water backup endorsement.
Austin features significant micro-risks near waterways like Shoal Creek, Onion Creek, and the Colorado River. Because standard homeowners policies never cover rising outdoor water, securing separate flood insurance remains necessary for homes near low-lying terrain.
Deciphering Texas Deductibles: Hail Percentages and Roof Terms
Many homeowners assume a storm deductible works like a standard flat-dollar charge. In Central Texas, property policies handle severe weather very differently. According to Insurance Information Institute hail loss data, Texas consistently leads the country in severe hail events. Because storm frequency is elevated here, carriers separate wind and hail deductibles from other property perils, making deductible structure a vital consideration for your homeowners insurance austin coverage.
How Wind and Hail Percentage Deductibles Function
Rather than a fixed dollar fee, wind and hail deductibles are typically structured as a percentage, commonly 1% or 2%. This percentage applies directly to your total dwelling coverage limit, not the specific repair estimate. For example, a 2% deductible on a home with a $400,000 dwelling limit requires an $8,000 out-of-pocket responsibility before policy benefits disburse. Under Texas law, contractors cannot legally waive, absorb, or rebate your deductible, making it essential to keep an accessible emergency fund matched to your chosen tier.
Replacement Cost Value vs. Actual Cash Value Roof Terms
How an insurer calculates roof damage determines how much you pay out of pocket after a severe storm. Replacement Cost Value (RCV) pays to replace damaged roofing materials with new equivalents at current market labor rates, minus your deductible. In contrast, Actual Cash Value (ACV) subtracts depreciation based on the age and condition of your roof before issuing payment.
Many carriers add endorsements that shift roofs older than 10 to 15 years onto ACV depreciation schedules. Homeowners with metal roofing should also review whether their policy includes a cosmetic damage waiver, which restricts claims if hail dents metal panels without causing structural water penetration.
Water Backup and Foundation Endorsement Options
Central Texas expansive clay soils expand during wet seasons and shrink during summer droughts. This movement puts continuous pressure on concrete slabs and sub-surface pipes. Because standard policies exclude foundation settling and backed-up sewer lines, you should consider optional endorsements:
- Water backup endorsements: Cover interior damage caused by backed-up drains or failed sump pumps.
- Foundation and slab leak riders: Help pay the tear-out and repair expenses required to fix sub-surface plumbing pipes under the foundation.
Aligning these optional protections with your core homeowners insurance austin policy ensures you are prepared for both regional weather hazards and local soil conditions.
Evaluating Your Coverage Needs: A Practical Austin Buying Framework
Setting up proper coverage requires moving past automated online calculators. National quote engines often base recommendations on broad national metrics, leaving homeowners vulnerable when severe regional weather strikes. Building a dependable homeowners insurance austin policy begins with an honest evaluation of your specific structure, local construction realities, and personal property requirements.
Calculating Reconstruction Costs Versus Real Estate Market Value
Real estate market value is not the same as reconstruction cost. In Austin, a significant portion of your home's sales price reflects the underlying land and neighborhood demand. You don't insure dirt. Dwelling coverage must strictly reflect the actual expense of clearing debris, purchasing materials, and hiring licensed local trades to rebuild from the slab up.
Local construction expenses can surge quickly, especially after widespread storms strain trade availability. Rebuilding also triggers modern municipal building codes. If your home was built decades ago, full reconstruction may require updated wiring, enhanced insulation, or new plumbing standards. Setting your coverage limit solely to match a purchase price or mortgage balance can leave you underinsured during a total loss.
Reviewing Policy Endorsements and Risk-Mitigation Discounts
Auditing the physical details of your home helps uncover hidden coverage gaps before you sign a contract. Older homes in central neighborhoods often feature legacy plumbing materials that warrant closer attention, while newer builds in growing suburbs demand clear terms around roof wear and hail exposure. Tailoring endorsements to these realities keeps your coverage grounded in how you actually live.
You can also offset your overall insurance costs through practical risk-reduction steps. Insurers routinely offer premium credits for proactive safeguards, including:
- Bundling your homeowners insurance policy with auto insurance under one carrier.
- Installing monitored burglar and fire alarm systems.
- Adding automatic water shutoff valves to prevent catastrophic plumbing leaks.
- Installing qualified impact-resistant roofing shingles.
Partnering with a knowledgeable local advisor helps you identify these opportunities while structuring your coverage limits properly. Rather than leaving your structural protection to an impersonal national website, reach out to The Lewis Agency to schedule a policy review and secure peace of mind for your Central Texas household.
Navigating Homeowners Insurance with The Lewis Agency in Central Texas
When severe weather strikes, having a direct line to someone who knows your neighborhood makes a tremendous difference. Automated chat portals and out-of-state call centers treat your home as a collection of generic data points. Securing the right homeowners insurance austin coverage works best when you collaborate with a professional who lives and works right here in Central Texas.
The Value of a Dedicated Local Allstate Agency
The Lewis Agency is a dedicated Allstate agency led by Chris Lewis. Instead of leaving you to navigate complex policy forms alone, Chris serves as an approachable neighborhood advisor focused on protecting what you've built. Working with a dedicated agency allows you to structure proven Allstate insurance products around your property's specific physical needs.
Distant phone representatives rarely understand how local hail corridors, regional roof repair challenges, and soil shifts influence your coverage requirements. Having an accessible advisor means you can discuss your questions directly across a desk. When property damage happens, you have a steady, dependable resource in your corner to guide you through the initial steps of the claims process with clarity and patience.
Proactive Policy Reviews for Austin and Surrounding Communities
Property values, local rebuilding costs, and household situations evolve constantly across Central Texas. Whether your home is located in Austin, Cedar Park, Leander, Round Rock, Pflugerville, Buda, or Kyle, an unexamined policy can slowly fall behind reality over time. Regular policy audits help identify coverage shortfalls before severe convective storm seasons arrive.
A comprehensive review examines your current dwelling limits against local construction trends, confirms your storm deductibles align with your household budget, and checks that your personal property safeguards remain sufficient. It also provides an opportunity to evaluate related protections, such as auto insurance or landlords insurance, ensuring seamless coverage across all your assets.
Protecting your household begins with a straightforward, informative conversation. Connect with The Lewis Agency to schedule your personalized homeowners coverage review and ensure your Central Texas home has the reliable protection it deserves.
Protecting Your Central Texas Home with Confidence
Securing dependable homeowners insurance austin coverage comes down to understanding your specific property risks. When you base your dwelling limits on regional reconstruction costs rather than real estate market swings, you avoid serious shortfalls after a loss. Knowing how your wind and hail percentage deductibles function also ensures you aren't caught off guard when spring hailstorms roll across Travis or Williamson County.
You don't have to decipher policy provisions or roof settlement schedules alone. As a dedicated local Allstate agency, Chris Lewis and the team bring deep familiarity with Central Texas weather patterns and structural challenges. Whether your home is located in Austin, Cedar Park, or Round Rock, we are here to provide steady, plainspoken guidance. Connect with The Lewis Agency for a personalized Austin homeowners policy review, and ensure your home has the dependable protection your family deserves.
Frequently Asked Questions
How much dwelling coverage do I need for my home in Austin?
Your dwelling coverage limit should reflect the full estimated cost to rebuild your home's physical structure from the slab up, separate from your land value or market selling price. Local construction expenses, architectural materials, square footage, and regional trade labor rates determine this figure. Establishing an accurate limit ensures your policy absorbs local rebuilding costs and municipal building code requirements rather than fluctuating real estate values.
How does a percentage hail deductible work on a Texas home insurance policy?
A percentage hail deductible calculates your out-of-pocket cost as a fixed percentage of your home's total Coverage A dwelling limit, not the total repair estimate. For example, a two percent deductible on a four hundred thousand dollar dwelling limit requires an eight thousand dollar out-of-pocket responsibility. Under Texas law, contractors cannot legally waive, rebate, or absorb this deductible on your behalf.
Does standard Austin homeowners insurance cover flood and water backup damage?
Standard homeowners policies exclude damage caused by rising surface water, flash flooding, and backed-up municipal drains or sewers. Sudden and accidental internal plumbing line bursts, such as those caused by hard winter freezes, are typically covered under baseline terms. Protecting your home from rising creek water or sewer lines requires separate protection through a dedicated flood policy and an optional water backup endorsement.
How does the age and condition of my roof affect coverage terms?
As your roof ages, carriers often adjust coverage terms to account for wear and tear. Roofs older than ten to fifteen years may trigger mandatory roof inspections, underwriting restrictions, or policy endorsements that transition storm settlements from full replacement cost to an actual cash value schedule. Maintaining documentation and addressing minor wear promptly helps preserve broader settlement terms on your homeowners insurance austin policy.
What is the difference between replacement cost and actual cash value on roofs?
Replacement cost coverage pays the necessary amount to repair or replace damaged roofing materials with new equivalents at current market labor rates, minus your deductible. Actual cash value, however, deducts physical depreciation based on the roof's age and preexisting condition before issuing payment. This depreciation deduction can leave property owners facing substantial out-of-pocket expenses during storm claim repairs if their roof is settled on cash value terms.
Can bundling my auto and home insurance policies help lower overall costs?
Bundling your homeowners insurance policy with auto insurance under a single carrier is one of the most practical ways to lower your overall insurance expenses. Carriers frequently provide multi-policy premium credits for households that combine personal coverages. Beyond financial savings, keeping policies with a dedicated agency like The Lewis Agency simplifies account management, streamlines billing, and ensures you have a single point of local contact.
Why do homeowners insurance premiums fluctuate across Central Texas?
Regional premium adjustments reflect changing claim volumes from severe convective storms, rising labor and construction materials expenses, and localized environmental risks. In high-growth communities like Austin, Round Rock, and Cedar Park, frequent hailstorms and regional contractor demand heavily influence market-wide claims payouts. Evaluating your homeowners insurance austin policy annually ensures your coverage limits remain aligned with actual regional reconstruction expenses without unexpected gaps.