What a 2% Homeowners Insurance Deductible Means in Texas
Understand your 2 percent homeowners insurance deductible Texas policy. Learn how dwelling coverage sets your out-of-pocket costs for wind and hail claims.
What if a 2% deductible is based on your home’s insured value, not the cost of repairing storm damage? That’s a key point to understand about a 2% homeowners insurance deductible in Texas. It’s reasonable to wonder how the math works and how much you might pay after hail or wind damage.
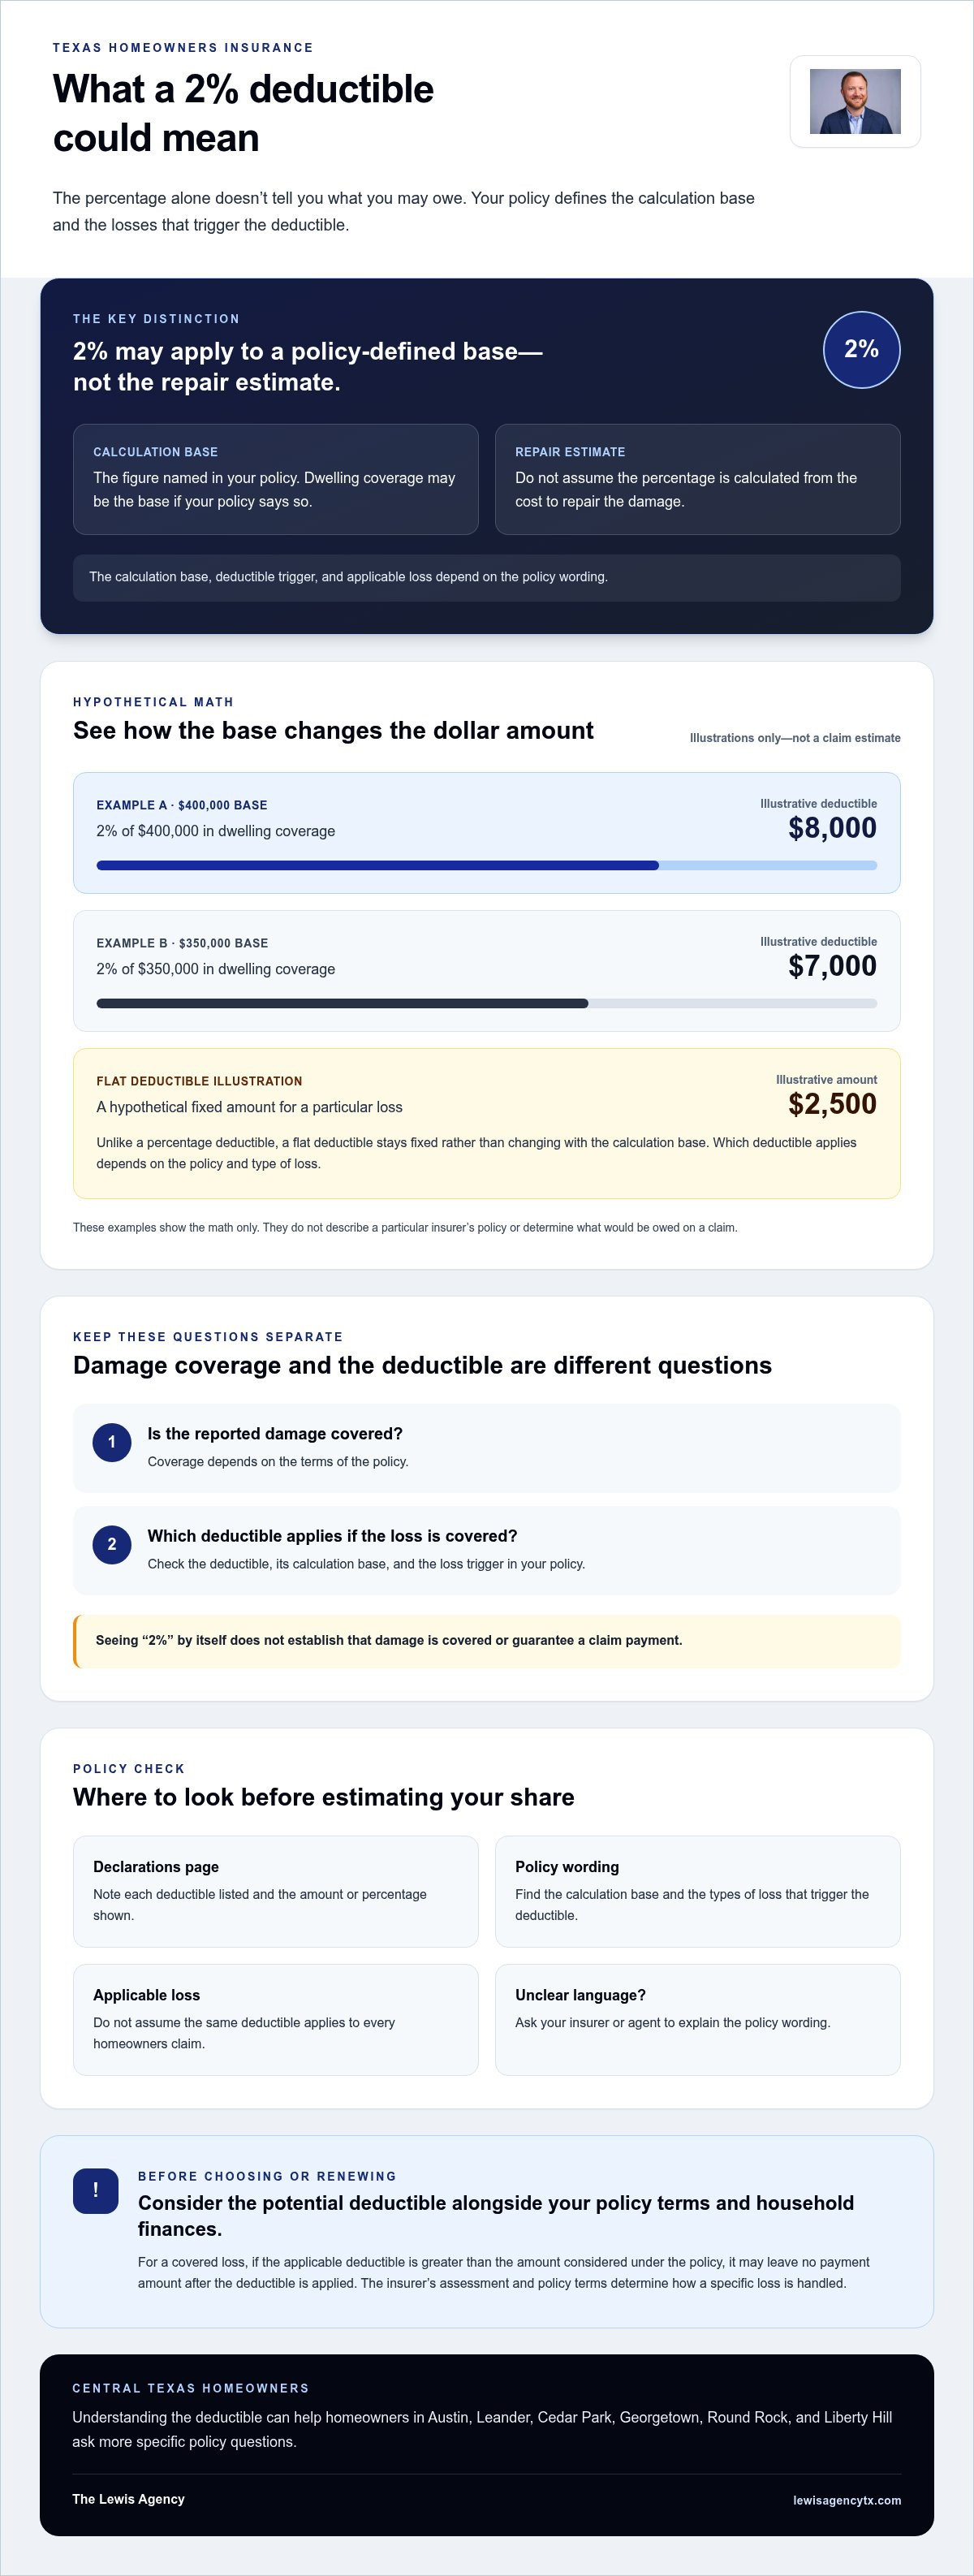
For a simple hypothetical example, 2% of $400,000 in dwelling coverage is $8,000. That figure isn’t a promise about what you’d owe on a claim. The deductible that applies depends on your policy’s wording, the cause of the damage, and any stated trigger. A percentage deductible can work very differently from a flat dollar deductible, so check which one applies before a storm.
This article explains how the calculation may work, what it could mean for a covered loss, and where to check your policy documents. If you’re reviewing homeowners coverage in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, or Liberty Hill, understanding the deductible can help you ask more specific questions when choosing or renewing a policy.
Key Takeaways
- A percentage deductible may be calculated using a base stated in your policy, not the repair estimate. Check the wording before estimating what you might pay.
- If your Texas policy has a 2% deductible, confirm which types of loss trigger it.
- Find the declarations page, note each deductible listed, and check the policy wording for the calculation base and applicable losses.
- A deductible is only one part of a coverage decision. Consider its potential cost alongside your policy’s terms and your household finances.
- The Lewis Agency works with homeowners to identify risks and match them with appropriate coverage, including policy limits and endorsements suited to their needs.
What does a 2% homeowners insurance deductible mean in Texas?
A percentage deductible is calculated using a base identified in the policy, rather than automatically using the repair estimate. The base and the losses that trigger the deductible can vary by insurer, policy form, and endorsements. In general, a deductible is the amount applied to a covered loss under the policy before any claim payment is considered. For a broader overview, see this explanation of an insurance deductible.
So, a 2% deductible doesn’t necessarily mean you pay 2% of your roof repair bill. The percentage alone doesn’t tell you the dollar amount. Find the calculation base in your own policy documents before estimating your share.
What figure might a 2% deductible apply to?
Check the declarations page and the policy wording for the base used to calculate the deductible. Dwelling coverage may be the base if your policy says so, but don’t assume that applies to every Texas policy. Look for the stated percentage, the figure it applies to, and the types of loss for which it applies.
If those details aren’t clear, ask your insurer or agent to explain the wording. A quote or summary may not include all the terms that appear in the policy.
How is a percentage deductible different from a flat deductible?
A percentage deductible is a policy-defined share of a specified base, while a flat deductible is a fixed dollar amount. Which applies depends on the policy and the type of loss. Both are ways a policy may set the homeowner’s deductible. Don’t assume one replaces or applies alongside the other without checking the documents.
Here’s a hypothetical calculation, not a statement about a particular insurer’s policy: if a policy identifies $350,000 in dwelling coverage as the base, a 2% deductible using that base would be $7,000. If a separate hypothetical policy instead lists a flat $2,500 deductible for a particular loss, that amount would stay fixed rather than rise or fall with the selected calculation base. These figures illustrate the math only.
For Texas homeowners considering a 2% deductible, the policy’s specific wording, not a general example, determines the calculation. Before estimating what you might pay, verify the deductible amount, its calculation base, and its trigger in your documents. Whether the damage itself is covered is a separate question, also determined by the policy terms.
How a Texas 2% deductible may affect a wind or hail claim
After a hailstorm in Central Texas, a homeowner may see roof damage and wonder whether a 2% deductible applies. The answer depends on the policy’s wording. A percentage deductible applies only to the types of loss identified in the policy and when its stated conditions are met.
Keep two questions separate. First, does the policy cover the reported damage? Second, which deductible applies if the loss is covered? A deductible doesn’t establish that damage is covered or guarantee a claim payment. For broader context on Texas homeowners policies and deductibles, see the Texas Department of Insurance Home insurance guide.
Does a 2% deductible apply to every homeowners claim?
Not necessarily. A policy may describe different deductibles for different causes of loss, but don’t assume every Texas policy has a separate wind or hail deductible. Check the declarations page and policy wording for the loss trigger and the deductible that applies. If the wording is unclear, ask your insurer or agent to explain it.
Imagine a hypothetical hailstorm damages a home in Round Rock. The policy’s terms would determine whether the reported damage is covered and whether the wind or hail deductible applies. Seeing “2%” on a document alone doesn’t answer either question. For homeowners researching “2 percent homeowners insurance deductible texas,” the policy’s specific wording is the useful guide, not the percentage in isolation.
What if the damage estimate is less than the deductible?
If a loss is covered and the applicable deductible is greater than the amount considered under the policy, the deductible may leave no payment amount after it is applied. That’s a general explanation, not a claim outcome. The insurer’s assessment and the policy’s terms determine how a particular loss is handled.
If you receive an estimate below your deductible, don’t treat that figure alone as a coverage decision. Confirm which deductible applies, what amount the insurer is evaluating, and whether other policy terms affect the claim. Your insurer can answer questions about a specific claim. An agent can help clarify policy language.
Before storm season, identify the trigger and deductible in your documents. If you’re choosing or reviewing homeowners coverage, contact The Lewis Agency to discuss your coverage needs. The agency works with homeowners in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, and Liberty Hill to identify risks and match them with appropriate policies.
How to check whether your Texas policy has a 2% deductible
A review of your policy documents can help you understand whether a 2% deductible applies and what the percentage means. Start with the declarations page, then use the full policy and any endorsements to confirm how the deductible works. The declarations page is a useful summary, but a short label may not explain every condition.
If you’re searching for a “2 percent homeowners insurance deductible texas” explanation, use general information as a starting point. Your own documents determine the calculation base, which types of loss may trigger the deductible, and how it works with other policy terms.
Where should you look on the declarations page?
Find the section that lists deductibles. Look for a percentage and any wording that identifies wind, hail, or another cause of loss. Note the exact language and any amount or coverage limit the percentage may be based on.
Next, check the full policy wording and endorsements. A label such as “wind/hail” may not explain all the conditions that determine when the deductible applies. If a term is unclear, don’t rely on the label alone.
The Texas homeowners insurance deductibles guide can provide additional context as you review your documents.
Which questions should you ask about the deductible?
Use the policy wording when you contact your insurer or agent. Specific questions can help clarify how the terms apply to your coverage:
- What is the calculation base? Ask what amount or limit the percentage is applied to under this policy.
- Which losses trigger it? Confirm the causes of loss named in the policy and whether the deductible applies to the event you’re asking about.
- How does it work with other terms? Ask how the deductible interacts with other applicable deductibles, conditions, or endorsements.
For example, if the documents list a percentage but don’t clearly state what it applies to, ask the insurer or agent to point to the relevant policy language. Avoid estimating your out-of-pocket share from the percentage alone.
Keep a note of the answers alongside your policy documents, especially when reviewing coverage before renewal or storm season. Terms can vary by insurer, policy form, endorsements, and individual circumstances, so a general explanation may not settle a question about your specific policy. Confirm the percentage, calculation base, and loss trigger using the documents that apply to your home.
How to weigh a 2% deductible before choosing or renewing coverage
A deductible is one part of a homeowners policy decision, not a stand-alone measure of whether coverage fits your needs. Consider the policy’s coverage and exclusions, the deductible’s calculation base, and whether your household could manage the amount if a covered loss occurred. The right choice depends on your circumstances and the exact policy terms.
Don’t compare quotes by percentage alone. A “2%” figure can’t tell you the potential dollar amount unless you know what the policy applies it to and which loss triggers it. Review the actual deductible wording in the proposed policy, and check that you understand the calculation before deciding. Choosing a higher or lower deductible doesn’t guarantee a particular premium change or savings.
What should homeowners consider alongside the percentage?
Start with the policy’s stated calculation base, then consider whether the resulting deductible would be manageable for your household. Also review roof coverage separately. The deductible describes your share of an applicable covered loss, while roof settlement terms address how the policy may value covered roof damage. For help understanding that distinction, see this guide to actual cash value versus replacement cost for a Texas roof.
These are related but different policy questions. A deductible figure alone doesn’t explain how roof damage may be settled, and settlement wording doesn’t tell you which deductible applies. Look at both parts of the policy rather than assuming one answers the other.
What should you clarify before renewal?
Compare your current policy with the proposed renewal documents. Check whether the deductible percentage, calculation base, or stated loss triggers have changed. If a term is unfamiliar, ask your insurer or agent to explain it using the actual policy wording before deciding whether to renew or change coverage.
It can help to write down what you want clarified: the amount the percentage applies to, the losses that trigger it, and how roof settlement terms work. For wider context on reviewing policy details, consult this Austin homeowners insurance coverage guide.
A search for “2 percent homeowners insurance deductible texas” can provide a general starting point, but your policy documents are what matter for your decision. If you’re considering homeowners coverage or reviewing your options, contact The Lewis Agency to discuss your coverage needs. The agency works with homeowners across Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, and Liberty Hill, helping identify risks and match them with appropriate policies.
Where Central Texas homeowners can get help understanding a 2% deductible
Before you need to make a claim, take a few minutes to find the deductible wording in your policy. Confirm the percentage, identify the amount or limit it’s calculated against, and check which types of loss may trigger it. Those details make “2 percent homeowners insurance deductible texas” more concrete, but only your policy documents can explain how the terms apply to your home.
The Lewis Agency works with homeowners in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, and Liberty Hill. Its homeowners insurance service helps clients consider their risks, policy limits, and endorsements when choosing coverage. The insurer and policy terms govern whether a loss is covered and what a claim will pay.
What an agency can and cannot clarify
An agency can help you understand coverage options and identify questions to ask about policy wording. That guidance can make it easier to consider how limits and endorsements relate to your needs, but it doesn’t change the contract. The insurer makes coverage, claim, underwriting, and renewal decisions. For a specific claim or final interpretation, refer to the governing policy documents and confirm details with the insurer.
This distinction matters. A general explanation can help you understand what to look for, but it can’t guarantee how the terms will apply to a particular loss. Policy language, endorsements, and circumstances all matter.
A practical next step for Austin and Central Texas homeowners
Review your deductible before storm season or policy renewal, rather than waiting until you’re trying to understand it during a stressful situation. Have your declarations page and the relevant policy wording ready. If a term is unclear, note the exact wording and ask what the calculation base is, which loss triggers the deductible, and how other policy terms may affect its application.
That preparation can help you have a more focused conversation with your insurer or agent. It also gives you a chance to consider whether the deductible amount would fit your household finances, without assuming a particular claim outcome.
If you’re choosing or reviewing homeowners coverage, learn more about The Lewis Agency and discuss your needs. The agency works with homeowners in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, and Liberty Hill to identify risks and match them with appropriate coverage.
Review your deductible before the next storm
A 2% deductible is easier to assess once you know the calculation base and which losses trigger it. The percentage alone doesn’t tell you what you might owe, and it doesn’t determine whether damage is covered. Check the declarations page and full policy wording, then consider the deductible alongside your roof coverage and household finances.
Understanding the “2 percent homeowners insurance deductible texas” homeowners may see in a policy starts with those specific terms, not a general example. Insurance coverage and wording vary, so confirm unclear details with your insurer or agent before renewal or a claim.
If you’re a homeowner in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, or Liberty Hill and want to discuss coverage options, contact The Lewis Agency. The agency works directly with clients to identify risks and match them with appropriate homeowners policies. Review your policy terms with your insurer for answers about a specific claim.
Frequently Asked Questions
Is a 2% wind and hail deductible based on my home's value?
Not necessarily. Your policy identifies the calculation base, so don’t assume the percentage applies to your home’s market value or the repair cost. Check the declarations page and the applicable policy wording for the amount or limit used and the losses that trigger the deductible. If the base isn’t clear, ask your insurer or agent to explain how the actual calculation works for your policy.
How do I calculate a 2% homeowners insurance deductible?
Use this formula only if your policy confirms the base: stated calculation base × 0.02. For example, if a hypothetical policy specifies a $300,000 base, the calculation would be $300,000 × 0.02, or $6,000. This illustrates the math, not a standard Texas policy structure. The resulting deductible applies only as the policy describes for a qualifying loss, so confirm both the base and loss trigger in your documents.
Does a 2% deductible apply to every homeowners insurance claim in Texas?
No, don’t assume a percentage deductible applies to every claim or every cause of damage. The applicable deductible and its trigger depend on the specific policy and loss. Check the declarations page for deductible entries, then review the policy wording for conditions or endorsements that explain when each applies. If the trigger is uncertain, ask your insurer or agent to clarify it using your actual policy documents.
Can I change my 2% deductible when my homeowners policy renews?
That depends on the insurer and the renewal terms. Ask whether any deductible options are available and what policy wording would change before assuming you can select a different amount. A change shouldn’t be treated as a guaranteed way to save money or alter your premium by a particular amount. Review the proposed renewal documents alongside your current policy so you can understand the terms before deciding.
What happens if hail damage costs less than my deductible?
A deductible generally reduces an otherwise covered payment according to the policy. If an estimate is below the applicable deductible, that may mean no payment is made, but an estimate alone doesn’t establish coverage or the final claim amount. The insurer evaluates the claim under the policy terms. Report damage concerns as appropriate, and ask your insurer about the claim and which deductible applies.
Where can I find my Texas homeowners insurance deductible?
Start with your declarations page and locate the deductible amount or percentage. If the summary doesn’t explain the calculation base or applicable loss, check the full policy and endorsements. An agent can help clarify policy language, while the policy and insurer govern coverage and claim decisions. The Lewis Agency works with homeowners in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, and Liberty Hill.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.

Texas Roof Hail Damage Deductible Guide 2026
Wondering how roof hail damage deductible insurance Texas policies work? Learn how dwelling limits, percentage deductibles, and ACV affect your claim costs.
If severe spring weather damages your roof tomorrow, how much will you really pay out of pocket before your coverage kicks in? When examining a roof hail damage deductible insurance Texas homeowners often expect a simple flat fee or a small charge tied to the roofer's repair bill. In reality, wind and hail deductibles scale directly with your home's total dwelling reconstruction limit, which can mean thousands of dollars in sudden out-of-pocket expenses.
It is completely understandable to feel overwhelmed by confusing policy math, especially when you are also trying to interpret actual cash value schedules and strict state deductible payment laws. This guide explains how Texas wind and hail deductibles work so seasonal storm repairs never bring unexpected financial surprises to your household. You will discover how percentage deductibles are calculated against your dwelling limit, learn the critical difference between replacement cost and actual cash value roof coverage, and find out how to review your policy endorsements before severe spring storms arrive.
Key Takeaways
- Texas home policies frequently separate wind and hail damage from standard perils, creating distinct out-of-pocket rules for storm claims.
- When evaluating your roof hail damage deductible insurance Texas policies calculate that percentage against your total dwelling limit rather than the roofer's repair bill.
- The difference between Replacement Cost Value and Actual Cash Value determines whether your insurer pays full replacement costs or subtracts for roof age.
- Texas House Bill 2102 strictly prohibits contractors from paying, waiving, or rebating property insurance deductibles.
- Reviewing your policy declarations page before peak spring storms helps you budget effectively and avoid sudden financial surprises.
How Roof Hail Damage Deductibles Work in Texas Home Insurance
A property insurance deductible represents the specific out-of-pocket amount you agree to pay toward an approved claim before your insurer pays the rest. Understanding how insurance deductibles work as a foundational risk-sharing tool is especially vital in Texas, where severe convective storms routinely drop large hail across entire neighborhoods. In years past, homeowners often paid a simple flat fee like $1,000 for any covered loss. Today, coverage structures have shifted toward percentage-based thresholds that treat severe weather claims distinctly from routine property losses.
The Distinction Between All-Peril and Hail Deductibles
Reviewing your policy declarations page reveals an important layout: Texas carriers routinely separate property perils into distinct buckets. Rather than listing a single deductible, your policy typically outlines two separate amounts:
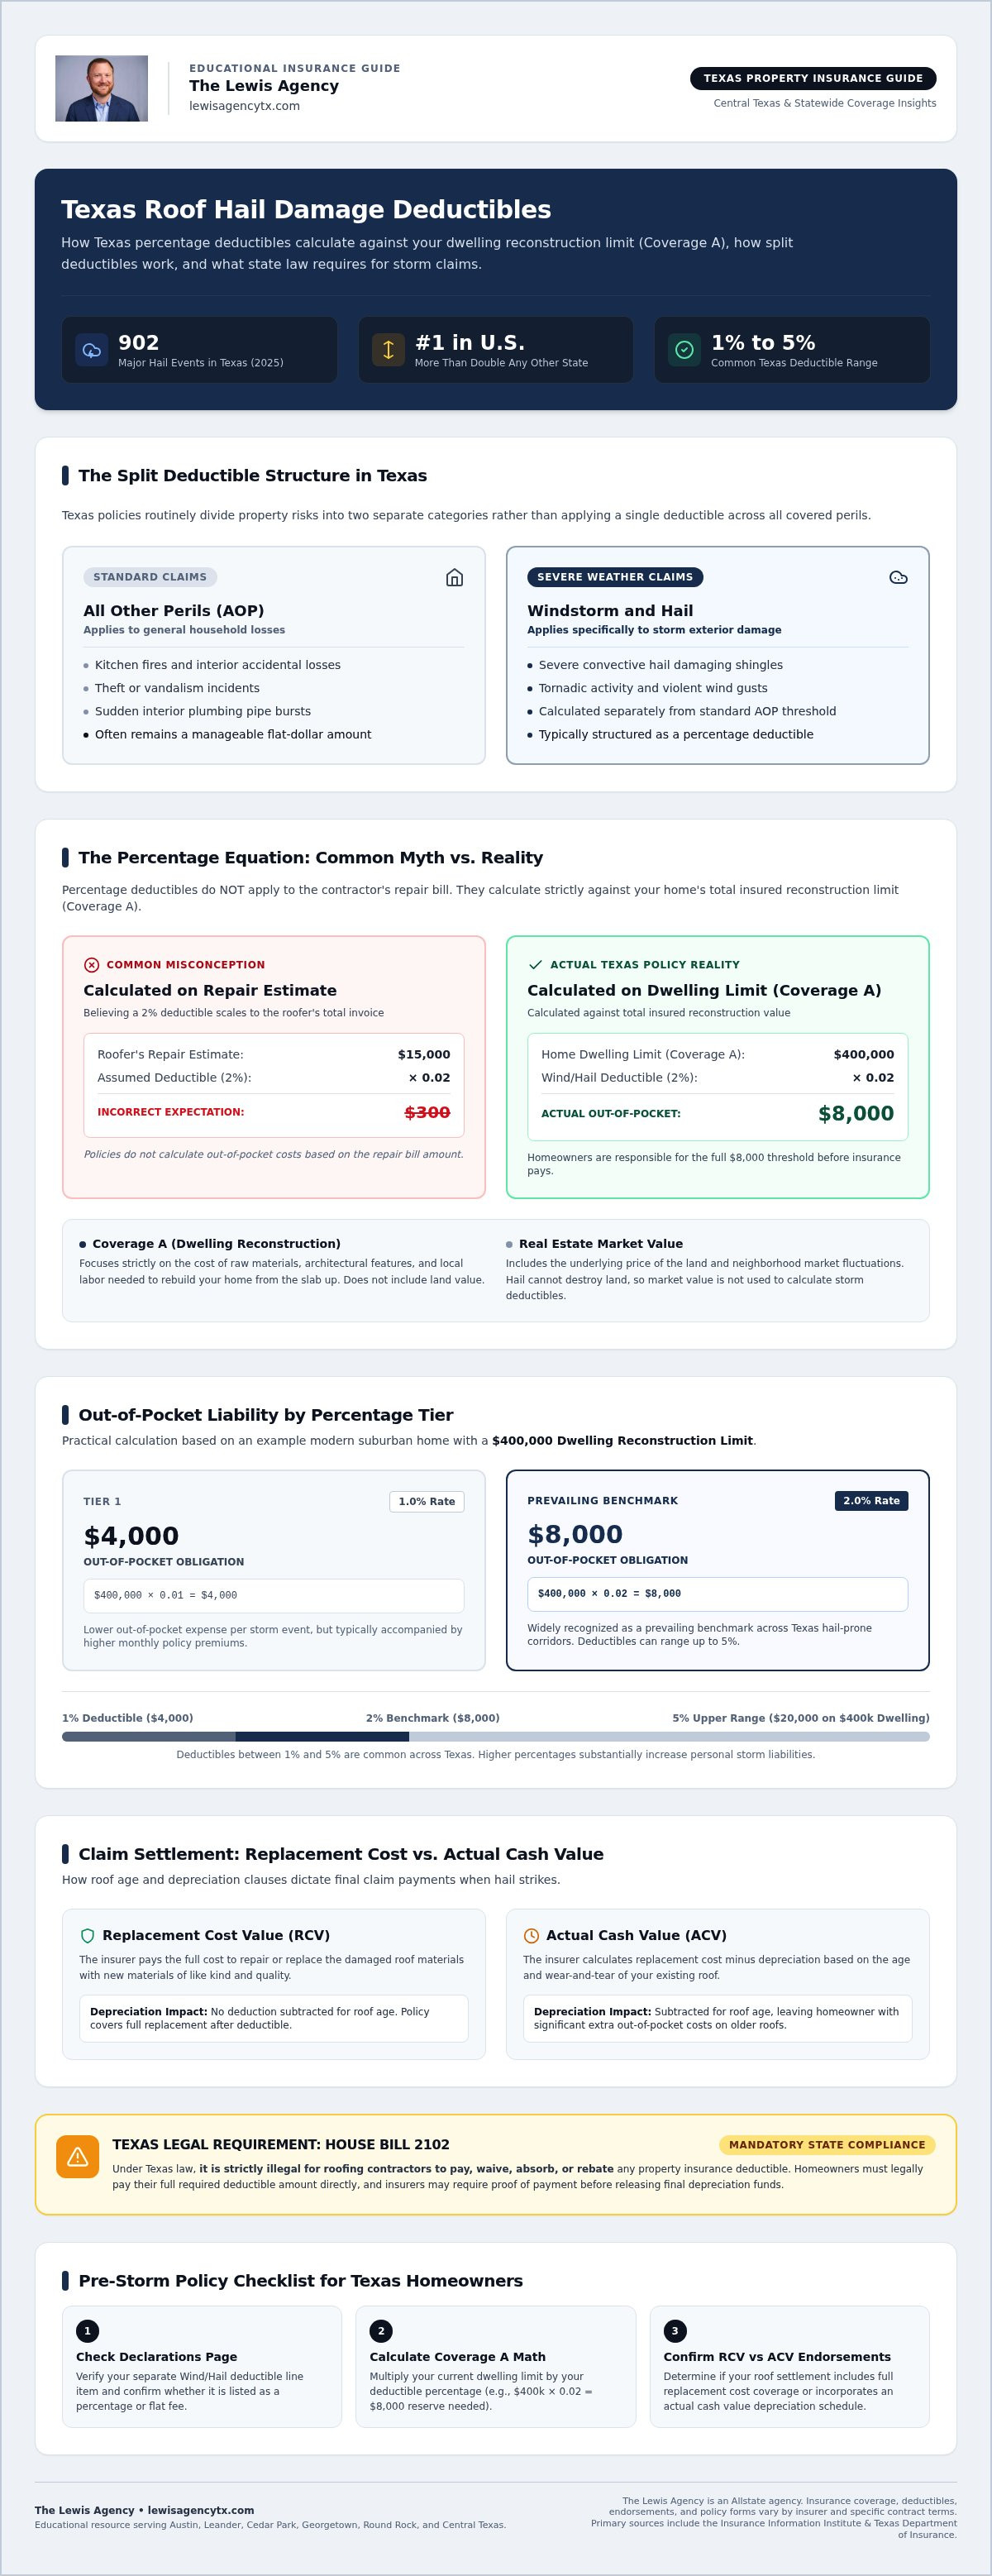
- All Other Perils (AOP): This applies to standard household losses, including kitchen fires, theft, or sudden pipe bursts. It often remains a manageable flat-dollar amount.
- Windstorm and Hail: This specific clause triggers only when wind, tornadic activity, or severe hail damages your exterior structure.
When evaluating a roof hail damage deductible insurance Texas policies apply this dedicated weather clause rather than your base property threshold. That means an interior water leak from an appliance triggers your standard AOP deductible, but shingles torn apart by spring hailstones trigger the separate wind and hail deductible.
Why Texas Insurers Require Separate Hail Deductibles
Why do carriers separate hail damage from other risks? Texas consistently leads the country in major hail events, creating massive property claim volumes each spring. According to the Insurance Information Institute, Texas recorded 902 major hail events in 2025 alone, more than double any other state. To manage this concentrated weather risk while keeping baseline homeowners insurance premiums accessible, insurers implement split deductible structures. Deductible structures vary across different policy forms and carrier guidelines, making it vital to understand your exact policy terms long before turbulent storm fronts develop.
Calculating Your Percentage Deductible: The Coverage A Equation
One common misconception among homeowners is assuming a two percent deductible means paying two percent of the roofer's total repair estimate. If an estimate comes out to $15,000, paying two percent would only be $300. That is not how property policies operate. In Texas, percentage deductibles calculate strictly against your policy's Coverage A limit, which represents the total insured reconstruction value of your home. If you want to clarify your policy endorsements and structural limits before storm season arrives, scheduling an educational review with The Lewis Agency can help you verify your numbers.
The Math Behind One Percent and Two Percent Tiers
Many older state consumer guides still rely on outdated home valuations of $150,000, giving families an inaccurate impression of what they might owe. In today's market, modern suburban replacement costs tell a different story. Consider a dwelling limit of $400,000 to see how the percentage equation works in practice:
- 1% Wind/Hail Deductible: $400,000 multiplied by 0.01 equals an out-of-pocket obligation of $4,000.
- 2% Wind/Hail Deductible: $400,000 multiplied by 0.02 equals an out-of-pocket obligation of $8,000.
Deductibles between 1% and 5% are common across the state, with 2% widely recognized as a prevailing benchmark in hail-prone corridors. When factoring your roof hail damage deductible insurance Texas carriers apply this formula directly. A higher percentage significantly increases your personal out-of-pocket liability whenever severe weather strikes.
Dwelling Coverage Versus Real Estate Market Value
Coverage A does not reflect what you paid for your home or what a buyer might offer tomorrow. Real estate market values include the price of the underlying land, which cannot be destroyed by a hailstorm. Instead, Coverage A focuses entirely on the cost of raw materials, architectural features, and local labor needed to rebuild your home from the slab up. Official Texas Department of Insurance roof guidance highlights how critical these policy limits are when settling claims.
Keep in mind that most homeowners insurance policies include an automatic inflation guard. This endorsement periodically adjusts your dwelling limit upward to keep pace with rising construction and material expenses. While this safeguards you against underinsurance, it also steadily increases your nominal dollar deductible over time, even if your deductible percentage stays exactly the same.
Replacement Cost Versus Actual Cash Value on Hail-Damaged Roofs
Even after calculating your exact deductible, your final out-of-pocket obligation hinges on how your policy values your roof structure. Settling storm losses involves more than just subtracting your deductible from contractor estimates. The structural settlement valuation method specified in your policy determines whether you only pay your deductible or absorb thousands of dollars in architectural depreciation on top of it.
How Depreciation Impacts Out-of-Pocket Roof Expenses
Settlement terms fall into two main valuation categories. Replacement Cost Value (RCV) pays to repair or replace damaged shingles with comparable modern materials without reductions for age, subject to policy limits. Insurers typically disburse RCV payouts in two stages: an initial payment reflecting actual cash value, followed by a second check for recoverable depreciation once you provide proof of completed repairs.
Actual Cash Value (ACV) functions differently. Under ACV terms, the insurer deducts accumulated wear and tear before issuing payment. That depreciation is non-recoverable. As the Insurance Information Institute's deductible breakdown notes, your deductible applies directly to the settled loss amount. When filing under a roof hail damage deductible insurance Texas homeowners holding ACV policies must fund both their full percentage deductible and the accrued roof depreciation entirely on their own.
Understanding Roof Schedules and Cosmetic Waivers
Insurers across Texas increasingly attach specific roof endorsements at policy renewal, particularly when shingles reach 10 to 15 years of age. Understanding these clauses prevents unpleasant surprises when adjusters inspect your property:
- Roof Surface Payment Schedules: These endorsements establish a sliding payout scale based on shingle age. As your roof gets older, the carrier pays a smaller percentage of replacement costs, requiring you to self-insure the remaining balance.
- Cosmetic Damage Waivers: Many policies covering metal or Class 4 impact-resistant roofs now exclude cosmetic damage. If severe hail leaves visible dents or dimples across metal panels but does not puncture the surface or compromise water-shedding performance, the carrier may deny the claim entirely.
Reviewing these endorsements early ensures you know exactly how age and cosmetic criteria affect your roof hail damage deductible insurance Texas coverage before severe thunderstorms roll in.
Texas Law and Hail Deductibles: Understanding House Bill 2102
Following intense hail storms, homeowners often encounter roofing vendors promising to handle the entire repair without any out-of-pocket expense. Texas law strictly prohibits these arrangements. Under Texas Insurance Code Chapter 707 and Texas Business and Commerce Code Section 27.02, codified by House Bill 2102, roofing contractors cannot lawfully pay, waive, absorb, rebate, or credit any portion of a property deductible. The statute ensures that policyholders take personal financial responsibility for their contracted share of storm restoration.
Why Free Roof Offers Create Legal Risks
Door-to-door sales pitches advertising a free roof might sound tempting, but agreeing to one carries genuine legal danger. To bypass your deductible, an unscrupulous contractor must typically submit inflated or altered invoices to your carrier, asserting that you paid costs you never actually covered. Concealing unpaid deductibles through deceptive billing constitutes criminal insurance fraud. Under Texas law, violations are classified as a Class B misdemeanor, punishable by fines up to $2,000, up to 180 days in county jail, or both. Any repair contract over $1,000 must include a mandatory consumer disclosure stating in bold type that the law requires you to pay your deductible.
Proof of Payment Requirements for Insurance Claims
Carriers actively verify compliance before releasing claim funds. Under state law, insurers issuing replacement cost coverage possess the explicit statutory authority to demand reasonable proof of deductible payment before disbursing withheld recoverable depreciation. Adjusters frequently ask for verified records, such as:
- Cleared bank checks or electronic transaction receipts
- Credit card billing statements showing the processed transaction
- Formal installment loan or financing contracts obligating you to full payment
Without acceptable proof, the carrier will simply withhold that second depreciation check. When handling a roof hail damage deductible insurance Texas property owners should always request itemized invoices matching the approved adjuster scope of loss. If you want to confirm your coverage limits and understand how state deductible mandates apply to your property, reach out to The Lewis Agency for a personalized policy checkup.
Preparing Your Roof Coverage Before Central Texas Hail Season
Peak hail activity across Central Texas typically hits hardest from March through June, when warm Gulf moisture collides with drylines and advancing cold fronts. Waiting until severe thunderstorm alerts sound across your neighborhood is the worst time to discover gaps in your coverage. Preparing ahead of time ensures that storm damage leads to a smooth recovery rather than unexpected out-of-pocket expenses.
Balancing Deductible Choices Against Premium Budgets
Selecting the right deductible requires balancing your ongoing premium costs against your household emergency savings. Choosing a higher percentage deductible can help reduce your regular homeowners insurance premium. However, it also demands substantial liquid cash if baseball-sized hail hammers your roof. When budgeting for your roof hail damage deductible insurance Texas guidelines emphasize matching your cash reserves to your actual dollar exposure rather than an abstract percentage.
Upgrading your roof materials can also make a meaningful financial difference. Many carriers offer policy discounts for homes protected by UL 2218 Class 4 impact-resistant shingles or qualified metal roofing systems. While discount options vary by carrier and policy contract, these durable products resist hail impact effectively, reducing the likelihood of minor claims while protecting your structure.
Reviewing Your Policy with The Lewis Agency
Before spring storms arrive, take a moment to audit your declarations page. You will want to verify whether your roof is covered under full replacement cost terms or a depreciated roof surface payment schedule. You should also check whether your Coverage A dwelling limit still accurately reflects current Central Texas construction costs. Additionally, scheduling a qualified roof inspection during calm weather creates a clear photo record of your pre-storm shingle condition, giving you documented proof should a disputed claim arise later.
Understanding your coverage details shouldn't feel like navigating a maze alone. As a dedicated Allstate agency serving Austin, Cedar Park, Leander, Round Rock, and neighboring communities, Chris Lewis at The Lewis Agency provides neighborly, educational guidance to help you examine your dwelling limits and understand your storm endorsements. Taking time to review your roof hail damage deductible insurance Texas coverage today gives you the clarity and confidence needed to weather whatever the Texas skies bring this season.
Take Control of Your Hail Coverage Before the Next Storm
Navigating seasonal storm repairs starts with clarity, not guesswork. When evaluating a roof hail damage deductible insurance Texas homeowners must remember that their out-of-pocket obligation scales with their total dwelling reconstruction limit rather than the roofer's repair estimate. Knowing whether your policy provides full replacement cost protection or enforces actual cash value depreciation schedules ensures you aren't blindsided by repair costs. Combined with state laws requiring policyholders to pay their full deductible, auditing your terms ahead of time is the best way to protect your household budget.
You don't have to decipher complex policy declarations on your own. As a dedicated Allstate agency serving Austin, Round Rock, Cedar Park, and surrounding Central Texas communities, The Lewis Agency is here to support you. Insurance professional Chris Lewis provides grounded, personal guidance to help you examine your dwelling limits, understand weather endorsements, and answer your storm deductible questions. Review your roof hail coverage with The Lewis Agency today so you can face severe weather season with confidence.
Frequently Asked Questions
What is a typical roof hail damage deductible for Texas homeowners?
Most Texas homeowners carry a wind and hail deductible between 1% and 2% of their home's Coverage A limit, though policies can range up to 5%. For a home insured for $400,000, a standard 2% deductible equals $8,000 in out-of-pocket costs. In Central Texas communities like Round Rock and Cedar Park, percentage deductibles have become the regional standard because severe spring thunderstorms produce frequent hail events across Travis and Williamson counties.
Can a Texas roofing contractor legally pay or waive my deductible?
No, it is illegal for any roofing contractor to pay, waive, rebate, or absorb your deductible under Texas law. House Bill 2102 established that policyholders must pay their full deductible directly. Contractors offering to cover your deductible commit a Class B misdemeanor, and homeowners who knowingly participate in these billing schemes can face criminal insurance fraud penalties. Legitimate contractors will always invoice you directly for the deductible amount required by your policy contract.
Is my hail deductible calculated from the repair estimate or dwelling limit?
Your deductible is calculated strictly from your total Coverage A dwelling limit, never from the contractor's repair estimate or the real estate market value of your property. For a roof hail damage deductible insurance Texas carriers apply your stated percentage directly against your insured structure limit. If your home has a $450,000 dwelling limit with a 1% deductible, your out-of-pocket obligation is $4,500, regardless of whether roof repairs cost $6,000 or $25,000.
What happens if storm damage repairs cost less than my deductible?
If the total cost to fix hail damage falls below your deductible amount, your insurance carrier pays zero dollars toward the repair. For instance, if an adjuster estimates roof repairs at $3,500 but your 1% deductible on a $500,000 home is $5,000, the expense rests entirely on you. Homeowners across Austin and Pflugerville should obtain an independent inspection before filing a claim for minor damage to avoid an unnecessary claim on their record.
How do replacement cost and actual cash value roof coverage differ?
Replacement Cost Value (RCV) pays to repair or replace your hail-damaged roof with new materials of similar quality without factoring in roof age, once repairs are completed. Actual Cash Value (ACV) subtracts depreciation based on how old your shingles are before calculating payment. With an ACV policy, you must pay both your deductible and the accumulated depreciation out of pocket, which can leave you covering a substantial portion of total roof replacement costs.
Why does my Texas insurance policy list two different deductibles?
Texas policies frequently separate standard perils from weather risks to manage extreme storm exposure. Your policy typically lists an All Other Perils (AOP) deductible for indoor risks like burst pipes or kitchen fires, alongside a separate wind and hail deductible. Evaluating your roof hail damage deductible insurance Texas documents will show that this split structure allows carriers to offer more manageable baseline premiums while accounting for the high volume of spring storms across Central Texas.
Can my insurer alter my roof deductible percentage upon renewal?
Yes, carriers can adjust deductible terms, raise percentage thresholds, or switch older roofs to actual cash value schedules when your policy renews. Insurers issue formal notice endorsements in renewal packets when these underwriting changes happen. Homeowners in growing areas like Leander and Buda should review their renewal declarations pages each year. Chris Lewis at The Lewis Agency helps local homeowners review their policy forms annually to ensure storm deductibles remain clear and manageable.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.