A Texas homeowners insurance quote is shaped by more than a home’s sale price. The premium can depend on the home’s age and value, its location, the coverage selected, and the deductible. For homeowners insurance quote information in Texas, these details help explain why quotes can differ from one home to another.
It’s reasonable to want a clear picture of what affects the cost before choosing coverage. This article explains the average cost of homeowners insurance in Texas, discounts that may be available, and the home and policy details insurers may consider.
You’ll also learn what information to gather before requesting a quote and how to assess factors that affect premiums, with practical considerations for homeowners in Austin and Central Texas.
Key Takeaways
- Security features, a fire sprinkler system, a claims-free history, or policies with the same company may open the door to discounts.
- Location, construction materials, home age, deductible, and coverage choices can all influence a premium.
- Learn which coverage details to review so you can prepare useful information for a homeowners insurance quote.
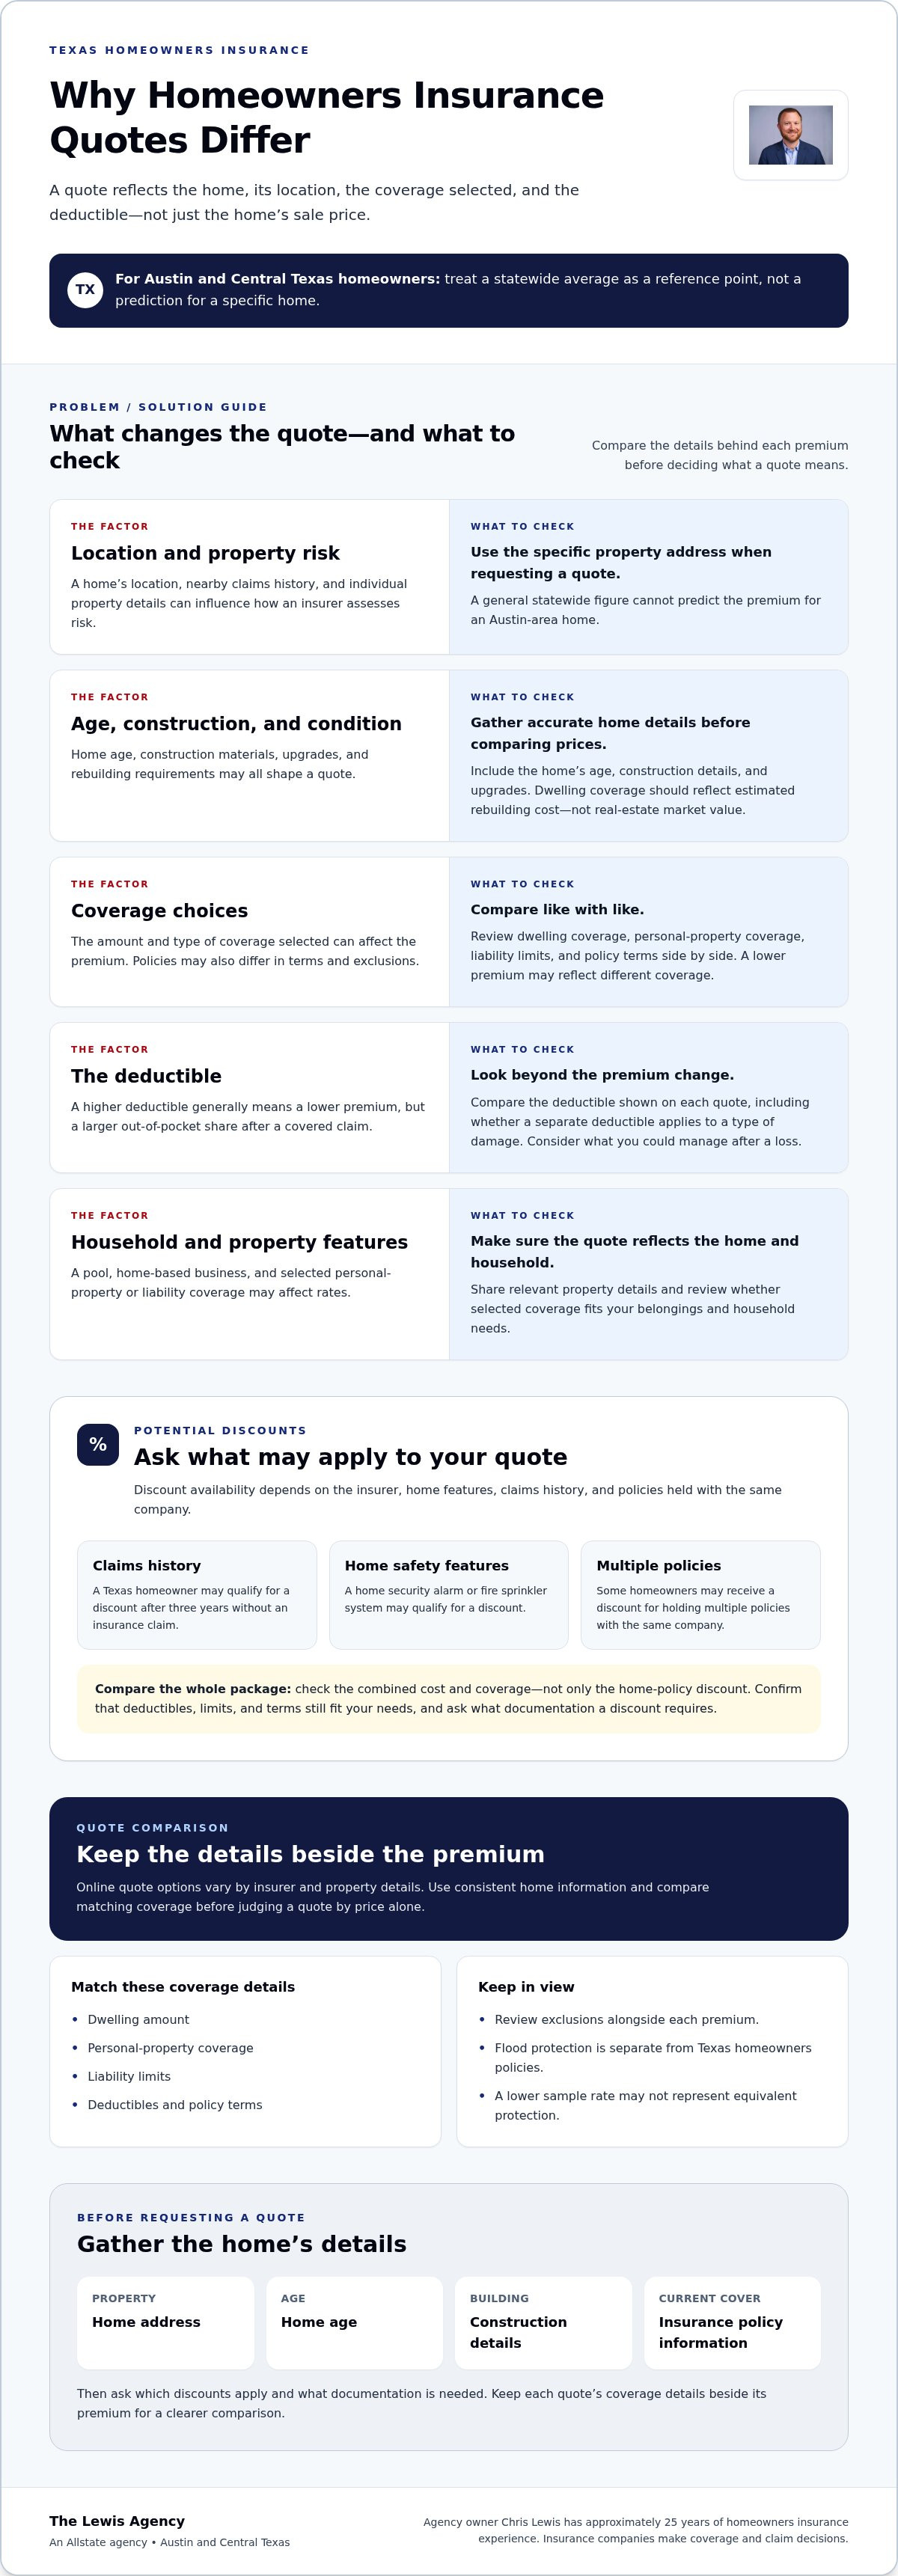
How Is the Average Cost of Homeowners Insurance in Texas calculated?
While industry data provides a statewide average annual premium to use as a baseline, that figure is only a general reference point, not a prediction for an Austin home. Location, age, construction, coverage choices, and the deductible can all shape a quote. Homeowners insurance quote information in Texas is most useful when it reflects the specific property and protection you need.
Texas doesn’t require homeowners insurance by law, though a mortgage lender will likely require it. Don’t end an existing policy until replacement coverage begins or you have written confirmation that coverage is in place.
Homeowners insurance commonly includes coverage for the dwelling, personal property, liability, and additional living expenses. Dwelling coverage may help pay to repair or rebuild after covered damage, such as hail or fire. Personal property coverage applies to belongings, while liability coverage may help with certain injury or property-damage expenses. Additional living expenses can help with extra costs if a covered loss makes the home temporarily unlivable. Texas homeowners policies don’t cover flood damage, so consider flood protection separately.
Check the policy for details beyond these core coverage types. Identity-theft assistance and refrigerated-food loss may have specific terms or limits. For valuable belongings, such as jewelry or artwork, review how the policy covers them and whether additional coverage is available. Quote details should clarify how the policy treats these items.
To choose a dwelling coverage amount, estimate the cost to rebuild the house, not its real-estate market value. Construction materials, home features, and rebuilding requirements shape that estimate. Then assess personal-property and liability limits in light of your belongings and household needs. An Austin homeowner with a pool, for example, should consider how liability protection relates to that feature.
Home insurance discounts
Discounts may depend on the insurer, home features, claims history, and policies held with the same company. Texas homeowners may qualify for a discount after three years without an insurance claim. A home security alarm or fire sprinkler system may also qualify. Ask how each discount applies to the quoted coverage instead of assuming it reduces every part of the premium.
Bundling home and auto insurance means placing both policies with one insurance company. Some homeowners may receive a discount for buying multiple policies from the same company. Compare the combined cost and coverage, not just the home policy’s discount. Check that the home and auto deductibles, limits, and terms still fit your needs.
Which Texas homeowners insurance companies offer online quotes? Online quote options vary by insurer and property details. Use an insurer’s own quote process where available, and provide consistent information about the home, its construction, and the coverage you want.
Compare quotes with matching dwelling amounts, personal-property coverage, liability limits, and deductibles. A lower sample rate may reflect different coverage or a different deductible, so it may not represent equivalent protection for a covered loss. If flooding is a concern, note whether flood insurance is handled separately. Keep each quote’s coverage details beside its premium for a clearer comparison.
Before requesting quotes, gather the home’s address, age, construction details, and current insurance policy information. Then ask which discounts apply and what documentation each requires. A homeowners insurance resource center can help you organize coverage questions before reviewing quote details.
Factors that affect homeowners insurance premiums
Texas premiums reflect the property’s risk and the amount and type of homeowners insurance coverage selected. Compare equivalent coverage before judging a quote by its premium alone.
Annual Premiums by Insurer
Annual premiums differ by insurer because companies assess property and coverage details differently. Compare quotes using the same dwelling amount, personal-property coverage, liability limits, and deductible. Then review exclusions and policy terms alongside each premium. A lower figure may reflect less coverage, so it doesn’t necessarily represent equivalent protection for the same property.
How Deductibles Affect Premiums
A higher deductible generally results in a lower premium. The tradeoff is a larger out-of-pocket share after a covered claim. Compare the deductible shown in each quote, including any separate deductible for a particular type of damage. Choose an amount you could manage after a loss, rather than focusing only on the premium change.
Other Premium Factors
Insurers may consider location, nearby claims history, construction materials, home age, and upgrades. Replacement cost estimates what rebuilding the home could require, rather than its market price. A pool, home-based business, or selected personal-property and liability coverage may also affect rates. Mortgage requirements can shape the coverage a homeowner selects.
What Makes Homeowners Insurance Quotes Different in Central Texas?
Homeowners in Austin, Leander, Cedar Park, Georgetown, and Round Rock face several considerations that can influence their homeowners insurance quotes. While every property is different, understanding these local factors can help homeowners make more informed coverage decisions.
Roof Age and Condition
In Central Texas, a home's roof can play an important role in the insurance quoting process. Insurance companies may consider the roof's age, material, condition, and replacement history when evaluating a property. Homeowners with older roofs may encounter different pricing or eligibility requirements than those with newer roofs.
Before requesting a quote, gather information about when your roof was installed, its construction materials, and any recent repairs or replacements.
Hail and Severe Weather Exposure
Austin and the surrounding communities experience severe thunderstorms that can bring hail, damaging winds, and heavy rainfall. Because roof damage is a common concern following these storms, homeowners should understand how their policy addresses wind and hail losses.
Coverage can vary depending on the insurance company, policy provisions, roof condition, and applicable exclusions or endorsements.
Wind and Hail Deductibles
Many Texas homeowners policies include a separate windstorm or hail deductible. These deductibles may be calculated as a percentage of the home's insured dwelling amount rather than as a fixed dollar amount.
For example, a 2% deductible on a home insured for $500,000 would equal $10,000. That amount represents the homeowner's deductible for a covered claim to which it applies, not necessarily the amount the homeowner will ultimately pay for repairs.
Understanding this distinction is particularly important for Central Texas homeowners comparing insurance quotes.
Local Rebuilding Costs
A home's market value is not necessarily the amount it would cost to rebuild after a covered loss. Construction labor, materials, architectural features, and local building requirements can all influence replacement costs.
In growing communities such as Leander, Georgetown, and Cedar Park, homeowners should periodically review their dwelling coverage to help ensure it reflects the estimated cost of rebuilding their home rather than simply its purchase price or current market value.
Get Guidance From a Central Texas Insurance Professional
With more than 25 years of insurance experience, Chris Lewis, owner of The Lewis Agency, helps homeowners throughout Austin and Central Texas understand how roof characteristics, deductibles, coverage options, and rebuilding costs can affect their insurance decisions.
Whether you're purchasing a new home or reviewing an existing policy, The Lewis Agency can help explain available Allstate coverage options and answer questions about your homeowners insurance quote.
The Lewis Agency: Homeowners Insurance Policies
The Lewis Agency is an Allstate agency offering homeowners insurance policies and guidance to help homeowners understand coverage. Agency owner Chris Lewis has approximately 25 years of homeowners insurance experience. He can explain policy language and answer questions about coverage options available through the agency.
A review can help when you’re buying a home, updating a policy, or reassessing coverage after renovations. Bring your quote or policy and note questions about how the home was evaluated. The Lewis Agency provides plain-English guidance on coverage and claims processes, while insurance companies make coverage and claim decisions.
For help with a quote or policy question, contact The Lewis Agency.
Make Your Next Coverage Review Count
A quote review can help you prepare for changes to your home, not just choose a policy today. Renovations, new belongings, or a change in how you use your property can make it useful to revisit your coverage. Keep notes about updates and questions so your next conversation focuses on what matters to your household.
For homeowners insurance quote information in Texas, The Lewis Agency can help explain policy language and answer questions about available coverage. The agency also offers Auto Insurance and Landlords Insurance for related needs. Coverage and terms depend on the policy and individual circumstances.
When you’re ready to talk through a quote or policy question, contact The Lewis Agency. A thoughtful review can help you take your next step with greater clarity.
Frequently Asked Questions
Is Home Insurance Mandatory in Texas?
Texas law doesn’t require homeowners insurance, but a mortgage lender will likely make it a condition of the loan. A lender will require flood insurance if the property is in a flood zone. Before closing, review the lender’s insurance requirements alongside the policy documents so you understand what coverage must be in place.
What risks does a homeowners insurance policy cover?
Depending on the policy, covered risks may include fire, theft, vandalism, lightning, wind, hail, explosions, falling objects, and the weight of snow or ice. For example, hail may damage a roof, while a falling tree limb may damage a structure. Review the policy’s exclusions and terms to understand how it treats each type of loss.
Are there ways I can help protect my home?
Yes. Keep records of roof work and home improvements, and store photos of important belongings in a secure location. Before a Central Texas storm, secure loose outdoor items and check that windows and doors close properly. After a storm, document visible damage from a safe location. These steps support preparedness but don’t change what a policy covers.
How Can I Lower My TX Home Insurance Rate?
Start by checking that the quote reflects the home’s current features and the coverage you want. Ask about discounts tied to safety features or policy eligibility, then compare the total premium, deductible, and coverage terms. A higher deductible may reduce the premium, but consider whether you could afford that out-of-pocket amount after a covered loss.
Trouble finding insurance?
If applications are declined or quotes are difficult to obtain, identify the reason given and gather relevant property details, such as roof age, construction, and repair records. Clear, consistent information can help explain the home’s condition during an application. The Texas FAIR Plan is an option Texas residents who can’t find an insurer may contact for information about coverage.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.