Texas homeowners insurance costs and why rates are rising
Learn why Texas homeowners insurance costs increase, how severe weather and rebuilding costs affect premiums, and what to review in your policy and budget.
A rising premium is only part of the affordability picture. Understanding why Texas homeowners insurance costs increase starts with severe weather losses and the cost of repairing or rebuilding damaged homes, which can put pressure on premiums. The increase also matters in the context of mortgage payments, property taxes, and other costs of owning a home.
If your renewal is becoming harder to fit into the household budget, that concern is understandable. This article explains why Texas homeowners insurance costs increase, including how storms can affect premiums and why insurance has become a larger part of homeownership expenses. It also covers factors that may affect your individual policy, helping you understand its price and coverage.
Key Takeaways
- Understand how Texas insurance regulation works and what it can tell you about market stability.
- See how repeated severe-weather losses can put upward pressure on homeowners insurance rates.
- Put insurance premiums in context alongside the other costs of owning a Texas home.
- Learn which policy details to review so you can better understand your coverage and household budget.
Is Texas experiencing a home insurance crisis?
Texas homeowners are facing rising premiums, but an increase by itself does not prove there is a market crisis. The figures help explain why affordability matters to households balancing mortgage payments and other homeownership costs.
Texas regulates insurance rates through the Texas Department of Insurance. Insurers can apply rate changes before official approval, subject to standards and possible disapproval by the insurance commissioner. A Texas Senate bill passed in 2025 would have required regulators to approve rate increases above 10% before insurers implemented them. The proposal addressed prior review of larger increases, not a promise of lower premiums.
How much have Texas homeowners insurance rates increased in recent years? These annual figures show a rising trend, although individual renewals can differ.
A home’s value, age, roof condition, and construction materials help insurers assess its condition and potential rebuilding needs. These details may inform underwriting, but their effect depends on the insurer and policy.
How do insurers use claims history, credit-based insurance scores, and deductibles to set rates? The treatment of claims history and credit-based scores varies by insurer. Deductibles can affect premiums: according to the Texas Department of Insurance, higher deductibles mean lower premiums but more out-of-pocket expense after a claim. Your quote depends on your home, its condition, location, and policy details; the exact figure is provided in a quote for your case.
Severe weather losses and insurance costs
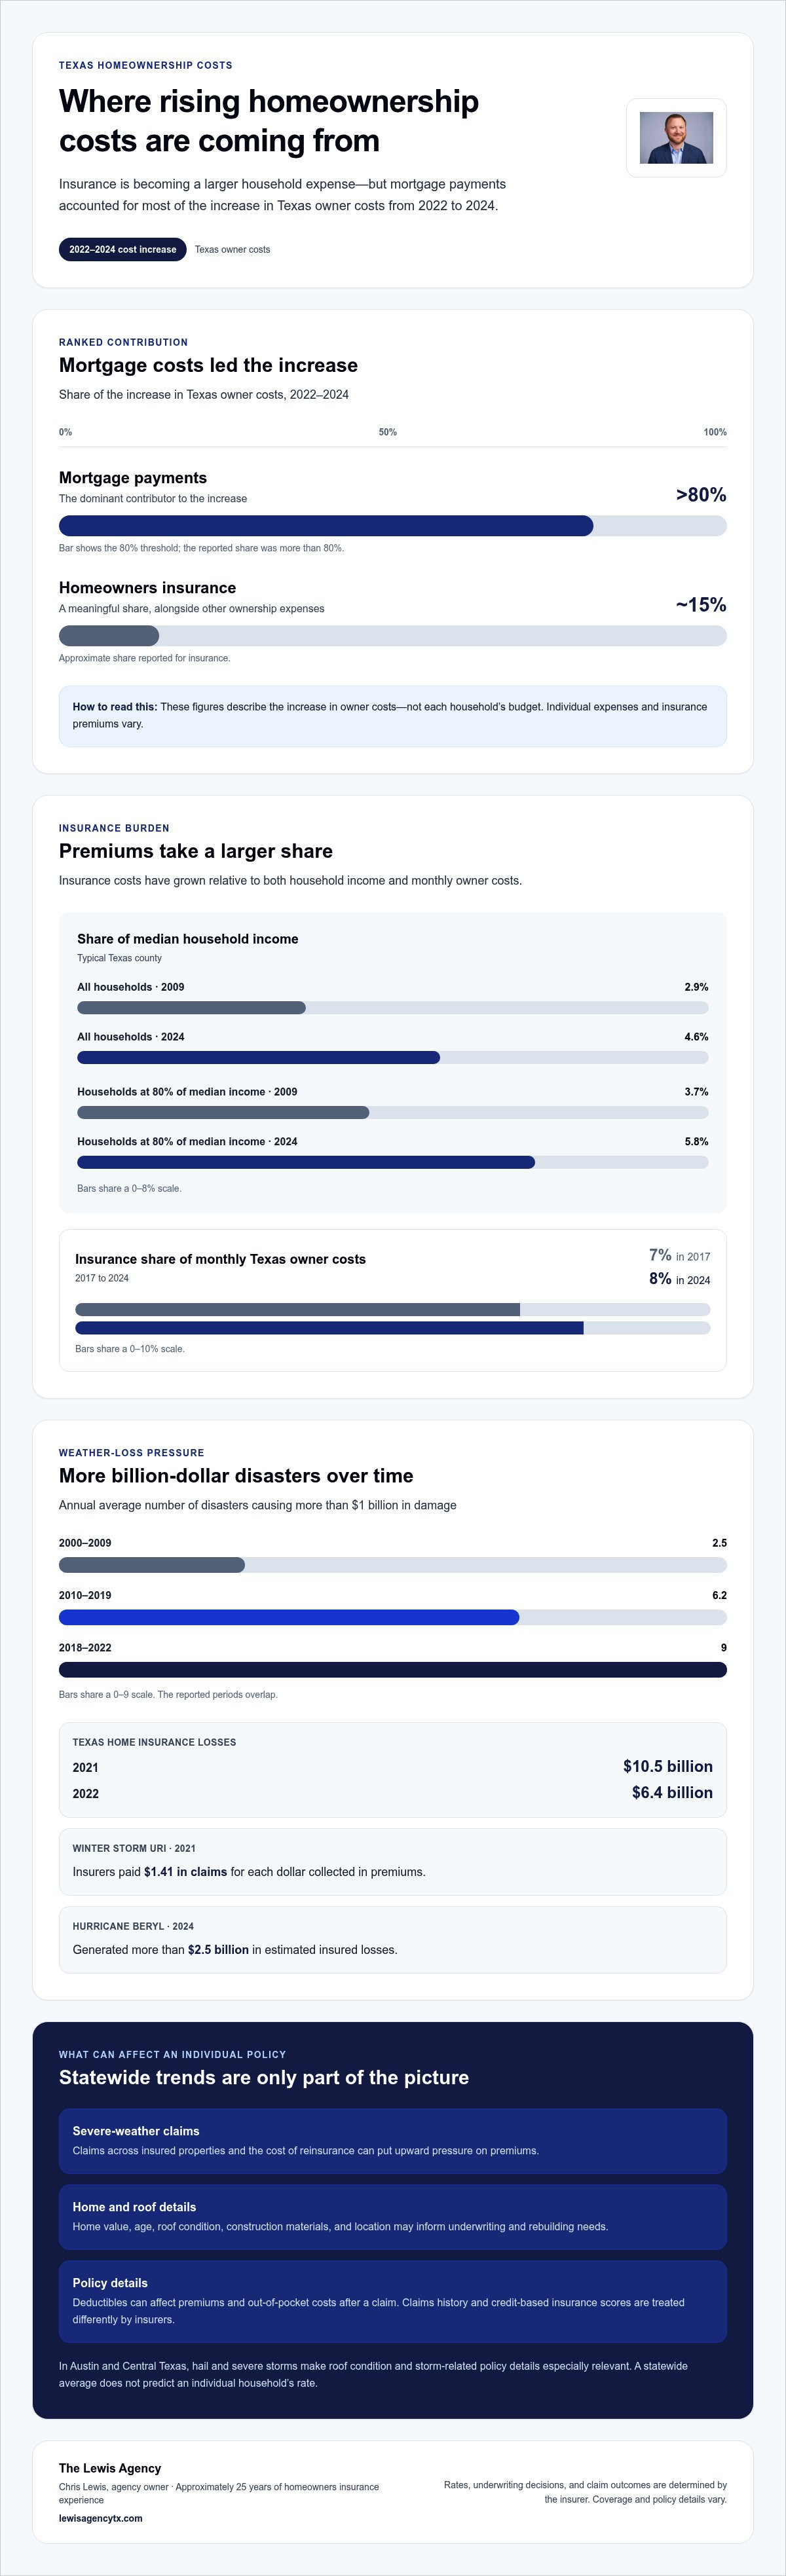
Texas weather losses can affect insurance premiums beyond the homes directly damaged. The state averaged 2.5 disasters causing more than a billion dollars in damage annually from 2000 to 2009. That average rose to 6.2 during 2010 to 2019, then 9 from 2018 to 2022. These trends help explain why Texas homeowners insurance costs increase: insurers account for claims across the properties they insure, not only damage to one home.
The losses can be substantial. Texas home insurance losses totaled $10.5 billion in 2021 and $6.4 billion in 2022. Winter Storm Uri added strain: in 2021, insurers paid $1.41 in claims for each dollar collected in premiums. In 2024, Hurricane Beryl generated more than $2.5 billion in estimated insured losses. These events show how severe weather can affect claim payments and future pricing. They also help explain why Texas homeowners insurance costs increase even for households without a recent claim.
Reinsurance is another cost factor. Insurers may buy it to help manage large losses, and its cost can influence the rates they seek. Storm claims and reinsurance costs can both put pressure on premiums, although each homeowner’s renewal also depends on the property and policy. In Austin and Central Texas, hail and severe storms make roof condition and policy details especially relevant when assessing a home’s exposure.
For a practical review, note your roof’s age, any storm repairs, and the deductible shown in your policy. The Homeowners Resource Center can help you prepare questions about storm damage and coverage. Understanding how a policy addresses losses helps connect statewide weather trends with the protection your household has chosen.
Texas homeowners insurance costs as a share of ownership expenses
Insurance premiums take a larger share of household income than they did in 2009. In a typical Texas county, premiums consumed 4.6% of median household income in 2024, compared with 2.9% in 2009. For households earning 80% of median income, the share rose from 3.7% to 5.8%. These comparisons show how premiums can tighten an already stretched housing budget, even when other expenses remain unchanged.
Insurance is one part of ownership costs, not the whole increase. It represented around 8% of monthly Texas owner costs in 2024, up from 7% in 2017. From 2022 to 2024, insurance accounted for roughly 15% of the increase in owner costs, while mortgage payments accounted for more than 80%. That context helps households assess premiums alongside their mortgage and other regular expenses.
Which Texas cities and regions have the highest homeowners insurance costs, and why? Costs vary by county, reflecting differences in properties and risks. In Austin and nearby Central Texas communities, a home’s location, construction, and coverage details can affect its premium. Statewide averages do not predict an individual household’s rate.
To manage costs, review your home details and compare quotes using similar coverage limits, exclusions, and deductibles. The Texas Department of Insurance explains that higher deductibles lower premiums but increase what you pay out of pocket after a claim. Check whether dwelling coverage reflects rebuilding needs, then weigh deductible costs against your budget. A homeowners policy review can help you identify details to discuss and compare.
The Lewis Agency: Homeowners Insurance Policies
The Lewis Agency helps Central Texas homeowners understand their homeowners policies, including how coverage, exclusions, and deductibles relate to their homes and budgets. The agency provides plain-English guidance on policy language, coverage, and the claims process. Rates, underwriting decisions, and claim outcomes are determined by the insurer.
Consider reviewing your policy after a renewal change, roof update, or home renovation. Have your declarations page handy and note questions about dwelling coverage, storm-related deductibles, and household expenses. A review can clarify your current policy and help you identify details to consider when requesting a quote.
For questions about your homeowners coverage, contact The Lewis Agency.
Make your next policy review more useful
Understanding why Texas homeowners insurance costs increase can help you approach your next renewal with clearer questions. Before reviewing your policy, note changes to your home, recent repairs, and your household budget. Then consider whether the coverage details and deductibles still suit your circumstances.
The Lewis Agency offers Homeowners Insurance Policies, Auto Insurance, and Landlords Insurance. You can ask questions about policy language and discuss how your coverage fits your needs. A thoughtful review won’t control rates or claim decisions, but it can help you understand what your policy says and what to consider next.
Contact The Lewis Agency to discuss your homeowners coverage. Taking time to understand your policy is a practical step toward making informed decisions about your home.
Frequently Asked Questions
What factors are driving homeowners insurance costs up in Texas?
An individual household’s premium reflects details about the property and the policy selected. To understand a change, compare your renewal with the prior policy: check the home information, coverage amounts, deductibles, endorsements, and exclusions. Updating outdated property details and identifying what changed can make a renewal easier to evaluate.
How do hail, hurricanes, tornadoes, and severe storms affect Texas insurance premiums?
Storms can damage different parts of a home, so review the policy language for wind, hail, and water damage. Check whether it lists a separate deductible or excludes a particular cause of loss. After a storm, document visible damage and keep repair records to support a claim discussion under your policy.
How have rising construction and labor costs changed Texas homeowners insurance prices?
Higher material and labor costs can make an older reconstruction estimate less useful when planning for repairs after a major loss. Keep records of renovations, additions, and major material changes, then review whether your dwelling coverage reflects the home’s current rebuilding needs. Market value and rebuilding cost are different measures, so one should not automatically stand in for the other.
What role do reinsurance costs and insurer losses play in Texas premium increases?
Reinsurance is insurance that an insurance company purchases to help manage its exposure to large losses. Its cost and the insurer’s loss experience can inform broader pricing decisions, but neither determines one household’s premium by itself. For your renewal, focus on the terms and property details in your documents rather than assuming a statewide trend explains every change.
What rules does the Texas Department of Insurance have for rate increases and policyholder notices?
The Texas Department of Insurance reviews rate filings under state standards. Texas permits insurers to apply rate changes before official approval, subject to possible disapproval by the insurance commissioner. For your renewal, read the insurer’s notice for the new premium, effective date, and policy changes. Ask the insurer to clarify anything the notice does not explain.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.
Detached Garage and Outbuilding Coverage in Texas
Learn how detached garage and outbuilding insurance coverage in Texas may apply to structures and belongings, and how exclusions and deductibles affect claims.
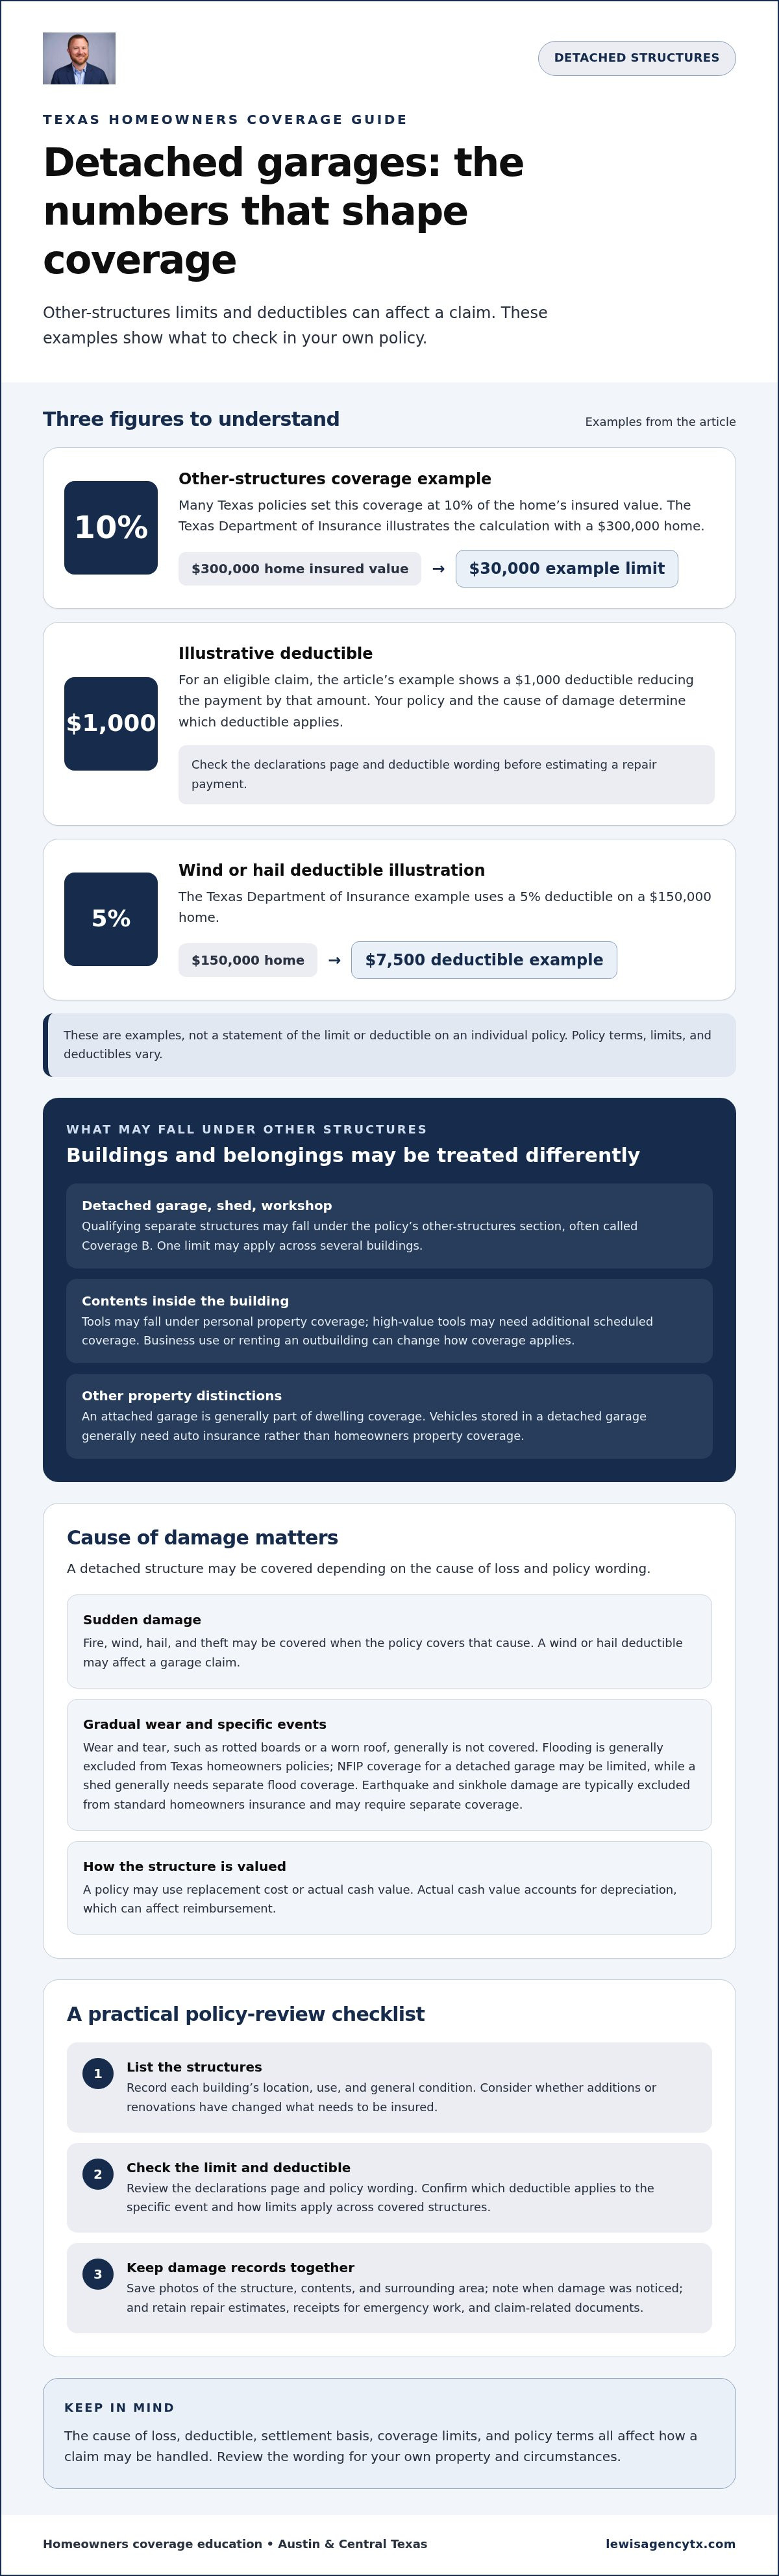
A detached garage may be covered under the other-structures portion of a homeowners policy, but the deductible can affect what a claim pays. Many Texas policies set this coverage at 10% of the home’s insured value. In its example, the Texas Department of Insurance shows that a home insured for $300,000 may have $30,000 in other-structures coverage, and it says most home policies include a deductible for this coverage.
It’s reasonable to expect a garage or shed to be treated differently from the house itself. Understanding detached garage and outbuilding insurance coverage in Texas means knowing which structures and belongings may be covered, what exclusions may apply, and how the deductible affects a claim. Here’s how to review the coverage, including why damage to a detached building may be subject to the same deductible as other covered property.
Key Takeaways
- List detached garages, sheds, and other buildings on your property, then consider whether renovations or additions have changed what needs to be insured.
- Separate sudden damage from gradual wear and understand how flooding and earthquake damage may be treated differently.
- Before filing a garage claim, identify the cause of damage and the deductible that applies to that loss.
- Remember that a building and the tools or other belongings inside it may fall under different parts of a homeowners policy.
Does Homeowners Insurance Cover a Shed?
Detached garage and outbuilding insurance coverage in Texas usually falls under the policy’s other-structures section, often called Coverage B. Whether a shed qualifies, and how much protection applies, depends on the policy wording, limits, and deductible.
Other Structures Coverage Limits
Coverage B refers to protection for qualifying structures separate from the dwelling. The Texas Department of Insurance gives an example of a home insured for $300,000 with $30,000 in other-structures coverage, or 10% of the home’s insured value. Use your declarations page to find the limit that applies to your own policy.
After adding a shed or enlarging a garage, review whether the listed limit still fits the buildings on your property. Ask the insurer about increasing it, then keep the updated policy documents with your home records.
Shared Limits Across Outbuildings
One other-structures limit may apply across several buildings, such as a garage, shed, and workshop. That matters when estimating whether the available amount could address damage to more than one structure. Make a property list that records each building’s location, use, and general condition.
Use that inventory when reviewing your policy wording and declarations page. Flood damage generally falls outside homeowners insurance. Under the National Flood Insurance Program, coverage for a detached garage may be limited, while a shed generally needs separate flood coverage.
Documenting a Detached Structure Claim
For a damage claim, keep photographs of the structure, affected contents, and surrounding area. Record when you noticed the damage and save receipts for emergency work or repairs. A dated record helps you describe the loss consistently.
Keep repair estimates and a list of damaged belongings with those images. Review the declarations page for the applicable deductible, and retain copies of claim-related documents. These records can help you explain the damage and keep claim details organized.
Is A Detached Garage Covered Under Your Homeowners Policy?
A detached garage may be covered as an other structure, but the cause of damage and policy terms matter. Flooding, earthquakes, business use, and gradual deterioration may be treated differently from sudden covered damage.
Covered Perils for Detached Buildings
Fire, wind, hail, and theft may be covered when the policy covers that cause of loss. For hail damage to a garage, the applicable wind and hail deductible may affect a claim. Wear and tear, such as rotted boards or a worn roof, develops over time and generally isn’t covered.
Flood damage is generally excluded from Texas homeowners policies. National Flood Insurance Program coverage for a detached garage may be limited, while a shed generally needs separate flood coverage. Earthquake and sinkhole damage are typically excluded from standard homeowners insurance and may require separate coverage.
For a damaged structure, the policy may value it at replacement cost or actual cash value. Actual cash value accounts for depreciation, so the valuation method can affect reimbursement.
Business Use and Stored Property Exclusions
Using an outbuilding for business or renting it can change how coverage applies. Business property or use may be limited under homeowners insurance, so review the policy terms for the building and its contents. Tools inside a garage may fall under personal property coverage, while high-value tools may need additional scheduled coverage.
Vehicles stored in a detached garage generally need auto insurance, not homeowners property coverage. Equipment breakdown may also matter: a garage-door opener’s mechanical failure or wiring may not be covered without that protection. For a policy wording review, explore these homeowners insurance resources.
Deductibles for detached garage claims
A detached garage claim may use the homeowners policy’s deductible rather than a separate deductible for the building. The Texas Department of Insurance says most home policies include a deductible for other-structures coverage. A policy may apply the dwelling deductible unless its terms say otherwise, so read the declarations page and deductible wording before estimating a repair payment.
The deductible amount depends on the policy and the covered cause of damage. For example, a $1,000 deductible would reduce the payment for an eligible claim by that amount. Windstorm or hail damage may involve a percentage deductible instead. The Texas Department of Insurance illustrates a 5% deductible on a $150,000 home, which equals $7,500. That example shows why the deductible type matters before deciding whether to file.
Check which deductible applies to the specific event, then compare it with the estimated repair or replacement amount. A shared deductible can affect a detached garage and other structures covered under the same policy. Attached garages are generally part of dwelling coverage, while fences may fall under other-structures terms. A separate policy may apply to flood damage, so don’t assume the homeowners deductible governs every loss.
Keep the declarations page, damage photos, and repair estimate together when discussing a claim. Ask how the policy applies its deductible and coverage limits to the damaged structure. The deductible is not the only factor: the cause of loss, settlement basis, and policy terms also affect payment. For help understanding the wording, ask a homeowners coverage question.
The Lewis Agency: Homeowners Insurance Policies
The Lewis Agency can help homeowners understand how their policy addresses a detached garage, shed, or other outbuilding. As an Allstate agency, it can explain policy language, review coverage limits and deductibles, and help you understand the claims process. Coverage decisions remain with the insurer, and the policy terms determine how a particular loss is handled.
A policy review can be useful after adding a structure, changing how you use one, or finding that its limit or deductible is unclear. Focus the discussion on your homeowners policy and the details that matter to your property, rather than assuming every outbuilding has the same coverage. The Lewis Agency also offers auto, landlords, and condo insurance policies.
For help understanding your homeowners policy, contact The Lewis Agency with your coverage questions.
Make Your Next Coverage Review Count
A new structure, renovation, or change in how you use a garage can shift what you need to discuss at your next policy review. Keep a current record of outbuildings and their uses, then bring any questions about limits or deductibles to the conversation. A review of detached garage and outbuilding insurance coverage in Texas can help you understand how your policy’s wording applies to the property you have now. Because coverage depends on the policy, reviewing its terms with an insurance professional can clarify what to consider next.
Contact The Lewis Agency to discuss your homeowners coverage and questions about your property. A clear next step can make it easier to plan ahead with confidence.
Frequently Asked Questions
Home insurance: What structures are covered?
Home insurance may include structures on the residence premises that meet the policy’s definitions. For a less common feature, such as a built-in swimming pool, classification can depend on the insurer and policy wording. Check the declarations and definitions to see how the feature is categorized, especially if it’s part of a larger outdoor area or construction project.
What Counts as a Detached Structure?
A detached structure stands apart from the main home rather than forming part of its construction. For a borderline feature, note whether it shares a wall or roof with the house, and describe any connecting walkway or enclosure. Those details can help clarify how the policy classifies it, especially when additions change the property’s layout.
What about the things stored inside the shed?
Items stored in a shed are considered separately from the building itself. To prepare, keep a current inventory with descriptions, photographs, and receipts for belongings you may need to identify later. Record valuable equipment individually, since a policy may apply special limits or require additional coverage for certain items.
What types of damage does it pay for?
Coverage depends on the event that caused the loss and the policy’s terms. For example, a claim involving a fallen tree may require details about what fell, where it landed, and the resulting damage. Keep maintenance records and dated photographs of the structure’s condition; they can help distinguish a sudden event from deterioration that developed over time.
Does Texas homeowners insurance cover a detached garage or other outbuilding?
A detached garage or outbuilding may be covered, but construction status and use can affect how the policy applies. If you’re building a new garage, review how coverage applies during construction; a builders risk policy may be more suitable for that stage. Also review your policy if you rent the structure or use it for business.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.
Water Backup Endorsements in Round Rock and Their Cost
Learn what a water backup endorsement for Round Rock homeowners covers, how sump pump overflows are handled, and what influences endorsement coverage costs.
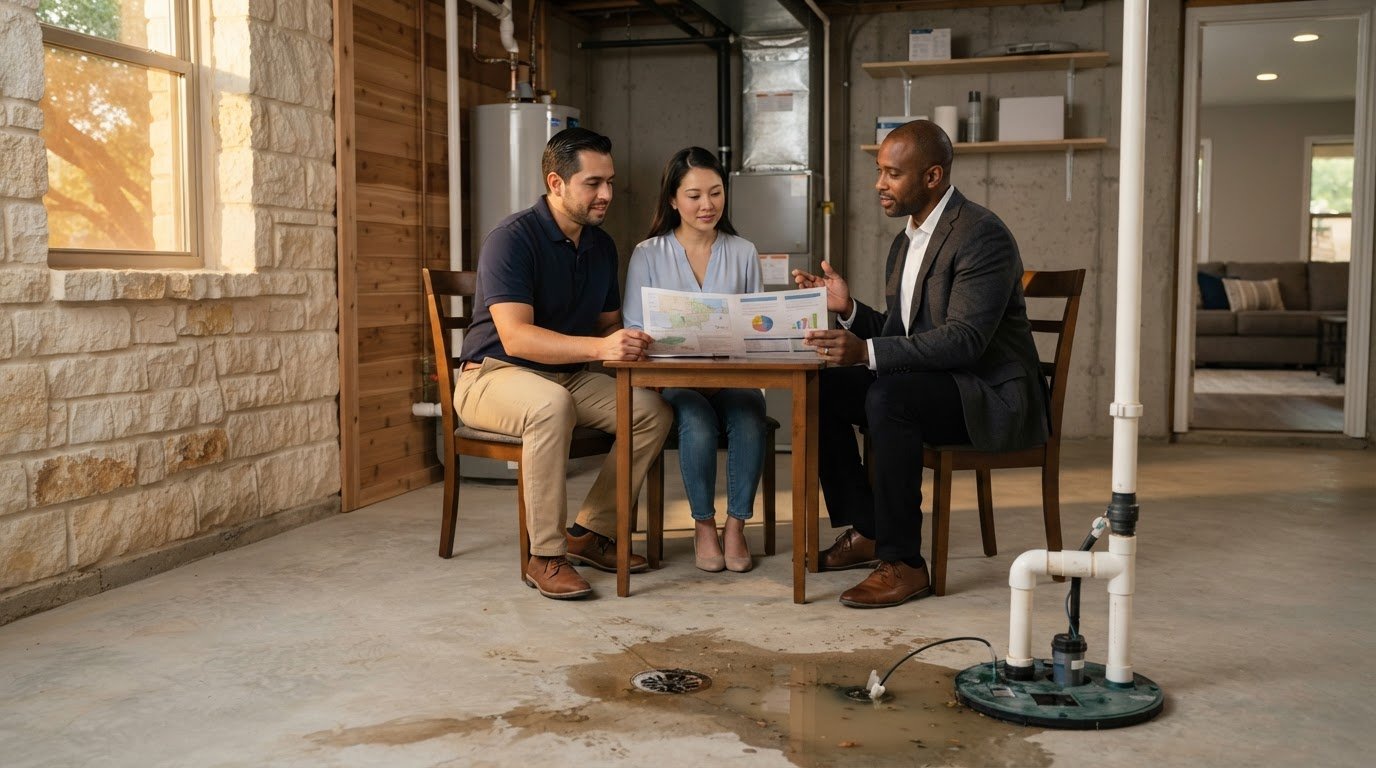
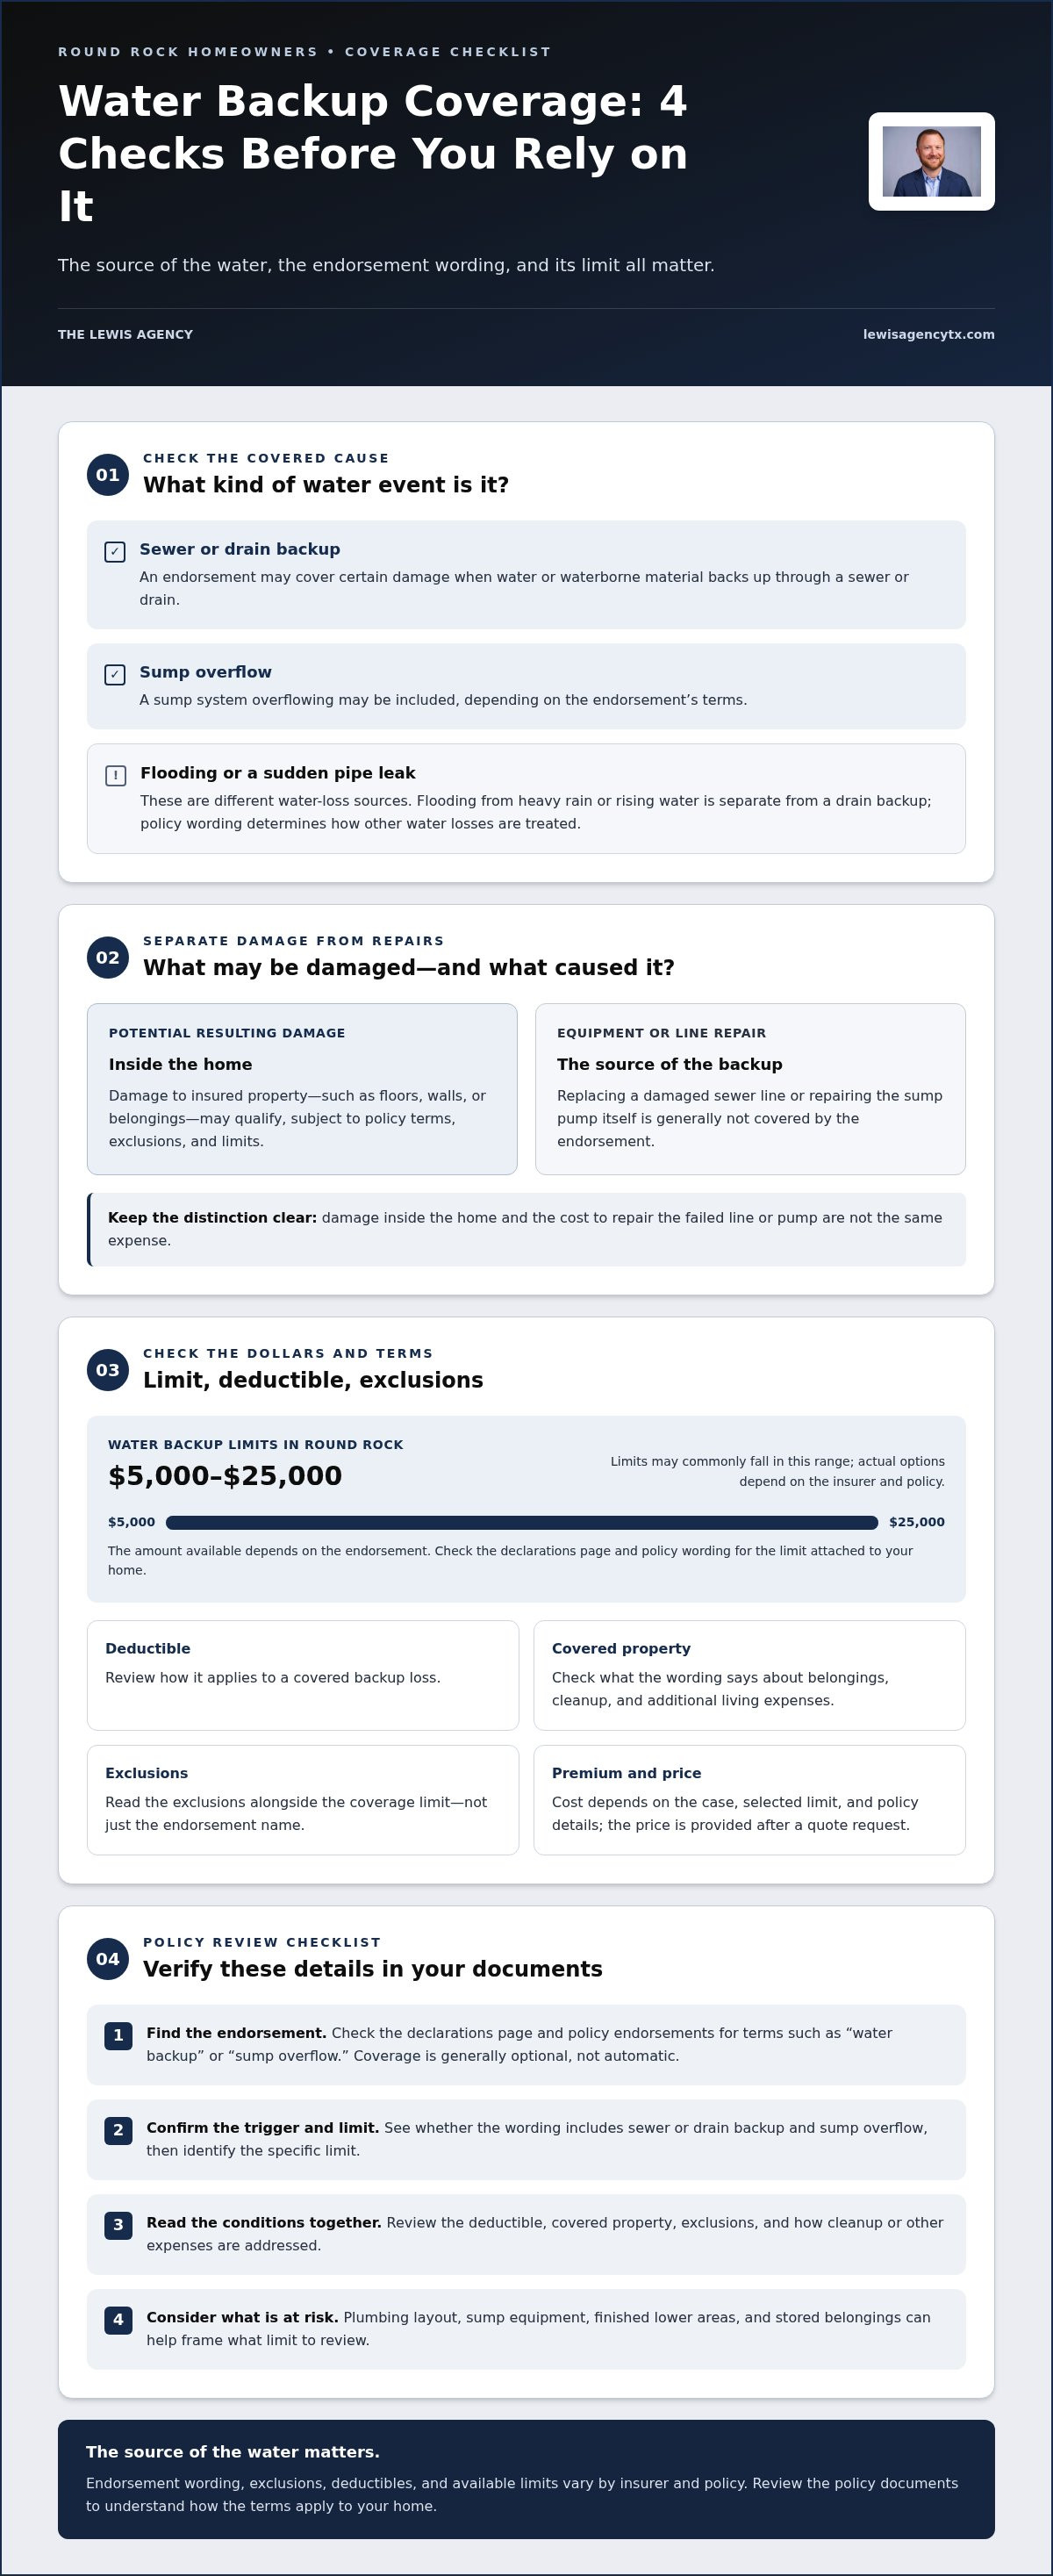
For Round Rock homeowners, a water backup endorsement may cover certain damage when water or sewage backs up through a sewer or drain, or overflows from a sump system. It may help pay for damage to the home and belongings, but generally won’t cover replacing a damaged sewer line or repairing the sump pump itself. Cost and limits depend on the policy.
The source of the water matters because homeowners insurance can treat different losses differently. This article explains what backup coverage may protect, what can affect its cost, how damage to a sump pump differs from damage caused by pump failure, and how to add an endorsement to a policy. It also explains how backup damage differs from flooding and sudden pipe leaks.
Key Takeaways
- Water backup coverage may help with damage from sewer or drain backups and sump overflows, but it doesn’t cover every water loss.
- Look closely at exclusions, coverage limits, and deductibles to understand how an endorsement could respond to a backup.
- Damage caused by a sump pump overflow is different from damage to the pump itself, which may not be covered.
- The source of the water matters: backup damage, flooding, and a sudden burst pipe can be treated differently under a homeowners policy.
- Review your policy’s endorsement options and wording to understand how to add coverage that fits your home.
What Is Water Backup and Do You Need Water Backup Coverage?
For Round Rock homeowners, a water backup endorsement may cover certain damage from backed-up drains or overflowing sump systems. Whether it fits your home depends on the policy wording, your plumbing, and the coverage limits you choose.
Water backup coverage is generally optional, not automatic. Its place in a homeowners policy is separate from any conditions in a mortgage agreement, so review your policy and loan documents for their respective terms.
Water Backup and Sump Overflow Coverage
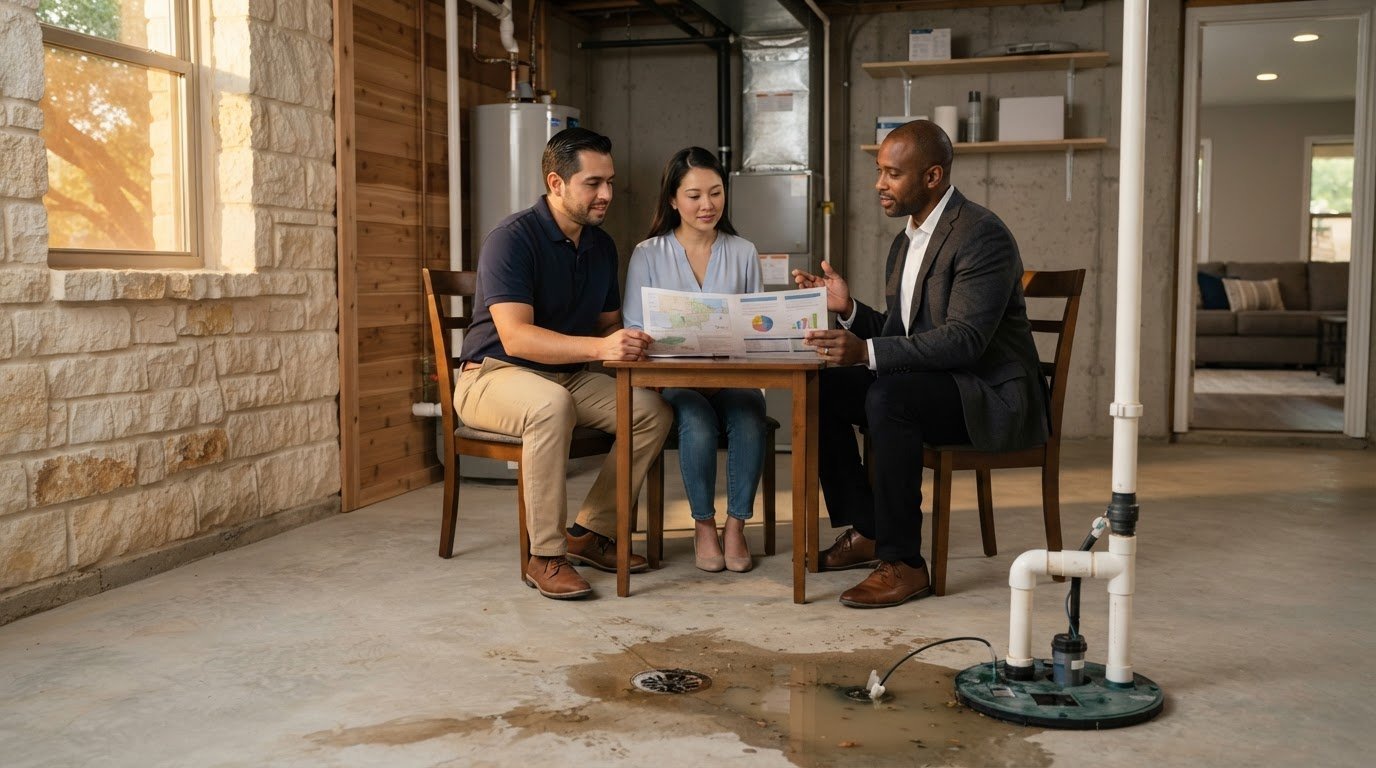
A water backup and sump overflow endorsement may cover damage to insured property when water or waterborne material backs up through a sewer or drain, or overflows from a sump. This can matter when contaminated water reaches floors, walls, or belongings before you can stop it.
Examples include sewage backing up through a basement drain, a clogged drain causing a toilet overflow, or a sump pump system overflowing. Some limits commonly start at $5,000, but the amount available depends on the endorsement. Check whether the stated limit fits the property and cleanup costs you could face.
Coverage Exclusions
A water backup endorsement doesn’t cover every water-related loss. Flooding and damage to the failed pump or sewer line itself are common exclusions. Resulting damage inside the home isn’t the same as the cost of replacing the equipment or line that caused it.
Flooding from heavy rain, an overflowing river, or a tidal surge is different from water backing up through a drain. A separate flood policy may be relevant to flood risks. Endorsement wording also determines how exclusions apply, including whether damage to personal belongings or additional living expenses may qualify.
For example, if a sewer backup damages flooring and the sewer line also needs replacement, the endorsement may cover the indoor damage but not the line repair. Read the policy’s definitions, exclusions, and limit together rather than relying on the endorsement’s name alone.
Coverage in Homeowners Policies
Homeowners insurance doesn’t automatically include water backup coverage in every policy. You may need to add an endorsement, and available limits and terms depend on the insurer and policy.
Check the declarations page and endorsements for terms such as “water backup” or “sump overflow.” Then review the limit, deductible, covered property, and exclusions in the policy wording. If the endorsement isn’t listed, don’t assume a drain backup is covered just because you have homeowners insurance.
Is sinkhole coverage relevant when buying a home? Review it separately from water backup coverage. Sinkhole coverage concerns sudden land collapse; gradual settling or erosion may not meet that description. It addresses a different cause of property damage, so its presence doesn’t tell you whether drain backups are covered.
A Round Rock homeowner can weigh the home’s plumbing layout, sump equipment, and belongings in lower areas when considering limits. Older pipes, nearby trees, or a community sewer system may also make the policy wording worth reviewing. The key question is whether the endorsement’s covered causes and limit match the risks around your home.
What Is a Sewer Backup Endorsement and What Does It Cost?
A sewer backup endorsement may add protection for covered damage when wastewater backs up through a sewer or drain. Its terms matter because a backup, a flood, and a damaged buried sewer line can involve different coverage.
Coverage options and limits vary by insurer and policy, so compare the endorsement wording, covered causes, exclusions, and deductible. The endorsement’s price depends on the case and is given after a quote request; factors include the selected limit and policy details.
Sewer and Drain Backup Exclusions
A sewer backup endorsement may cover damage to insured property from water backing up through a sewer or drain, but it won’t necessarily cover every related repair. This matters if the backup damages furniture while a buried sewer lateral also needs replacement.
Flooding from heavy rain or rising water is a separate cause of damage and generally falls outside water backup coverage. The endorsement may also exclude the cost of repairing or replacing the underground sewer line itself. Review both exclusions before assuming one limit applies to cleanup, belongings, and pipe repairs.
Comparing Water Backup Coverage
Texas homeowners insurers can differ in endorsement wording, available limits, deductibles, and how they treat covered property. Comparing the policy documents directly is more useful than comparing endorsement names alone.
Check whether the terms cover water or waterborne material backing up through drains and whether they include sump overflows. Review how the deductible applies and what the policy says about cleanup, damaged belongings, and additional living expenses. These details affect what you may be responsible for after a sewer backup.
To understand the cost, consider the selected coverage limit and policy terms alongside the premium quoted for your home. A lower limit may leave you responsible for more of a large loss, while a higher limit means purchasing more coverage.
Available Coverage Limits in Round Rock
Round Rock homeowners may find water backup limits commonly ranging from $5,000 to $25,000. The actual options depend on the insurer and policy, so use the declarations page and endorsement wording to identify the limit attached to your home.
Consider what could be affected by a backup, including flooring, finished rooms, stored belongings, and cleanup needs. A hypothetical loss affecting a finished lower level could involve several types of property, while a smaller event might affect only one room. Match the limit to the areas and belongings at risk, then consider the deductible separately.
Prevention can reduce some causes of a sewer backup, although it can’t change policy exclusions. Flush only toilet paper, and put cooled cooking grease in the garbage rather than down the drain. Roots can enter cracks in sewer lines and trap debris, so a camera inspection can help identify concerns before a blockage worsens. A backwater prevention valve in lower-level drains may also help keep sewage from flowing back into the home.
If repeated backups or slow drains raise questions about your policy, a homeowners policy review can help clarify how the endorsement and its limits apply.
Sump pump failure and overflow
A sump pump moves water away from a foundation, but mechanical failure or a power outage can stop it from working. If water then overflows from the sump and damages insured property, a water backup and sump overflow endorsement may apply. The pump itself and related equipment are treated differently from the resulting water damage.
Picture a sump pump failing during a storm, allowing water to spread across a finished room. The endorsement may cover eligible damage to flooring, walls, or belongings, subject to its terms and limit. In an illustrative example, a $15,000 sump pump damage claim has a $10,000 coverage limit and a $1,000 deductible. The limit and deductible affect the amount available for covered damage; the example doesn’t promise a particular claim payment.
Pay close attention to power failure wording. A pump can stop because of mechanical breakdown, a power outage, or water overwhelming the system. The endorsement determines whether resulting damage is covered when the pump fails or overflows. A battery backup sump pump may help keep water moving during an outage, but it doesn’t change policy exclusions or guarantee coverage.
Keep the equipment and surrounding drainage system in working order. Follow the pump manufacturer’s maintenance guidance, keep the sump area clear, and check that the discharge path isn’t blocked. Look for slow flow or gurgling in nearby drains, which can signal a developing blockage. If your home has a basement or lower-level rooms, avoid storing belongings where water could collect.
A backwater prevention valve in lower-level drains can help limit sewage flowing back into a home. It serves a different purpose from a sump pump: the valve helps restrict reverse flow through drains, while the pump moves subsurface water away from the foundation. Both systems need attention, and neither replaces insurance coverage for an insured loss.
Standard homeowners coverage and endorsements don’t treat every water event alike. A sudden pipe burst differs from water backing up through a drain or sump. The endorsement’s definitions and exclusions explain how it handles water caused by pump failure, including whether damage to the pump itself is excluded. Read those details alongside the stated limit before deciding whether the protection fits your home.
For Round Rock homeowners, consider the sump’s location, what’s nearby, and whether a power loss could interrupt pumping. Keep a record of maintenance and note any recurring overflow or drainage problems. These practical details help clarify the role of the endorsement and identify questions about the policy wording before a water problem occurs.
Separating backup damage from other water damage
The source of water helps determine which part of a homeowners policy may apply. A drain backup, a sudden pipe burst, and flooding can all damage a home, but they are different events. For Round Rock homeowners, identifying where the water came from is a practical first step when describing a loss and reviewing the relevant policy language.
Water backup coverage may apply when water or sewage pushes through a sewer or drain into the home. A sudden pipe burst is different: homeowners insurance typically covers damage from a pipe that suddenly bursts, subject to the policy’s terms. Flooding from heavy rain or rising water is another category, and a water backup endorsement generally doesn’t cover flood damage.
The difference can matter even in the same room. If a pipe bursts behind a wall, water may damage drywall, flooring, and furniture. If a sewer backs up through a floor drain, the endorsement may cover resulting damage to insured property. If outside floodwater enters that room, the backup endorsement isn’t designed to cover that cause.
Covered property can include the home’s structure and, depending on the policy, personal belongings. For example, contaminated water could damage flooring, electrical systems, walls, or furniture. This illustrates how property can be affected, but the policy wording determines how a specific loss is handled.
The cause of the water and the source of the damage also matter for buried pipes. Tree roots can enter cracks in sewer lines and collect debris, eventually contributing to a blockage or backup. An endorsement may cover resulting indoor damage, while the cost of repairing or replacing the buried sewer lateral may fall outside its coverage. Separate terms can apply to underground service lines.
Cleanup is another part of the loss to consider. Removing standing water and drying affected materials promptly can help limit ongoing damage and mold growth. Water backup cleanup and drying takes an average of 3.5 days. During cleanup, keep records of affected rooms and belongings, and photograph visible damage before removing damaged items when it is safe to do so.
When reporting water damage, describe what happened plainly: where the water first appeared, whether a pipe broke, and whether water came through a drain. Keep receipts for emergency work and list damaged property, such as furniture or appliances. Those details help distinguish backup damage from other water problems and make it easier to find the relevant policy provisions.
Adding an endorsement to a homeowners policy
Start by reviewing your current homeowners policy. Find the declarations page and endorsement schedule, then look for water backup or sump overflow wording. If it isn’t included, ask the insurer about adding an endorsement. The policy documents should show the selected limit, deductible, premium, and effective date.
Before choosing a limit, consider which parts of the home could be affected. A basement or lower-level room may hold furniture, stored belongings, or household equipment. Think through how a sewage backup could affect those items and the surrounding building materials. Choose an amount that reflects the potential covered loss rather than simply selecting the lowest available option.
Read the endorsement itself rather than relying on a short description. Check how it defines backup, which drains or sump systems it addresses, and whether it covers damage to personal property. Look for exclusions involving floods, the pump itself, or buried sewer lines. The deductible and limit matter too: they shape how much of a covered loss could remain your responsibility.
Ask for the proposed change in writing. Review the updated policy documents after the endorsement is added and confirm that the stated limit matches your selection. Keep the documents with your other home records, including a note of the effective date. If comparing options, use the same questions for each version of the endorsement so the differences are clear.
Timing matters, too. Discuss the change before a water problem occurs, since the endorsement’s effective date determines when its terms apply. Don’t assume that requesting a change means coverage begins immediately. Confirm the date shown in the updated documents, then save a copy where you can find it during an emergency.
For example, a Round Rock homeowner with a basement might list the belongings stored there, note nearby drains, and review the policy’s exclusions. This inventory helps clarify what the selected limit is intended to cover. It also separates water backup concerns from flood risks or repairs to the sewer line itself, which may involve different coverage.
Once you’ve reviewed the wording, write down any remaining questions about the limit, deductible, exclusions, or effective date. A focused policy discussion can clarify how the endorsement fits the homeowners coverage already in place. Review your homeowners coverage and ask for help understanding the endorsement language.
The Lewis Agency: Homeowners Insurance Policies
The Lewis Agency is an Allstate agency that helps homeowners understand their homeowners insurance policies, including water backup endorsements. If you’re unsure how your policy addresses sewer backups, sump overflows, limits, or exclusions, the agency can help explain the relevant wording and claims process.
Bring your declarations page and endorsement documents to a policy discussion. Reviewing them can help you identify the listed coverage, applicable deductible, and questions about damage to your home or belongings. Coverage and claim decisions depend on the policy and individual circumstances.
If you’d like help understanding your homeowners coverage, contact The Lewis Agency or visit lewisagencytx.com.
Make your next policy review count
A home changes over time, and insurance questions can change with it. A finished basement, new storage habits, or plumbing work may shape what you want to review. Keep a short note of home changes for your next policy conversation. It’s a practical starting point for discussing whether a water backup endorsement for Round Rock homeowners fits your needs.
Use that review to consider how the endorsement fits with the rest of your policy. The Lewis Agency offers homeowners insurance policies, auto insurance, and landlords insurance. Coverage terms and claim decisions depend on the policy and circumstances.
Contact The Lewis Agency to discuss your homeowners coverage. A clear review can help you move forward with greater understanding and confidence.
Frequently Asked Questions
Does homeowners insurance cover sewer line replacement?
Homeowners insurance typically doesn’t cover replacing an underground sewer line simply because it’s damaged or worn. A backup endorsement may cover resulting damage inside the home, while service-line coverage, if included, may cover the buried line itself. For example, if a blockage damages indoor flooring and the lateral also needs repair, those costs may fall under different policy terms. Check each coverage section separately.
How Do You Get Ahead of a Sewer Backup Problem Before It Happens?
Reduce common blockage risks by flushing only toilet paper and putting cooled cooking grease in the garbage. Watch for slow drains, gurgling pipes, sewage odors, or recurring issues, and address them before they worsen. A camera inspection can help reveal obstructions or root intrusion in a sewer line. Keeping notes on repeated drainage problems also gives you useful details for a plumber and for understanding your property’s risk.
How do I know if my sewer line is at risk?
Repeated slow drains, gurgling, sewage odors, or water pooling near a cleanout can point to a sewer-line problem. Trees or shrubs nearby may matter because roots can enter cracks and trap debris. If symptoms recur or several fixtures drain poorly at once, a camera inspection can help identify the issue. For a Round Rock home, note when problems occur and which drains are affected.
How does the deductible interact with the limit?
The deductible is the amount applied to a covered loss, while the limit caps the amount available under the endorsement. For example, with a covered loss of $10,000, a $1,000 deductible, and a $10,000 limit, an illustrative calculation leaves $9,000 after the deductible. Policy wording determines how the deductible is applied, so read that section before estimating your share.
What should not be charged against the backup limit?
Don’t assume costs excluded by the endorsement are covered within its backup limit. Sewer-line replacement and repair of the failed sump pump itself may fall outside water backup coverage. Flood damage is a separate cause as well. Keep invoices itemized so cleanup, damaged building materials, personal belongings, and excluded equipment or line work are distinguishable during a claim review.
What does a water backup endorsement cover on a homeowners policy?
A water backup endorsement may cover damage to insured property when water or waterborne material backs up through a sewer or drain, or overflows from a sump. Depending on the policy, insured property may include parts of the home and personal belongings. For instance, a backup affecting a laundry room could damage flooring and stored items. The endorsement’s wording and limit determine what applies.
Does a water backup endorsement cover sewer backup and sump pump overflow?
It may cover both if the endorsement’s terms include sewer or drain backups and sump overflow. The cause and resulting damage matter: sewage entering through a floor drain differs from rainwater entering through an exterior opening. Check the endorsement’s definitions, exclusions, deductible, and limit. A broken pump may be treated differently from water damage caused by its failure.
What is excluded from water backup coverage, including flooding and gradual leaks?
Flooding from heavy rain or rising rivers is generally separate from water backing up through a drain, so a backup endorsement isn’t designed for flood damage. Gradual seepage or a slow leak also differs from a sudden drain backup, and its treatment depends on the policy wording and circumstances. Review exclusions for the specific source of water rather than assuming every indoor water loss fits the endorsement.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.
Why Do Texas Insurance Rates Keep Increasing? A Homeowners’ Guide
Wondering why do Texas insurance rates keep increasing? Explore the key factors driving higher premiums and learn what to review before changing your policy.
What if your renewal increase has less to do with one change to your home and more to do with several costs rising at once? You may be asking, why do Texas insurance rates keep increasing? A higher premium can feel abrupt, especially when the renewal notice doesn’t show how broader market pressures and details about your home fit together.
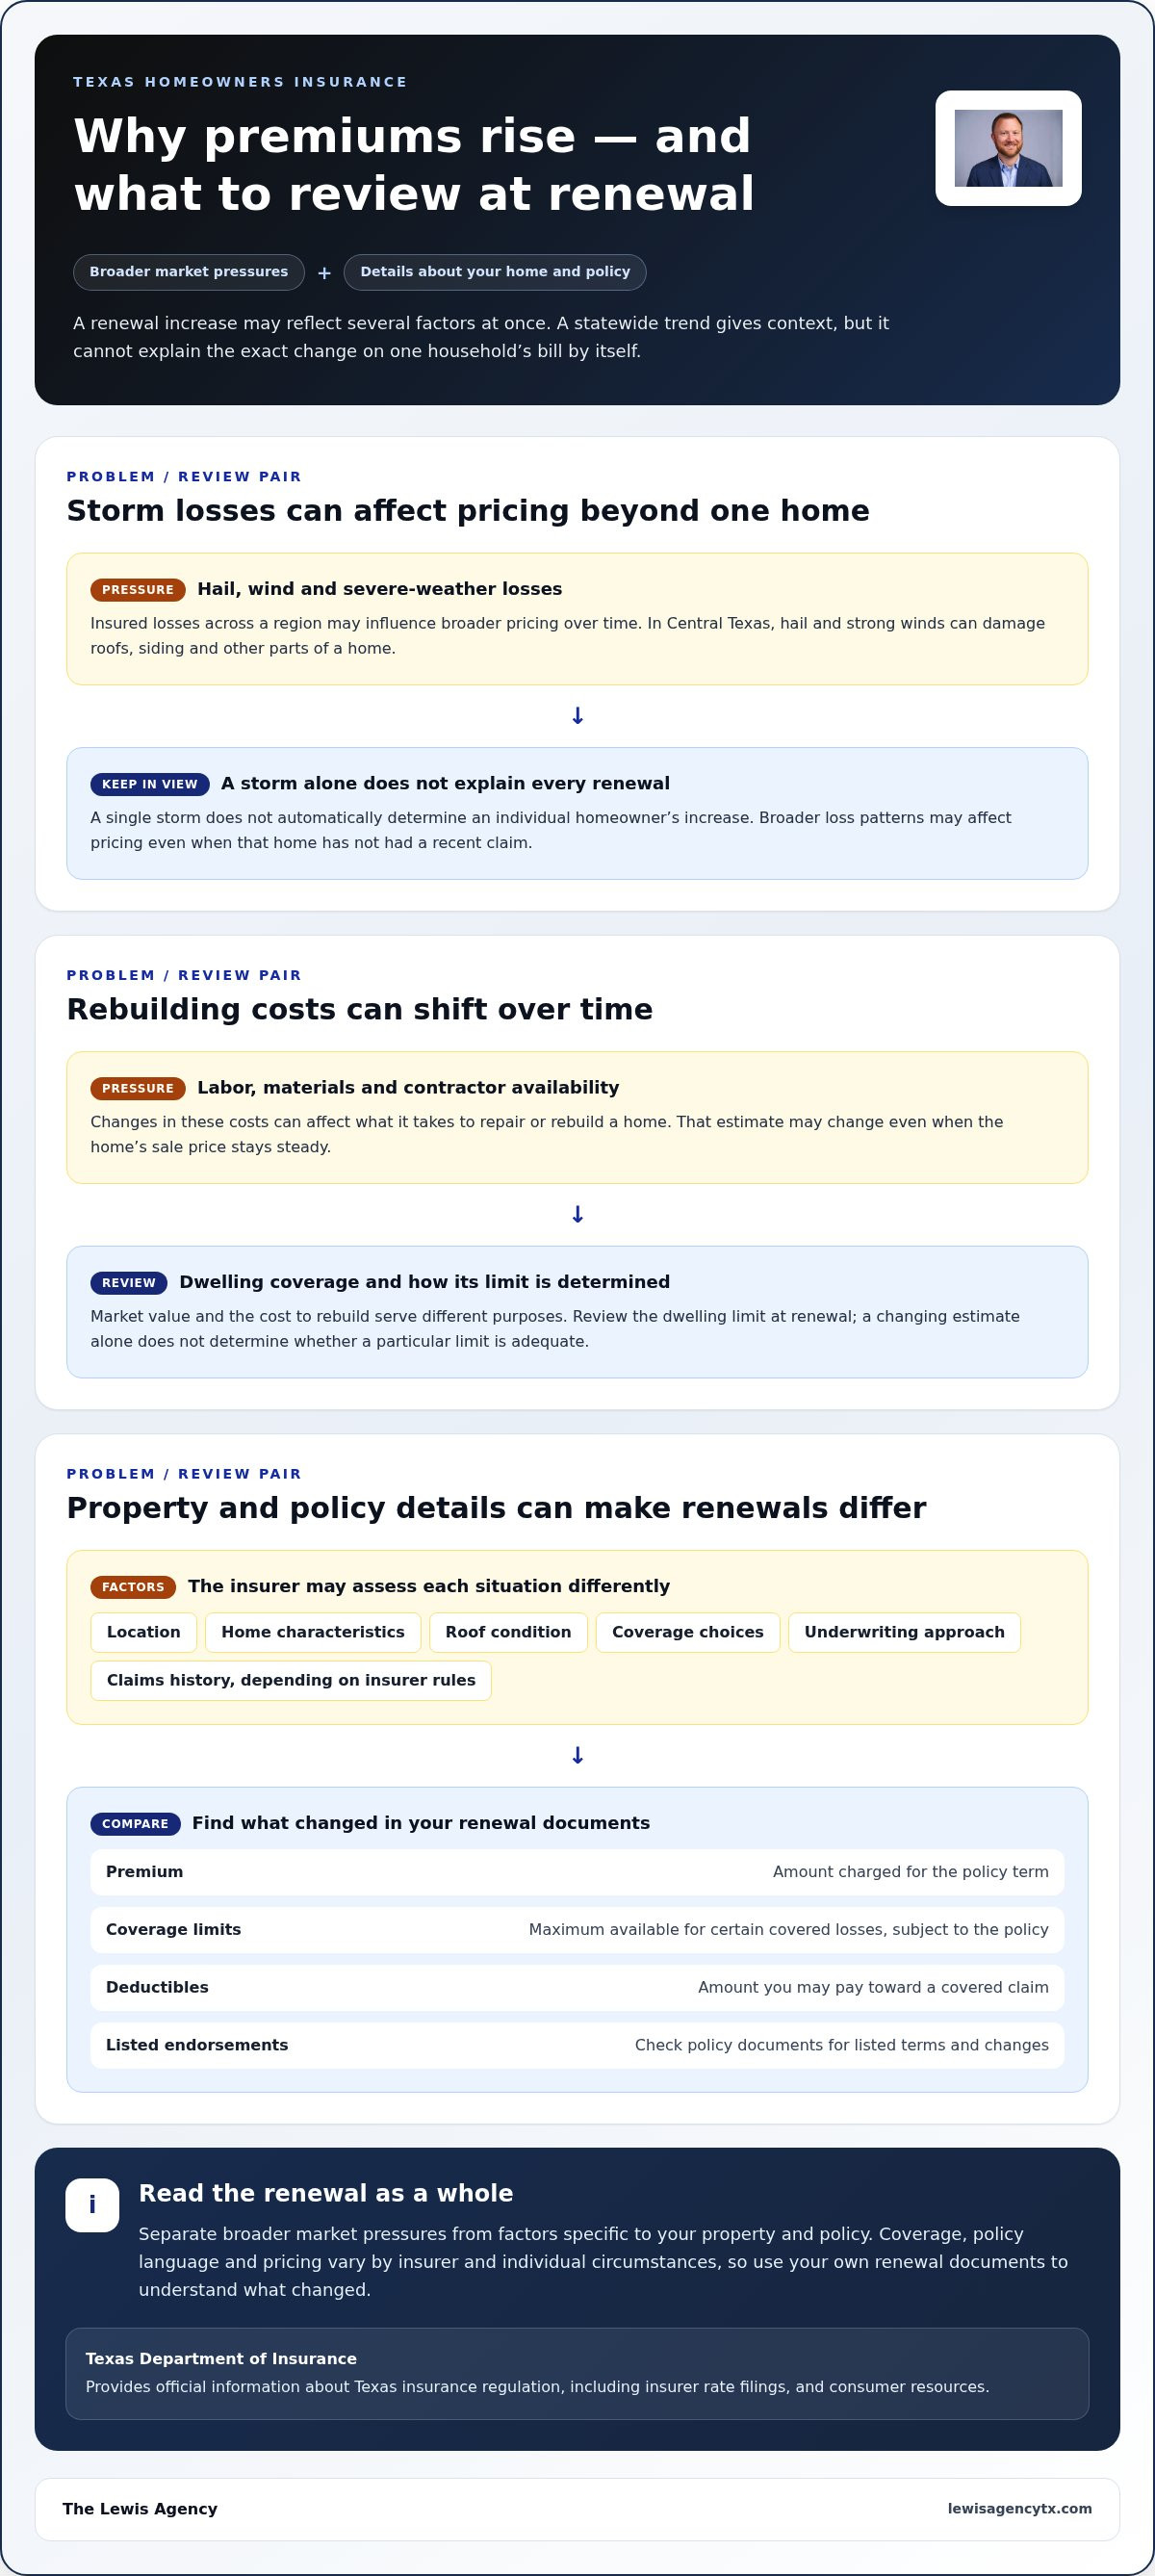
There isn’t one cause behind every increase. Severe weather losses, higher costs to repair or rebuild homes, and other pressures on insurers can all play a role. Your location, roof condition, coverage choices, and policy details may also affect your rate, so two homes in Central Texas can have different renewal changes. Cutting coverage isn’t the only step to consider. A rushed change could leave you unsure about what your policy covers.
This guide explains the main forces behind rising Texas homeowners insurance premiums, why rates vary between households, and what to review before making a change. Chris Lewis has more than 25 years of insurance experience and helps Central Texas homeowners understand their coverage and policy questions.
Key Takeaways
- Why do Texas insurance rates keep increasing? Several pressures can contribute, including weather losses, repair costs, and insurer rating practices.
- Separate broader market pressures from details specific to your home, such as its location, roof, and selected coverage.
- Hail and wind can affect Central Texas insurance costs, but a single storm doesn’t automatically explain an individual renewal increase.
- Compare your renewal documents and review the premium, coverage limits, deductibles, and listed endorsements to spot what changed.
- Understand your policy before making coverage changes. Rates and coverage vary by insurer, policy, and individual circumstances.
Why Texas Homeowners Insurance Rates Keep Increasing
A higher renewal bill can be unsettling, especially when the notice doesn’t explain what changed. A premium increase means the amount charged for your policy term is higher than it was for the previous term. It doesn’t necessarily mean your home changed or that you filed a claim. So, why do Texas insurance rates keep increasing? Several pressures can contribute at once, and no single statewide trend explains every household’s renewal.
Insurers set prices based on expected insured losses, the cost of repairing or rebuilding homes, property risks, and rating practices under state oversight. When repair costs rise, a covered loss may cost more to address. When an insurer expects greater losses across an area or group of policies, that broader experience may also influence pricing. The Texas Department of Insurance (TDI) provides official information about insurance regulation in Texas, including insurer rate filings.
Texas premiums can rise when loss expectations, rebuilding costs, and property-level risk shift at the same time. A statewide trend can provide context for a renewal, but it can’t explain the exact amount on one household’s bill by itself.
What a homeowners insurance premium pays for
A premium is the amount you pay for insurance over the policy term. It’s separate from the deductible, which is the amount you may have to pay toward a covered claim, and from coverage limits, which describe the maximum amount available for certain covered losses under the policy. Your out-of-pocket expenses can depend on the loss, policy terms, exclusions, and applicable deductible. Policy language and structure vary by insurer, so use your own documents rather than assuming every policy handles these items the same way.
Why one Texas homeowner may see a different increase
Location, home characteristics, selected coverage, and an insurer’s underwriting approach may all affect pricing. A statewide rate trend doesn’t mean every homeowner’s renewal will change by the same amount. Insurers may assess property details differently, and coverage choices can also affect the premium. An insurer may consider a home’s claims history, depending on its rules and the policy.
Consider a hypothetical comparison: two homes in Central Texas are in the same general area, but one has a newer roof while the other has an older roof. The homeowners have also chosen different coverage. Those details could contribute to different pricing or renewal outcomes, depending on the insurer’s rules. This is an illustration, not a prediction about how a specific company will rate either home.
When a renewal arrives, separate what may be happening across the market from what may relate to your property or policy. Higher repair costs or expected losses may affect pricing beyond one household. Location, home condition, coverage selections, and underwriting are more specific to your situation. Start with the renewal documents to identify which figures or terms changed.
How Severe Weather and Rebuilding Costs Put Pressure on Texas Premiums
Storm damage can affect insurance costs beyond the home that was hit. When hail, wind, or other severe weather leads to insured losses across a region, insurers may account for those broader loss patterns when setting prices over time. That doesn’t mean one storm automatically determines a particular homeowner’s renewal. Pricing reflects multiple factors, and each insurer assesses risk under its own rating practices.
In parts of Central Texas, hail and strong winds are practical concerns for homeowners, especially when storms damage roofs, siding, or other parts of a house. Local exposure isn’t a prediction that a specific home will have a loss. The Texas Department of Insurance official website offers Texas insurance information and consumer resources homeowners can use to understand the broader market.
Hail, wind, and other weather-related losses
Weather losses can add up across many properties, even though each home’s experience is different. An insurer may consider patterns in covered claims and the cost of paying them as part of its broader pricing decisions. That’s one reason a homeowner’s premium may be affected by market conditions even without a recent claim on that property.
Insured storm losses can put broader pressure on premiums, while higher rebuilding expenses can raise the cost of repairing or replacing damaged homes. These overlapping pressures help explain why Texas insurance rates keep increasing, though they don’t mean every policyholder faces the same risk or premium change.
Why rebuilding-cost changes matter
Repair and rebuilding costs can change as labor, materials, and contractor availability shift. The amount needed to rebuild a home may therefore change even if its sale price stays steady. A home’s market value includes factors such as land and location. Dwelling coverage is intended to address the home’s insured structure, subject to the policy’s terms and limits. These figures serve different purposes.
For example, a Central Texas homeowner could see local home values remain relatively stable while the estimated cost of replacing building materials and labor rises. That doesn’t automatically mean a specific coverage limit is adequate or inadequate. It does make the dwelling limit and how it’s determined useful items to review at renewal.
Roof damage is one area where the distinction between rebuilding terms can matter. Policies may treat roof losses differently depending on whether settlement is based on replacement cost or actual cash value, as well as on the policy and circumstances. Understanding those terms can help you assess what a roof claim might mean for your out-of-pocket costs. You can review your homeowners coverage with those questions in mind before making changes.
Weather losses and rebuilding expenses are related pressures, but neither explains every renewal on its own. Your location, property details, and policy terms still matter. Keep those differences in view when considering how broader market forces may relate to your coverage.
Which Rate Pressures Are Shared Across Texas, and Which Are Property-Specific?
A renewal reflects more than one kind of risk. Some pressures may affect an insurer’s broader pool of policies, while others relate to a particular home or the coverage selected for it. Separating those categories can make a renewal easier to understand. It also helps answer the question, “why do texas insurance rates keep increasing?” without assuming every homeowner is affected in the same way.
| Shared market pressures | Property-level considerations |
|---|---|
| Insured catastrophe losses across a wider area | Location and characteristics of the home |
| Changes in repair and rebuilding expenses | Roof condition or age and other property details |
| Possible insurer expenses, including reinsurance and operating costs | Coverage selections, policy terms, and claims history |
Broader forces that can affect many policyholders
Weather-related claims and changes in repair costs can influence insurers’ overall expenses. Reinsurance, which is insurance purchased by insurers to help manage large losses, may also be part of an insurer’s broader cost picture. Operating expenses are another possible business consideration. These factors don’t establish how much of a particular premium change came from any one source, and a statewide pattern doesn’t mean all policyholders receive identical renewals.
The Texas Department of Insurance provides official information about insurance in Texas, including consumer guidance and rate-related resources. State-level information can help put market developments in context, but it won’t explain every detail of an individual policy’s price.
Property and policy details that can affect an individual renewal
An insurer may consider a home’s location, roof condition or age, construction characteristics, selected coverage, and claims history. Which factors apply, and how they affect a premium, depends on that insurer’s rating and underwriting rules and the policy involved. A factor that matters for one home or insurer may be treated differently for another.
For example, two hypothetical homes in the same Central Texas community could differ in roof condition, building features, or the coverage choices their owners made. Their renewals could therefore differ, even though both households face some of the same wider market pressures. This illustrates why a statewide rate trend can’t predict an individual homeowner’s renewal.
Use the table as a guide, not a rating formula. It can help you sort questions into two groups: what may reflect broader insurance-market conditions, and what may be specific to your home or policy. Compare your renewal documents with your current policy. Look for changes in the premium, coverage selections, and other listed details before deciding what questions to raise. A change in one figure doesn’t, on its own, identify the reason for the full increase.
What to Review When Your Texas Home Insurance Premium Goes Up
A higher renewal premium can be frustrating, but you don’t have to make a quick coverage decision to understand it. Compare your renewal documents with your current policy, note what changed, and ask focused questions about the differences. If you’re wondering why Texas insurance rates keep increasing, this review can help separate a change in your premium from a change in coverage.
Compare the renewal with your current policy
Use the declarations page as a starting point. Depending on the insurer and policy, it lists key details such as your premium, coverage limits, deductibles, and endorsements. Compare the current version with the renewal, looking for changed amounts or listed terms. The declarations page is a snapshot, not a replacement for the full policy wording, which explains conditions, exclusions, and how coverage applies.
Check one item at a time. Did the dwelling limit change? Is a deductible different? Was an endorsement added, removed, or revised? If something looks unfamiliar, mark it for follow-up rather than guessing what it means. Keep the documents side by side so you can point to the exact figure or wording when asking about the change.
Compare policy terms, not just the total premium. A lower price doesn’t necessarily mean the coverage is the same. A change to a limit, deductible, or endorsement could affect what you pay or what the policy may cover after a loss. The effect depends on the policy language and circumstances.
Ask questions before changing coverage
Once you’ve identified the differences, ask your agent specific questions. For example, ask which policy terms changed, how a deductible applies to a covered loss, or what an endorsement does. If a term is unclear, ask for an explanation in plain language. Focused questions are more useful than trying to infer the reason from the premium alone.
Before changing a limit or deductible, consider how that change could affect your finances after a loss. A different deductible may shift more or less of a covered loss to you, depending on its terms. A lower limit could also change the amount available for a covered loss. Don’t treat a lower renewal price as a like-for-like option until you understand what changed.
Write down your questions and keep the answers with your policy documents. The Lewis Agency can help explain homeowners policy language and renewal details. The goal is to understand the coverage and the change, not to assume that a review will produce a particular rate. See the agency’s policy information.
How Central Texas Homeowners Can Make Sense of the Next Renewal
A renewal makes more sense when you compare it with the policy you already have. Statewide pressures, such as weather-related losses and higher repair expenses, may affect the broader market. Other considerations may be tied to your home, its location, its claims history, or the coverage you selected. These forces can overlap, but your own policy is the starting point for understanding how they relate to your renewal.
That’s a practical way to approach the question, “why do texas insurance rates keep increasing?” Market trends provide context, but they don’t explain every detail of an individual premium. Comparing documents and asking about unfamiliar changes can help you make decisions deliberately rather than reacting to the total alone.
Build a practical annual policy-review habit
Set aside time to review your coverage when the renewal arrives, and revisit it after a major home improvement or household change. An addition or significant renovation, for example, may change what you want to ask about your home’s insured value. A change in who lives in the home or how it’s used may also be a reason to review relevant policy details.
Keep the current policy, declarations page, endorsements, and renewal notice together. Having those documents in one place makes it easier to compare terms from one policy period to the next and see what questions remain. Don’t rely on memory alone. A written comparison can help distinguish changed figures from terms that stayed the same.
Review your deductibles and limits before a loss occurs. Make sure you understand what the deductible means for your share of a covered loss and what the stated limits apply to under your policy. Details vary by insurer and policy, so read the wording that applies to your coverage rather than assuming it matches someone else’s.
Get help understanding your policy
Insurance language can be difficult to interpret on your own. An agent can help explain policy terms, answer coverage questions, and clarify what appears in the policy documents. That guidance can make it easier to understand your options, but it doesn’t control the insurer’s rates, underwriting, renewal decisions, or claim outcomes.
Understanding the forces behind rising premiums is useful, but a broad explanation can’t replace a careful look at your own documents. Write down anything you don’t understand, such as a change to an endorsement or a term that affects how a deductible applies. Then you can ask clear questions and consider coverage changes with a better sense of what they mean.
For homeowners in Austin and across Central Texas, including Leander, Cedar Park, Georgetown, Round Rock, and Liberty Hill, a careful policy review can put renewal questions in context. The Lewis Agency is an Allstate agency that helps homeowners understand their coverage and policy language.
Make Your Next Renewal a More Informed One
A renewal can be a useful moment to check whether your policy still reflects your home and your priorities. Keep notes about renovations or household changes, and bring unclear terms into the conversation before making adjustments. That way, decisions can start with what matters for your own situation, not just the amount due.
If you’re still asking, “why do texas insurance rates keep increasing,” remember that a general explanation can’t answer every question about your specific policy. The next step is to understand the wording and choices in front of you. Chris Lewis has more than 25 years of insurance experience and helps Austin and Central Texas homeowners understand their coverage.
For help understanding policy language or reviewing your homeowners coverage, talk with The Lewis Agency. A clear conversation can help you understand what your policy says before you need to rely on it.
Frequently Asked Questions
Are Texas homeowners insurance rates rising faster than rates in other states?
Not necessarily in every comparison. Whether Texas rates are rising faster depends on the time period, type of policy, and how each comparison measures premiums. A fair comparison needs to look at similar coverage and dates across states. Statewide averages also don’t tell you what will happen at one address. For your own renewal, compare the same policy details across terms rather than relying on a national ranking alone.
Can a roof replacement lower my Texas homeowners insurance premium?
It may affect the premium, but a lower price isn’t guaranteed. An insurer may consider the roof’s age, materials, condition, and other details under its own rating rules. Replacing a worn roof could change how the property is assessed, but the renewal price may also reflect other factors. Before deciding on a project for insurance reasons, ask how your policy treats roof details and what documentation may be useful.
Does filing a homeowners insurance claim make my Texas rates go up?
Not automatically in every case. An insurer may consider claims history when assessing a policy, but whether a claim affects a future premium depends on the insurer, the claim, and other circumstances. A claim also doesn’t guarantee a particular payment or rate change. Before deciding whether to file, review your policy and consider the damage, deductible, and possible claim outcome. Your agent can explain policy terms and help clarify the claims process.
Do Texas property taxes affect homeowners insurance rates?
Property taxes generally aren’t part of the homeowners insurance premium. They’re separate expenses, even though both may appear in a mortgage escrow payment. If your monthly escrow amount rises, check the escrow statement to see whether the change comes from taxes, insurance, or both. A tax assessment change doesn’t, by itself, show that your insurance premium changed. Compare the insurer’s renewal documents to identify the premium amount.
Why can two similar homes in the same Central Texas neighborhood have different premiums?
Homes that look alike from the street may have different policy details or risk characteristics. One homeowner may have selected different limits or endorsements, while the homes may differ in construction, roof condition, or claims history. Insurers also apply their own rating and underwriting rules. In Austin, Leander, Cedar Park, Georgetown, Round Rock, or Liberty Hill, sharing a neighborhood doesn’t mean two policies are identical.
Can I lower my premium by choosing a higher deductible?
A higher deductible may reduce a premium in some cases, but the effect depends on the insurer and policy. It also means you could be responsible for more of a covered loss before insurance applies. Before changing it, consider whether you could manage that added expense after a storm or other covered damage. Compare the premium change with the revised deductible and review how the deductible applies to different types of losses in your policy.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.
Lower Your Texas Homeowners Insurance Premium in 2026
Wondering how to lower homeowners insurance premium Texas 2026 costs? Review deductibles, property updates, and coverage options with this Central Texas guide.
If you searched “how to lower homeowners insurance premium texas 2026,” you’re probably looking for practical ways to manage renewal costs without taking on more risk than you can afford. A lower premium can come with trade-offs, so start by understanding what a proposed change means for your coverage and your costs after a loss.
This guide walks through what to review, from your home’s roof and other property details to your coverage and deductibles. It also explains how to ask about possible discounts without assuming you qualify. Policy terms and pricing vary, so no single change fits every home. Chris Lewis of The Lewis Agency, an Allstate agency serving Austin and Central Texas, brings more than 25 years of insurance experience to helping homeowners understand their coverage. Whether you live in Austin, Leander, Cedar Park, Georgetown, Round Rock or Liberty Hill, use this guide to prepare for a clear, informed policy discussion.
Key Takeaways
- Know the difference between your premium, deductible and claim payment, and understand which details you can review.
- Review coverage before making changes. Lowering limits or adjusting policy terms can affect your financial risk after a loss.
- Compare possible steps by effort, cost and effect on protection. Treat bundling auto and home insurance as a question, not a promised discount.
- Use your declarations page and current policy documents to note home updates and prepare questions for your renewal review.
- Chris Lewis and The Lewis Agency can help explain policy terms and make coverage questions easier to understand.
Start by understanding what drives a Texas homeowners insurance premium
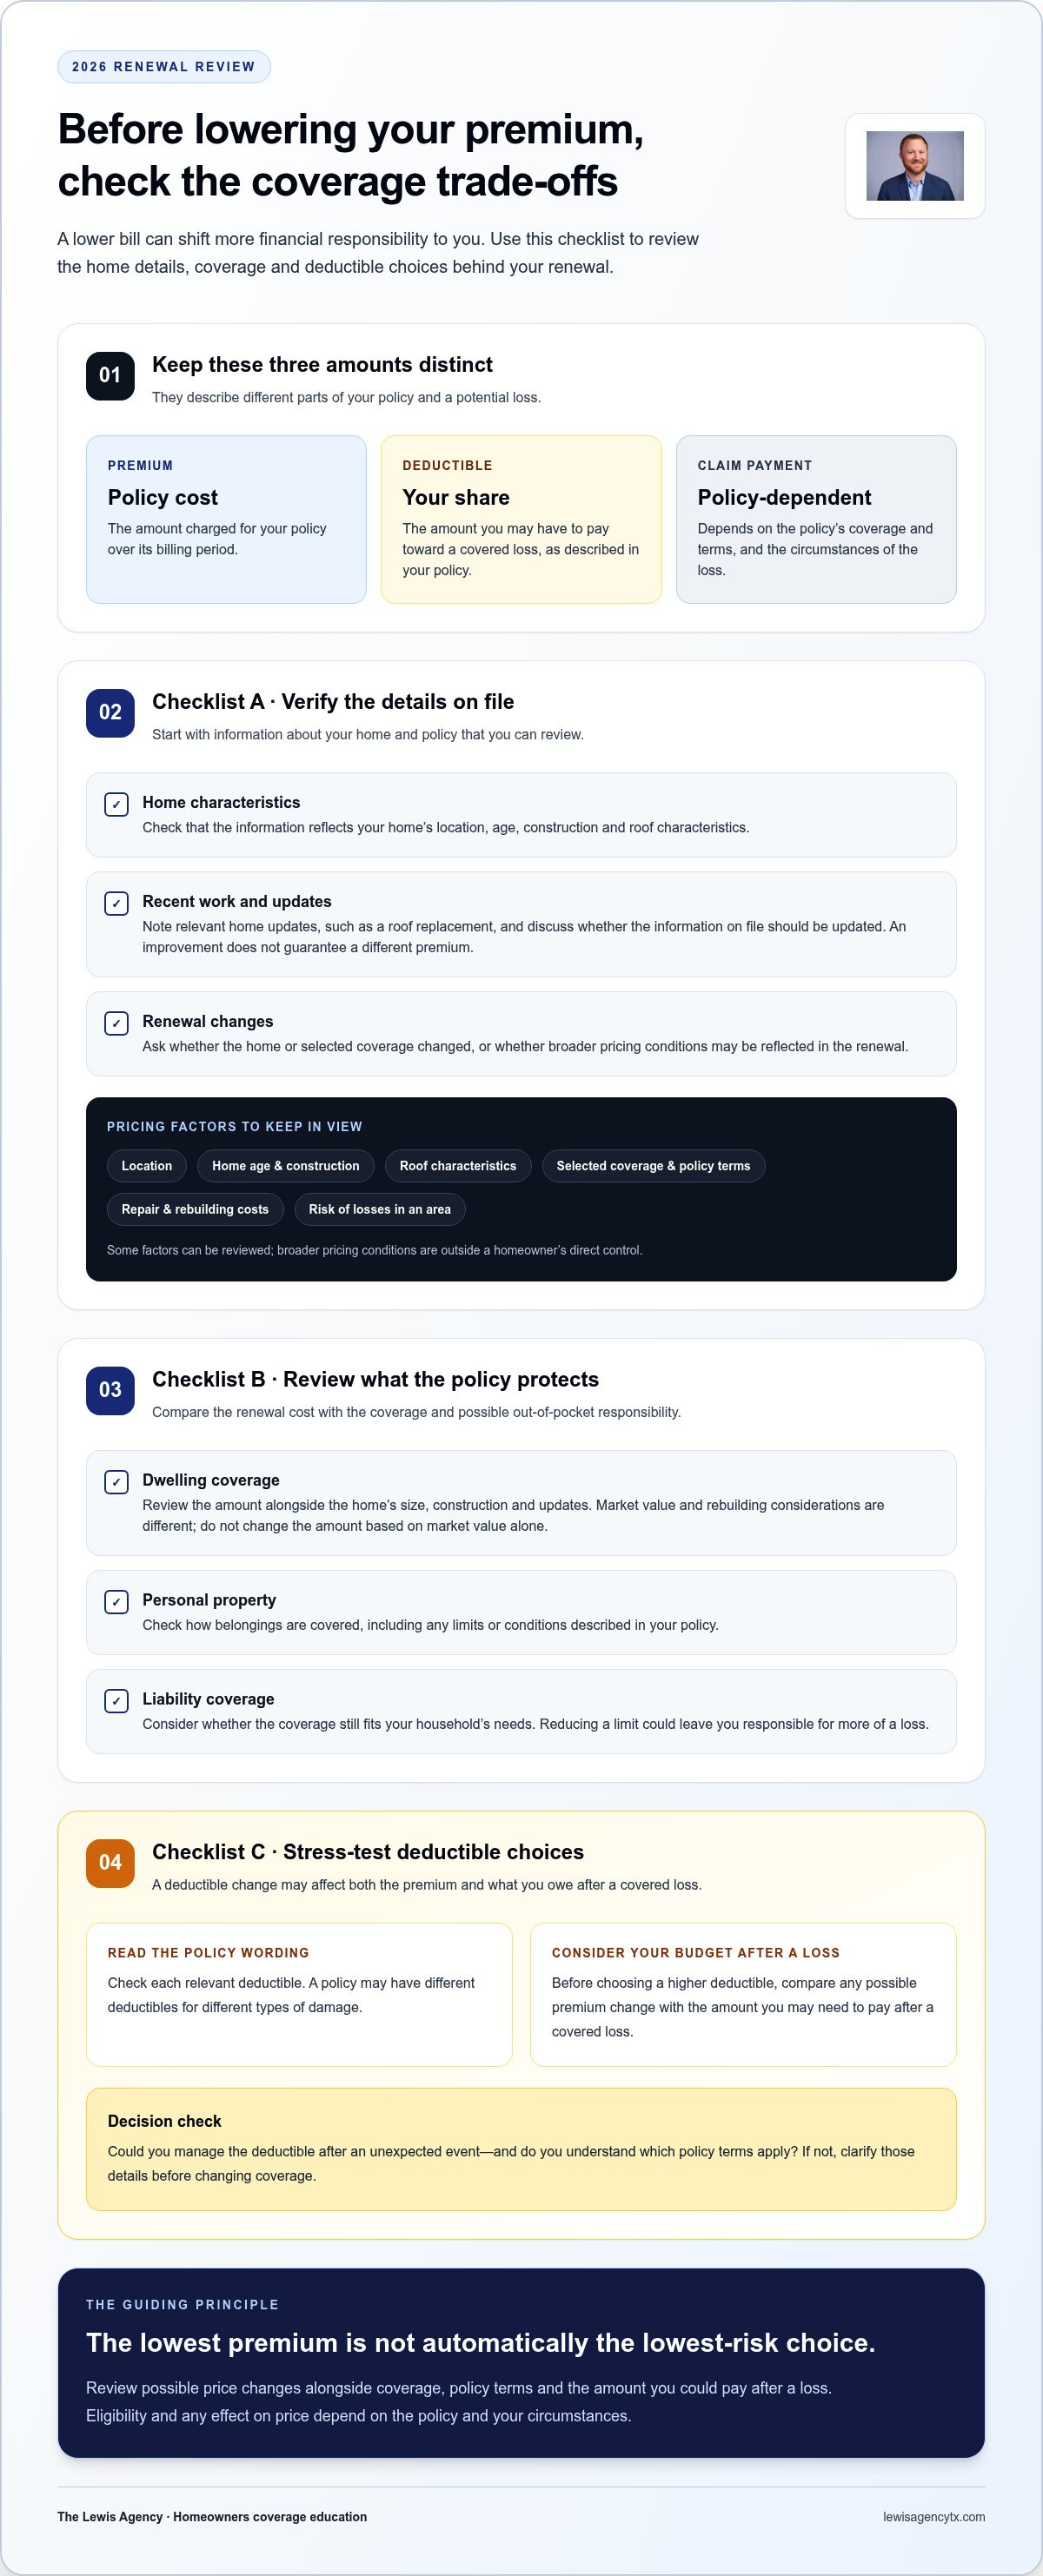
Your premium is the amount charged for your policy over its billing period. It is not the same as your deductible, which is the amount you may have to pay toward a covered loss under your policy. A claim payment depends on the policy’s coverage and terms, as well as the circumstances of the loss. Keep these amounts separate when you compare renewal options.
Some pricing factors relate to your home and coverage choices. Others reflect broader conditions, such as repair and rebuilding costs or the risk of losses in an area. Location, the home’s age and construction, roof characteristics, selected coverage and policy terms may all affect pricing. General information about homeowners insurance can explain a policy’s purpose, but the documents for your policy describe the coverage and exclusions that apply to your home.
No single action guarantees a lower premium. Weigh any potential price change against the coverage and out-of-pocket risk that come with it. To find ways to lower your homeowners insurance premium in Texas in 2026, separate the details you can review from pricing factors you cannot control.
Which parts of a premium can a homeowner influence?
You can review your selected coverage, deductible choices and the property information on file. For example, check that the information about your Central Texas home reflects its current roof and any relevant updates. Consider whether the coverage still fits your home and belongings, and whether you could manage the deductible after a loss. Eligibility and any effect on price depend on the policy and your circumstances.
Imagine a homeowner near Round Rock whose roof was recently replaced. It makes sense to document the work and discuss the updated information during a policy review, but the replacement does not guarantee a different premium. The insurer’s rules, policy terms and other pricing factors still matter. Look at the options together rather than assuming one improvement will produce a particular result.
Why can a Texas premium change at renewal?
A renewal price may reflect policy-specific details, such as updated information about the home, selected coverage or changes in pricing. It may also reflect broader conditions that affect repair and rebuilding costs or the insurer’s assessment of risk. A homeowner cannot directly change those broader factors, even though they may influence the price.
Start by asking whether anything about your home or policy changed, or whether the renewal may reflect broader pricing conditions. That can keep the discussion focused on useful next steps instead of an assumed cause. For more context about factors that may affect costs, see the Texas home insurance rate increases guide. Then review your current policy details before deciding whether to make an adjustment.
Review coverage and deductibles before trying to cut your premium
To assess a renewal, compare the premium with the coverage and the amount you could pay after a loss. Review dwelling coverage for the home, personal property coverage and its terms, liability coverage, and each deductible shown in your policy documents. Changing any of these elements may affect the premium, but it can also shift more financial responsibility to you.
The lowest premium is not automatically the lowest-risk choice. Before changing coverage, consider what the change could mean in a serious loss, not just what it might do to the bill. Make sure you understand both the potential price effect and the coverage trade-off.
Check whether dwelling coverage still reflects your home
Review the dwelling coverage amount alongside your home’s current characteristics, such as its size, construction and updates, and check how the policy describes coverage. Market value and rebuilding considerations are different: a sale price may reflect land and local demand, while rebuilding relates to the work and materials needed to reconstruct the insured home. Valuation methods and policy terms vary, so do not change the amount based on market value alone. The Austin homeowners insurance coverage guide offers more context for reviewing coverage.
Review personal property and liability separately. Check how the policy covers belongings, including any limits or conditions, and consider whether the liability coverage still fits your household’s needs. Reducing a limit is not necessarily a harmless way to lower the premium; it could leave you responsible for more of a loss. The Texas Department of Insurance (TDI) provides consumer information about insurance, while your policy documents explain the terms that apply to your coverage.
Weigh deductible changes against your ability to pay
A deductible is the amount you may pay toward a covered claim, as described in your policy. Changing it may affect both the premium and what you owe after a loss. Deductibles are policy-specific. A policy may have different deductibles for different types of damage, so check the relevant wording rather than assuming one amount applies to every claim. Before making a change, consider whether you could manage the out-of-pocket cost after an unexpected event.
For example, if you are considering a higher deductible to reduce renewal costs, compare the possible premium change with the amount you would need to pay after a covered loss. The Texas homeowners insurance deductibles guide can help you identify what to look for in your policy. You can also have a policy review conversation with The Lewis Agency to understand the terms before deciding what to adjust.
Compare practical premium-saving options without assuming a discount
Possible ways to manage a premium differ in effort, expense and effect on protection. A policy question may take little effort, while a roof project can involve substantial planning and cost. Neither guarantees a lower price. Before taking action, consider the expense, whether the step changes coverage or risk, and what information the insurer needs to determine eligibility.
Use these questions to compare options:
- Policy review: Is there information to correct or clarify, and could a proposed change affect your protection?
- Auto coverage: Is a home and auto option available for your policies, and what eligibility rules apply?
- Property improvements: What maintenance or resilience benefits would the work provide if the premium stays the same?
- Potential discounts: What documentation is required, and how are eligibility and any price effect determined for your policy?
For broader ideas, the Insurance Information Institute discusses ways to lower homeowners insurance costs. Treat general suggestions as questions to explore, not a promise that a particular option applies to your policy. Texas-specific consumer information from the Texas Department of Insurance (TDI) can help you frame questions about policy costs and discounts.
Ask about eligibility for policy discounts
Ask which discounts, if any, may apply to your specific policy. Do not assume you qualify because another homeowner received a discount or a general article mentions one. Eligibility, required documentation and the effect on the premium can vary. Ask what conditions apply and whether a policy change would affect coverage as well as price.
Consider roof and home improvements carefully
Hail is a practical concern for Central Texas homeowners, but replacing a roof or adding a safety feature does not guarantee a lower premium. Weigh the project’s maintenance and resilience benefits on their own, then ask whether the insurer considers the improvement and what documentation may be needed. That way, you are not taking on an expense solely because you expect insurance savings.
A measured review can help you distinguish a useful option from one that costs more or shifts risk without a clear benefit. The Lewis Agency can help you understand your policy terms and available choices through a homeowners coverage review.
Use a step-by-step review before your 2026 renewal
Preparing for a renewal can make the discussion more useful and less rushed. Start with your declarations page and current policy documents. Note what has changed and what you need explained. This keeps the focus on understanding your coverage and the options available under it, rather than treating a lower quoted price as the only goal.
Prepare documents and note changes to the home
Gather your renewal notice, declarations page and current policy documents. Make a short record of relevant changes since the last review, such as roof work, updates to major home systems, a change in occupancy or a shift in household circumstances. These details help you discuss whether the information on file is current. An update does not automatically qualify the home for a discount or change the premium.
Work through the review in order:
- Gather documents. Keep the renewal notice, declarations page and policy wording together so you can refer to the same information during the discussion.
- Inspect changes. Note work completed on the home and any changes in how it is used. For roof work, record what was done and when, along with any available documentation.
- List questions. Identify unfamiliar terms, a premium change you want explained or coverage details you would like to understand. Put the most important questions first.
- Review options. Discuss the current policy and any proposed adjustments one at a time. Consider how each could affect coverage, deductibles, exclusions or out-of-pocket costs, as well as the premium.
Ask focused questions about premium and protection
Ask what changed at renewal, which policy terms influence the premium and whether updated home information was considered. If an option involves changing coverage, ask how it could affect limits, exclusions, deductibles or the amount you might need to pay after a loss. The answers depend on your policy and circumstances.
Write down the explanation and any follow-up items. If a term is unclear, ask for a plain-language explanation and, when helpful, where it appears in the policy documents. You will have something concrete to review afterward instead of relying on memory.
If you are looking for ways to lower your homeowners insurance premium in Texas in 2026, a prepared policy review can help you evaluate changes without losing sight of protection. Review your homeowners policy with The Lewis Agency to discuss its terms and your renewal questions.
Get help understanding your Texas homeowners policy
A renewal conversation can help turn policy language into clear questions and choices. Chris Lewis has more than 25 years of insurance experience, and The Lewis Agency is an Allstate agency serving Austin and Central Texas, including Leander, Cedar Park, Georgetown, Round Rock and Liberty Hill. The agency can help homeowners understand policy terms and the claims process. Rates, underwriting, renewal, coverage and claim-payment decisions are made by the insurer, not the agency.
A discussion can clarify what your documents say and what questions to raise, but it cannot promise a particular premium or claim outcome. The goal is to help you understand your current policy so you can consider possible changes carefully.
What a policy discussion can help clarify
Bring your renewal notice, declarations page and any policy wording you are unsure about. A discussion can help explain how coverage terms, deductibles and other policy details fit together, as well as how the claims process generally works under your policy. If a term is unclear, ask where it appears in the documents and what it means for your circumstances.
Keep the conversation grounded in the actual policy. Coverage and exclusions vary, so a general explanation is not a substitute for the wording that applies to your home. You can ask how a proposed change might affect protection or costs after a covered loss, then consider the trade-off before deciding.
Choose a useful next step
For Austin and Central Texas homeowners, a useful first step is to raise renewal questions before making changes. Note what you want to understand, whether it is a premium change, a deductible or a particular coverage term. This keeps the discussion focused on your policy instead of assuming a change will produce a specific result.
If you are considering how to lower your homeowners insurance premium in Texas in 2026, use the conversation to understand possible effects on both price and protection. Ask for unfamiliar language to be explained plainly, and make sure you are comfortable with any change before moving ahead. You may decide an adjustment makes sense, or that your current terms better fit your needs.
There is no need to make a change simply because renewal is approaching. If you would like to talk through your current policy and questions, talk with The Lewis Agency.
Make your next renewal decision with confidence
A renewal review does not need to end with an immediate change. Take time to consider what you learned, revisit any policy language that remains unclear and decide which trade-offs fit your household’s needs. A premium adjustment is useful only if you understand what changes along with it.
If you are exploring ways to lower your homeowners insurance premium in Texas in 2026, bring specific questions to a policy discussion. Ask how each option you are considering could affect your coverage or out-of-pocket costs. You do not have to choose an adjustment simply because it is available; keeping your current terms may also be the right decision for your needs.
If you would like help working through your renewal questions, review your homeowners policy questions with The Lewis Agency. A thoughtful conversation can help you understand your choices and the protection you keep.
Frequently Asked Questions
Can bundling homeowners and auto insurance lower my premium?
It may affect the price, but whether a home and auto option applies and what it changes depends on the insurer, policies and household details. Ask for the home and auto costs separately and together, then compare the combined price alongside coverage and deductibles. For example, a lower homeowners premium alone may not make the combined option less expensive if the auto policy cost changes. Do not assume a discount is available or guaranteed.
Will replacing my roof lower my Texas homeowners insurance premium?
A new roof may affect how the insurer evaluates the home, but it does not guarantee a lower premium. Before starting a project mainly for insurance reasons, ask how the proposed work would be considered under your policy. Keep records such as invoices, permits if applicable, and details about materials or installation. Also weigh the roof’s condition, maintenance needs and resilience benefits separately from any possible insurance effect.
Does homeowners insurance in Texas cover flood damage?
Do not assume your homeowners policy covers flooding. The policy wording determines how water damage is treated, and coverage for a plumbing leak may differ from damage caused by rising water. Check the definitions, exclusions and any endorsements in your documents, then ask about your specific situation. If flood risk is a concern, consult consumer guidance from the Texas Department of Insurance or FEMA about coverage options rather than relying on a general assumption.
Can filing a small homeowners insurance claim affect my premium?
The effect depends on the insurer, policy, claim details and underwriting circumstances, so there is no universal outcome to rely on. Before deciding whether to file, compare the known damage with the applicable deductible and review how the claims process works. The agency can explain policy language and the process, but it does not determine claim decisions, premium changes or renewal outcomes. Keep records of damage and communications related to the loss.
Do home security devices qualify for a homeowners insurance discount?
Some insurers may recognize certain security features, but eligible equipment and any premium effect vary by policy. Before buying a device mainly for possible savings, ask whether the specific equipment is considered and what documentation may be needed. Keep its model information and installation records. Then weigh any potential insurance benefit against the device’s separate value for household safety and property protection, even if the premium does not change.
Can I lower my premium by changing my homeowners insurance deductible?
A deductible change may affect both the premium and what you pay toward a covered loss, depending on the policy. Before choosing a different amount, consider whether you could manage that expense if a claim occurred alongside other household costs. Check the declarations page and policy wording for applicable deductibles, including whether different types of loss have different terms. Understand the out-of-pocket trade-off before making a change.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.
Actual Cash Value vs. Replacement Cost for a Texas Roof
Compare actual cash value vs replacement cost roof Texas coverage to understand how depreciation affects roof storm claims in Austin and Central Texas.
Could two homeowners with similar hail damage receive very different roof claim payments? Policy wording, depreciation, and claim conditions may help explain the difference. If you’re searching “actual cash value vs replacement cost roof texas,” you’re likely trying to understand what those terms could mean for your roof in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, or Liberty Hill.
It’s easy to mix up the valuation method, the deductible, and a repair estimate, especially after a storm. Actual cash value generally accounts for depreciation, while replacement-cost coverage may handle depreciation differently. The exact terms and claim process depend on the policy.
This guide explains the basic difference, shows what policy language and conditions to check, and offers questions to ask before a storm. The Lewis Agency helps homeowners choose coverage limits and endorsements based on their dwelling and financial needs. The goal here is to help you read your policy with greater confidence, not predict a claim outcome.
Key Takeaways
- For “actual cash value vs replacement cost roof texas,” the key difference is how the policy treats depreciation when valuing roof damage.
- Check your declarations page and policy documents for roof valuation terms and endorsements that may affect coverage.
- Review the deductible separately from depreciation. They are distinct parts of a claim calculation.
- Look for payment conditions and claim requirements, and note what you want clarified before a storm.
- The Lewis Agency can help you understand homeowners coverage options, limits, and endorsements. The insurer makes claim decisions based on the policy and circumstances.
What ACV and Replacement Cost Mean for a Texas Roof
Actual cash value (ACV) and replacement cost are methods a policy may use to value covered roof damage. They describe how the insurer calculates a loss, not whether the damage is covered or exactly what a claim will pay. The question behind “actual cash value vs replacement cost roof texas” is how depreciation and other policy terms may affect the value assigned to roof damage.
In general, ACV starts with the cost to repair or replace damaged property and may subtract depreciation. Replacement-cost valuation generally does not subtract depreciation at the outset. For a neutral overview of the basic ACV concept, see Actual Cash Value (ACV). Your policy’s wording, endorsements, exclusions, deductible, and claim requirements still matter. Neither label alone guarantees that a roof will be replaced or establishes the final payment.
What does actual cash value mean for roof damage?
Depreciation is an adjustment that may reflect a roof’s age, condition, or wear, depending on the policy terms. It can reduce the value used to calculate a claim, but that estimated value is not necessarily the amount ultimately payable. Other terms, including the deductible and coverage conditions, may also affect the calculation.
Hypothetical example: A storm damages shingles, and an estimate is prepared for the covered repair. If the policy uses ACV, depreciation may be applied to that estimate before the insurer calculates any payment under the policy. The estimate, depreciation adjustment, and deductible are separate considerations. This example does not predict a particular claim result.
What does replacement cost mean for a roof?
Replacement cost generally values covered damage based on the cost to repair or replace it without subtracting depreciation at the outset. That does not necessarily mean the insurer pays the full estimate upfront or in every situation. The policy may set conditions for when or how replacement-cost benefits are paid, such as requirements to complete repairs or provide documentation. Check the specific wording rather than relying on the label alone.
For example, if a covered roof loss has a repair estimate, replacement-cost terms may treat depreciation differently from ACV terms. Payment timing, eligible costs, limits, and other requirements can still affect what is payable. Coverage and claim outcomes vary by insurer, policy form, endorsements, and individual circumstances.
How Depreciation and Policy Conditions Can Affect Roof Settlement
A roof claim involves more than choosing between ACV and replacement cost. The insurer evaluates the reported damage and its cause, applies the policy terms, and considers an estimate alongside those terms. Exclusions, endorsements, limits, and claim requirements may also affect the settlement. A contractor’s estimate can describe proposed repairs, but it does not by itself establish what the policy will pay.
The valuation method alone cannot predict a roof claim payment. Coverage, depreciation, the deductible, and policy conditions all matter.
Keep the deductible separate from depreciation. Depreciation is a possible adjustment to the value of damaged materials. A deductible is the amount that applies under the policy to a covered loss. They are different parts of a claim calculation, and the policy wording determines how they apply.
How is roof depreciation considered?
Age and condition may be relevant when depreciation is considered, but there is no single formula or schedule that applies to every roof policy. The policy wording and claim evaluation govern whether depreciation applies and how it is calculated. Do not assume that a particular roof age automatically produces a fixed reduction. Review the terms that apply to your policy and ask for clarification if the calculation is unclear.
Other coverage questions can matter just as much. The policy’s treatment of the reported cause of damage, any exclusions or endorsements, and applicable limits may affect a claim. A hail-damaged roof and a roof with deterioration may raise different coverage questions, depending on the policy and circumstances. Consider an estimate alongside the policy, not in isolation.
Why replacement-cost coverage may involve more than one payment
Some policies may initially withhold depreciation and make it available only after specified claim steps are completed. Conditions vary, so check your policy for deadlines, required documents, repair requirements, or other steps. Do not assume a particular reimbursement process or timeline applies to your roof.
Before authorizing repairs, understand what the insurer has evaluated, which estimate is being used, and whether any payment conditions remain. If the explanation is unclear, ask the insurer or your insurance professional to point out the relevant policy language. Homeowners can also review their homeowners coverage with The Lewis Agency and discuss policy options, limits, and endorsements. Claim decisions and payments are determined by the insurer.
ACV vs. Replacement Cost: What Texas Homeowners Should Compare
When comparing actual cash value vs replacement cost roof texas coverage, look beyond the label. Check how depreciation is handled, whether payment depends on completing repairs, and what the policy requires from you. Replacement-cost coverage does not automatically mean full reimbursement. The deductible, covered damage, limits, exclusions, and claim conditions may affect the final amount.
| What to compare | ACV | Replacement cost | What to verify |
|---|---|---|---|
| Depreciation | May be deducted based on policy terms and claim evaluation. | Generally is not deducted at the outset, but terms vary. | How does the policy define roof valuation and depreciation? |
| Payment conditions | Payment remains subject to coverage terms and the deductible. | Some policies may require certain steps before additional payment is available. | Are repairs, documents, or other claim steps required? |
| Potential out-of-pocket expense | Depreciation may affect the amount available for covered repairs. | Payment may still be affected by the deductible, limits, and policy conditions. | What expenses could remain your responsibility? |
Hypothetical comparison: Imagine the same covered roof damage and repair estimate under two different policy terms. Under ACV terms, depreciation may reduce the amount used to calculate payment. Under replacement-cost terms, depreciation may not be subtracted initially, though the policy could set conditions for receiving an additional amount. The estimate alone does not determine either outcome, and this example does not predict a claim result.
Which roof valuation method may fit your situation?
Consider your budget flexibility, the roof’s condition, and how you would handle a gap between repair costs and available claim funds. Compare the premium and roof coverage shown in your own policy documents. A lower premium by itself does not show whether coverage fits your needs, and neither valuation method is automatically right for every homeowner.
Does roof age decide whether coverage is ACV or replacement cost?
Roof age may affect underwriting or claim valuation, depending on the insurer and policy. But age alone does not establish which method applies or guarantee a change in coverage. Check the current declarations page and any endorsements for roof-specific terms, then ask what wording applies to your home. Do not rely on a general age cutoff instead of reviewing your policy.
How to Review Your Texas Roof Coverage Before a Storm
A policy review is easier before hail or wind damage creates time pressure. Use this sequence to find the roof terms that could shape a claim, then note anything you want clarified. Whether you own a home in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, or Liberty Hill, confirm what your own policy says instead of relying on a general description of coverage.
- Start with the declarations page. Review the listed property coverage and deductible information. Note whether a separate deductible may apply to wind or hail, then check the policy wording to understand when it applies.
- Confirm the policy form. Find the form identified in your documents and remember that forms and coverage vary by insurer. Do not assume a familiar policy label tells the whole story about roof settlement.
- Look for roof valuation language and endorsements. Search the policy and attached endorsements for terms such as “actual cash value,” “replacement cost,” “roof,” or “depreciation.” Check whether an endorsement changes terms shown elsewhere.
- Review exclusions and claim conditions. Note language that may affect the reported cause of loss, required documentation, repair steps, or deadlines. Ask for clarification if you are unsure what a condition means.
- Keep a record of roof condition. Save relevant inspection, repair, and maintenance records, along with dated photos if available. These records can help describe the roof’s condition, but they do not guarantee coverage or a particular claim payment.
Which policy documents and terms should you check?
Read the declarations page together with the full policy and endorsements. The declarations page can point you to listed coverage and deductible details, while the policy wording explains terms, exclusions, and conditions. The Texas Department of Insurance offers consumer information about homeowners coverage. Check its current guidance and compare it with your policy language.
What should you ask after hail or storm damage?
Record what you observe and preserve relevant maintenance or repair documents. Before authorizing work, ask the insurer how the policy describes roof valuation and which claim steps apply. Do not assume damage is covered based on appearance alone. Coverage depends on the policy and circumstances, and the insurer makes claim determinations.
If you want help discussing your homeowners coverage options, limits, or endorsements, ask The Lewis Agency about your roof coverage. Bring your policy documents and questions so the discussion can focus on the wording that applies to your home.
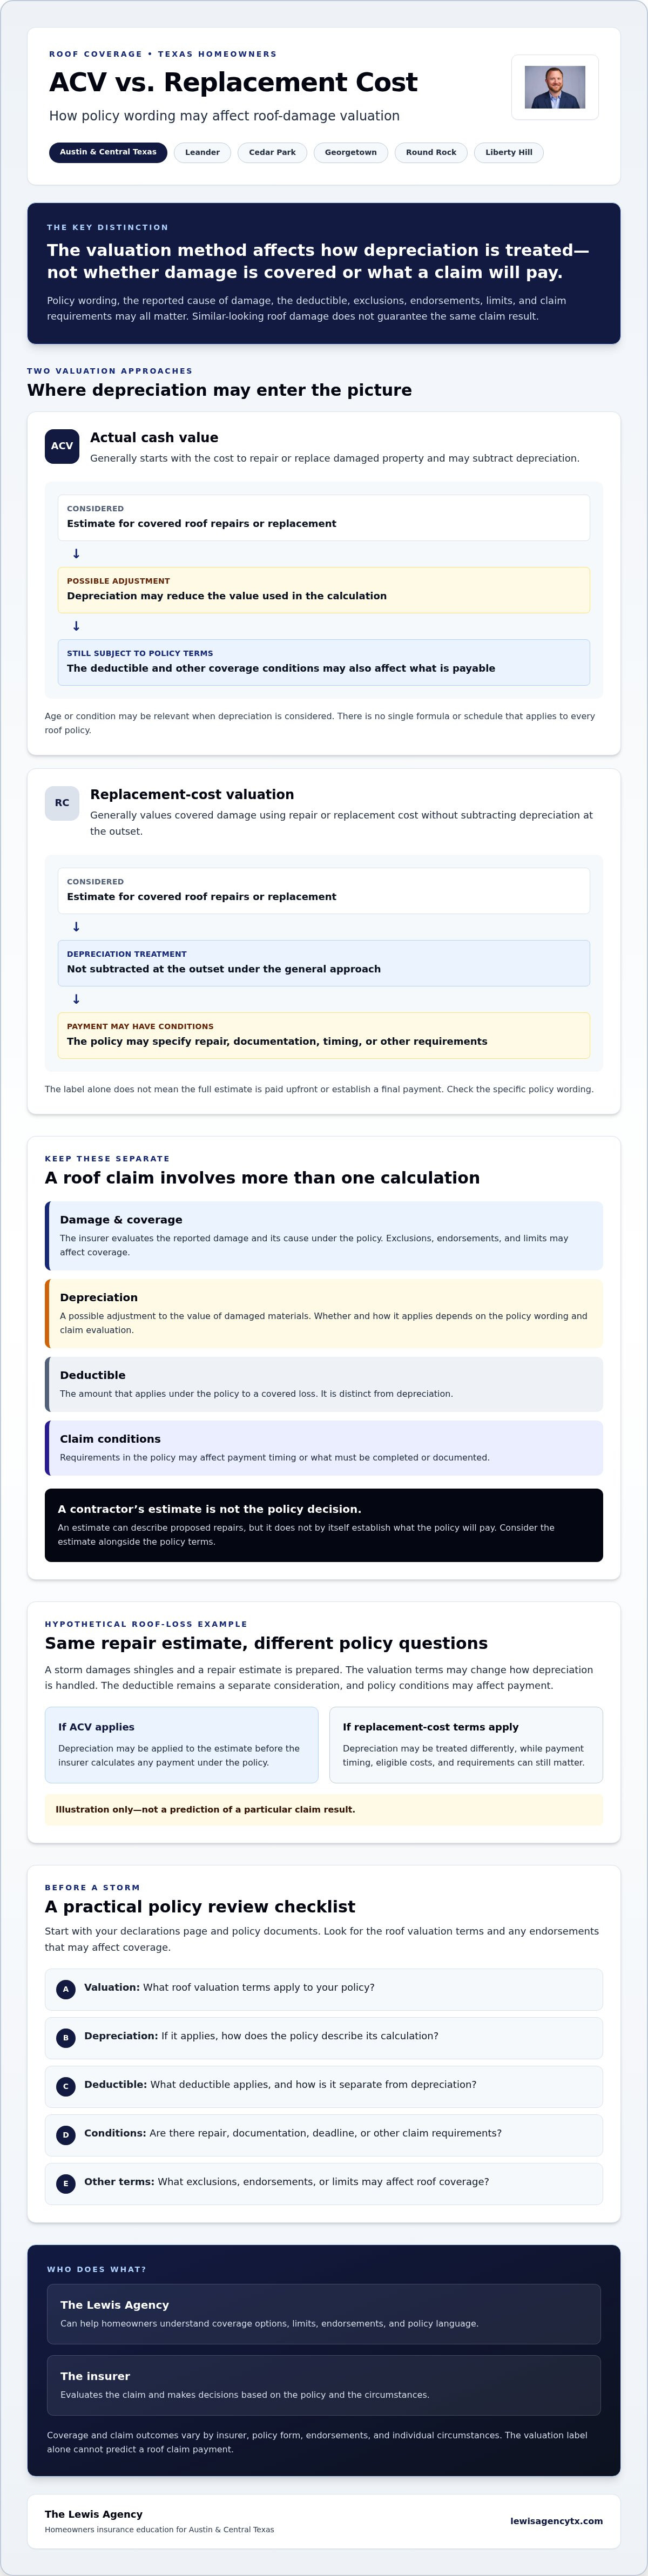
How The Lewis Agency Can Help You Understand Roof Coverage
Roof valuation language can be difficult to interpret on your own. The Lewis Agency works directly with clients to identify risks and match them with appropriate policies. For homeowners in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, and Liberty Hill, a conversation about homeowners coverage can help clarify which policy limits or endorsements may suit the dwelling and the homeowner’s needs.
Reviewing your coverage before a storm can help you identify questions while there is time to look up the relevant terms. This discussion does not determine whether damage is covered or how much a claim will pay. The insurer reviews the claim and makes coverage and payment decisions based on the policy and circumstances.
What an insurance agency can clarify about roof coverage
An agency can help you discuss homeowners policy options, limits, and endorsements. You might ask where your documents address roof valuation, which deductible information to review, or whether an endorsement changes the coverage terms. Having the declarations page, full policy, and endorsements available can make it easier to focus on the specific wording in your documents.
Those conversations are about understanding and choosing coverage. They do not replace the insurer’s evaluation of a particular loss or determine claim payments, underwriting, rates, or coverage decisions. If a question depends on how the insurer evaluates reported damage, the insurer is the source for a decision about that claim.
A practical next step for Austin and Central Texas homeowners
Before asking about actual cash value vs replacement cost roof texas, gather your declarations page, full policy, and any endorsements. Mark passages you have questions about and make a short list covering:
- How the policy describes roof valuation and depreciation
- Which deductible information applies to roof damage
- Any exclusions, endorsements, or conditions that may affect a claim
- What steps or documentation the policy requires during the claims process
Having these documents at hand makes it easier to discuss the language that applies to your home, rather than relying on general assumptions about Texas roof claims. Policy terms and coverage vary, so use your own documents as the starting point.
If you have a question about your homeowners policy, ask a question about your homeowners coverage. A conversation can help clarify your coverage options and which questions may need to be directed to the insurer.
Review Your Roof Coverage Before the Next Storm
Understanding actual cash value vs replacement cost roof texas coverage starts with knowing how your policy treats depreciation, which deductible applies, and whether payment depends on specific claim steps. The valuation label alone cannot tell you what a future claim will pay. Your policy wording, endorsements, and circumstances matter.
Review your declarations page and policy documents. Look for roof valuation language, exclusions, applicable deductibles, and claim conditions. If a term is unclear, write down your questions and ask for an explanation before you need to make decisions after a storm.
The Lewis Agency helps clients identify risks and choose appropriate coverage. Homeowners in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, and Liberty Hill can discuss homeowners policy limits and endorsements with the agency. The insurer makes coverage and claim decisions.
Bring your questions and policy documents together for a clearer conversation. Ask a question about your homeowners coverage and take the next step toward understanding what your policy says.
Frequently Asked Questions
What is the difference between ACV and replacement cost for a roof?
ACV generally values covered roof damage after accounting for depreciation, which may reflect age, condition, or wear under the policy. Replacement-cost valuation generally uses repair or replacement cost without subtracting depreciation at the outset. The phrase “actual cash value vs replacement cost roof texas” refers to this basic distinction, but neither label promises a particular payment. Your policy wording, covered cause of loss, deductible, and claim conditions determine how the terms apply.
Does replacement-cost coverage pay to replace the entire roof?
Not necessarily. Replacement-cost coverage does not guarantee approval of a full roof replacement or full reimbursement of an estimate. The insurer evaluates the reported damage under the policy, and covered damage, deductibles, limits, exclusions, and required claim steps may affect payment. Review your own policy for the applicable terms. If the wording is unclear, ask your insurer or agent to explain it without assuming a particular claim outcome.
How is depreciation calculated on a Texas roof claim?
There is no single depreciation formula or rate that applies to every Texas roof claim. How depreciation is considered depends on the policy wording and the insurer’s evaluation of the claim. Ask how the roof’s age and condition were assessed and where the relevant valuation terms appear in your policy or endorsements. That can help you understand the calculation being used, but it does not establish the final claim payment.
Can an insurer settle a roof claim using ACV in Texas?
The applicable policy and the circumstances of the loss determine how a roof claim may be valued. There is no one answer for every Texas homeowner. Review your policy’s valuation provisions and any roof-related endorsements to see which terms apply. For Texas consumer guidance, consult current information from the Texas Department of Insurance. You can also ask your insurer or agent to explain relevant wording without assuming a specific claim result.
Does roof age affect actual cash value or replacement-cost coverage?
Roof age may affect underwriting or claim settlement, depending on the insurer and policy, but it does not create one universal outcome. Age alone may not tell you which valuation method applies or how a future claim would be handled. Check your policy and any roof-specific endorsements for the terms that apply to your home. Ask your insurer or agent to clarify the wording rather than relying on a general age cutoff.
What should I check in my policy before filing a roof claim?
Look for roof valuation language, applicable deductibles, exclusions, endorsements, documentation requirements, and claim conditions. Your declarations page may identify some coverage and deductible details, but it may not contain every relevant term. Read it alongside the full policy and endorsements. If a provision is unclear, ask your insurer or agent to explain what it says and which claim steps may apply. That explanation can help you understand the process, but it cannot promise a claim result.
Can The Lewis Agency decide whether my roof claim will be paid?
No. The insurer makes coverage and payment decisions based on the policy and circumstances of the loss. The Lewis Agency can help clients identify risks and discuss homeowners policy options, limits, and endorsements, but it cannot control a claim determination or guarantee an outcome. Homeowners in Austin, Central Texas, Leander, Cedar Park, Georgetown, Round Rock, and Liberty Hill can contact the agency with questions about their coverage.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.

Dwelling Coverage Homeowners Insurance Texas: Complete Policy Guide (2026)
Learn how dwelling coverage homeowners insurance Texas policies protect your home. Understand rebuild costs, hail deductibles, and policy limits with confide...
One of the most important numbers on a Texas homeowners insurance policy is the dwelling coverage limit—but it's also one of the easiest to misunderstand. Your home's insured value isn't necessarily the same as its market value, tax appraisal or purchase price.
In reality, market values and physical construction expenses are entirely different calculations. You don't want to pay high premiums for bloated protection, but you also cannot afford an unexpected shortfall when severe hailstorms strike. In this guide, you'll learn how Coverage A protects your home's structure, why rebuild expenses differ from market valuations, and how to establish accurate policy limits. We'll examine how replacement cost mechanics work, unpack percentage-based hail deductibles, and help you evaluate your coverage options with total confidence.
Key Takeaways
- Learn how dwelling coverage homeowners insurance Texas policies provide essential structural protection for your foundation, framing, and roof system after covered losses.
- Discover why real estate market value and property tax appraisals differ significantly from the actual labor and material costs required to reconstruct your home.
- Understand the vital financial distinctions between replacement cost settlements and actual cash value claim payouts, particularly for aging roof systems.
- Find out how evolving municipal building codes across Central Texas impact your repair requirements and why regular limit reviews prevent costly out-of-pocket shortfalls.
What Is Dwelling Coverage in Texas Homeowners Insurance?
Dwelling coverage, officially designated as Coverage A, forms the structural backbone of your policy. It pays to repair or rebuild the physical structure of your primary residence if damaged or destroyed by a covered loss. Rather than protecting the land beneath your feet or the furniture inside your rooms, this specific coverage focuses entirely on the bricks, mortar, and framing that keep a roof over your head.
In standard homeowners insurance policies, the dwelling limit serves as the baseline for the rest of your protection. The dollar amount you select for Coverage A directly dictates the formulaic limits available for other structures, personal property, and temporary living expenses. That makes setting an accurate limit for your dwelling coverage homeowners insurance Texas policy one of the most critical decisions you will make as a homeowner.
What Dwelling Coverage Protects Inside and Outside
Coverage A extends beyond the exterior siding to include permanently installed fixtures that make the house functional. If you could turn the house upside down, anything that stays attached typically falls under dwelling protection:
- Core structural framing: Concrete slab foundations, wall studs, roof trusses, subflooring, and exterior cladding.
- Attached structures: Attached two-car garages, covered back patios, front porticos, and permanently anchored decks.
- Built-in interior elements: Custom kitchen cabinetry, stone countertops, vanities, and installed hardwood or tile flooring.
- Integrated home mechanicals: Central ducted HVAC units, ductwork, plumbing lines, water heaters, and electrical breaker panels.
Items not permanently joined to the structure fall outside this protection. Separate outbuildings like detached storage sheds, standalone workshops, and perimeter fences require separate other structures coverage, while furniture and rugs belong to personal property.
Common Covered Perils vs. Standard Policy Exclusions
Texas weather presents substantial hazards to residential framing and roofs. Understanding how your dwelling coverage homeowners insurance Texas policy responds to sudden regional weather events ensures you know where policy boundaries lie.
Most standard policies cover perils like lightning, fire, high winds, and severe hail damage. They also generally cover sudden, accidental water discharge, such as an interior supply line that ruptures during an unexpected winter freeze. However, standard policies carry strict exclusions. Rising surface floodwaters, river overflows, and storm surges are excluded, requiring separate flood insurance policies. Similarly, gradual structural issues, such as foundation cracks caused by shifting clay soils, termite damage, or deferred roof maintenance, remain the homeowner's responsibility.
Dwelling Rebuild Value vs. Market Value in Texas
One common mistake homeowners make is assuming market value equals reconstruction cost. When your county appraisal district sends its annual property valuation, that total reflects buyer demand, school district boundaries, and neighborhood appeal. Your policy's Coverage A limit, however, exists strictly to purchase physical materials and hire licensed trades to reconstruct your home from the dirt up. As highlighted in the Texas Department of Insurance Home insurance guide, your structural limits need to reflect true replacement expense rather than real estate transactions or outstanding mortgage balances.
Why Real Estate Market Valuations Mislead Homeowners
Real estate appraisals bundle the value of your physical home together with the raw land it occupies. When a total catastrophe strikes, the lot beneath your home does not burn away. Factoring land value into your dwelling limits results in purchasing unnecessary coverage and paying inflated premiums for dirt that cannot be destroyed. Conversely, if local property sales cool down, the price of concrete, roofing, and skilled trade labor does not suddenly drop alongside home prices.
Key Factors Driving Texas Reconstruction Expenses
Calculating accurate replacement limits requires looking directly at physical construction variables rather than neighborhood sales comparables. Several regional elements determine what contractors charge to restore a damaged property:
- Architectural complexity: Steep roof pitches, custom masonry, high ceilings, and non-standard floor plans require specialized installation labor.
- Interior finish tiers: Rebuilding basic builder-grade trim involves different material expenses than replicating custom hardwood cabinetry, imported tile, and solid stone surfaces.
- Suburban trade demand: Fast-growing Central Texas communities like Leander, Liberty Hill, and Pflugerville experience high competition for subcontracting crews, which directly affects local labor rates.
- Demolition and debris haul-away: Before a builder pours fresh concrete, heavy equipment must break down damaged structures, clear hazardous rubble, and haul away debris to designated landfills.
If you aren't sure whether your current policy accounts for these regional construction realities, sitting down with The Lewis Agency can help you evaluate your property's specific characteristics and verify your numbers against local building trends.
Replacement Cost vs. Actual Cash Value on Texas Homes
Setting an accurate limit is only half the equation; the claim settlement method written into your contract determines how disbursements are calculated after a loss. When damage occurs, insurance carriers settle structural claims under either Actual Cash Value (ACV) or Replacement Cost Value (RCV). Knowing which provision applies to your structure protects your household from unexpected out-of-pocket bills.
Industry guidance on calculating your home's replacement cost emphasizes meeting your insurer's coinsurance requirements. According to the Texas Department of Insurance, most insurers require homeowners to maintain coverage equal to at least 80% of the home's total replacement cost. Falling short of this threshold can trigger coinsurance penalties, meaning the carrier reduces claim payouts on partial losses proportionally, leaving you responsible for the remaining balance.
Comparing Actual Cash Value and Replacement Cost
Actual cash value subtracts physical depreciation, factoring in the age and prior condition of your building materials before issuing payment. If an older roof sustains severe damage under an ACV provision, the insurer subtracts years of normal wear, paying only its current value. Replacement cost coverage pays to rebuild or replace damaged property with new materials of like kind and quality, without deductions for deterioration. Because of this added financial security, mortgage lenders routinely require replacement cost coverage on residential loans.
Extended Replacement Cost and Inflation Guard Endorsements
Severe storm outbreaks frequently generate localized shortages of building materials and trade labor. When widespread hail damages hundreds of homes in a single community, local construction costs can surge overnight, occasionally exceeding initial estimates.
Adding an extended replacement cost endorsement gives your dwelling coverage homeowners insurance Texas policy an extra safety buffer. Depending on policy terms, this endorsement provides an additional percentage of structural coverage above your stated Coverage A limit if localized demand drives up reconstruction expenses. Pairing this buffer with an inflation guard endorsement helps ensure your base limits steadily adjust over time, preserving your financial protection against ongoing price increases.
Tailoring Dwelling Coverage to Texas Perils and Local Codes
Every region presents its own set of environmental threats, but the Lone Star State is notorious for volatile weather patterns. From severe straight-line winds and tornadoes to spring hail swarms and bitter winter freezes, your home's structural framing and roof endure extraordinary strain. Structuring your dwelling coverage homeowners insurance Texas policy requires tailoring your protections to these specific regional realities rather than settling for a generic policy template.
Managing Hail Risks and Percentage Deductibles
Severe convective storms, hail, and high winds generate over 60% of all Texas homeowners insurance losses. Because hail risk is so high across the state, Texas insurers commonly write separate wind and hail deductibles structured as a percentage rather than a flat dollar amount. Crucially, this percentage applies directly to your Coverage A dwelling limit, not the total amount of storm damage.
For example, if your dwelling limit sits at $400,000 and your policy includes a 2% wind and hail deductible, your out-of-pocket obligation is $8,000 before insurance proceeds cover a single dollar of roof repairs. Under Texas Business & Commerce Code § 27.02, it is illegal for roofing contractors to absorb, rebate, or waive this deductible, meaning policyholders must pay this amount themselves. Keeping your baseline dwelling limit accurate prevents your percentage deductible from inflating unnecessarily while still ensuring adequate reconstruction funds.
The Role of Ordinance or Law Coverage in Growing Communities
Standard home policies agree to rebuild damaged structures back to their original specifications. However, fast-growing municipalities across Travis and Williamson counties regularly update local building standards. Cities like Cedar Park, Buda, and Round Rock frequently adopt newer revisions of the International Residential Code (IRC) along with stricter energy conservation mandates.
If extensive repairs require upgraded electrical panels, modified roof decking fasteners, or modern plumbing pipe configurations, standard policies typically provide little or no funding for those mandatory improvements. Adding an Ordinance or Law endorsement bridges this financial gap, providing dedicated funds to cover the code-mandated upgrades required by municipal inspectors during reconstruction.
Taking time to review your policy details can save your family thousands of dollars after a storm. If you want a clear, personalized assessment of your structural limits and roof deductibles, contact The Lewis Agency to walk through your current homeowners coverage.
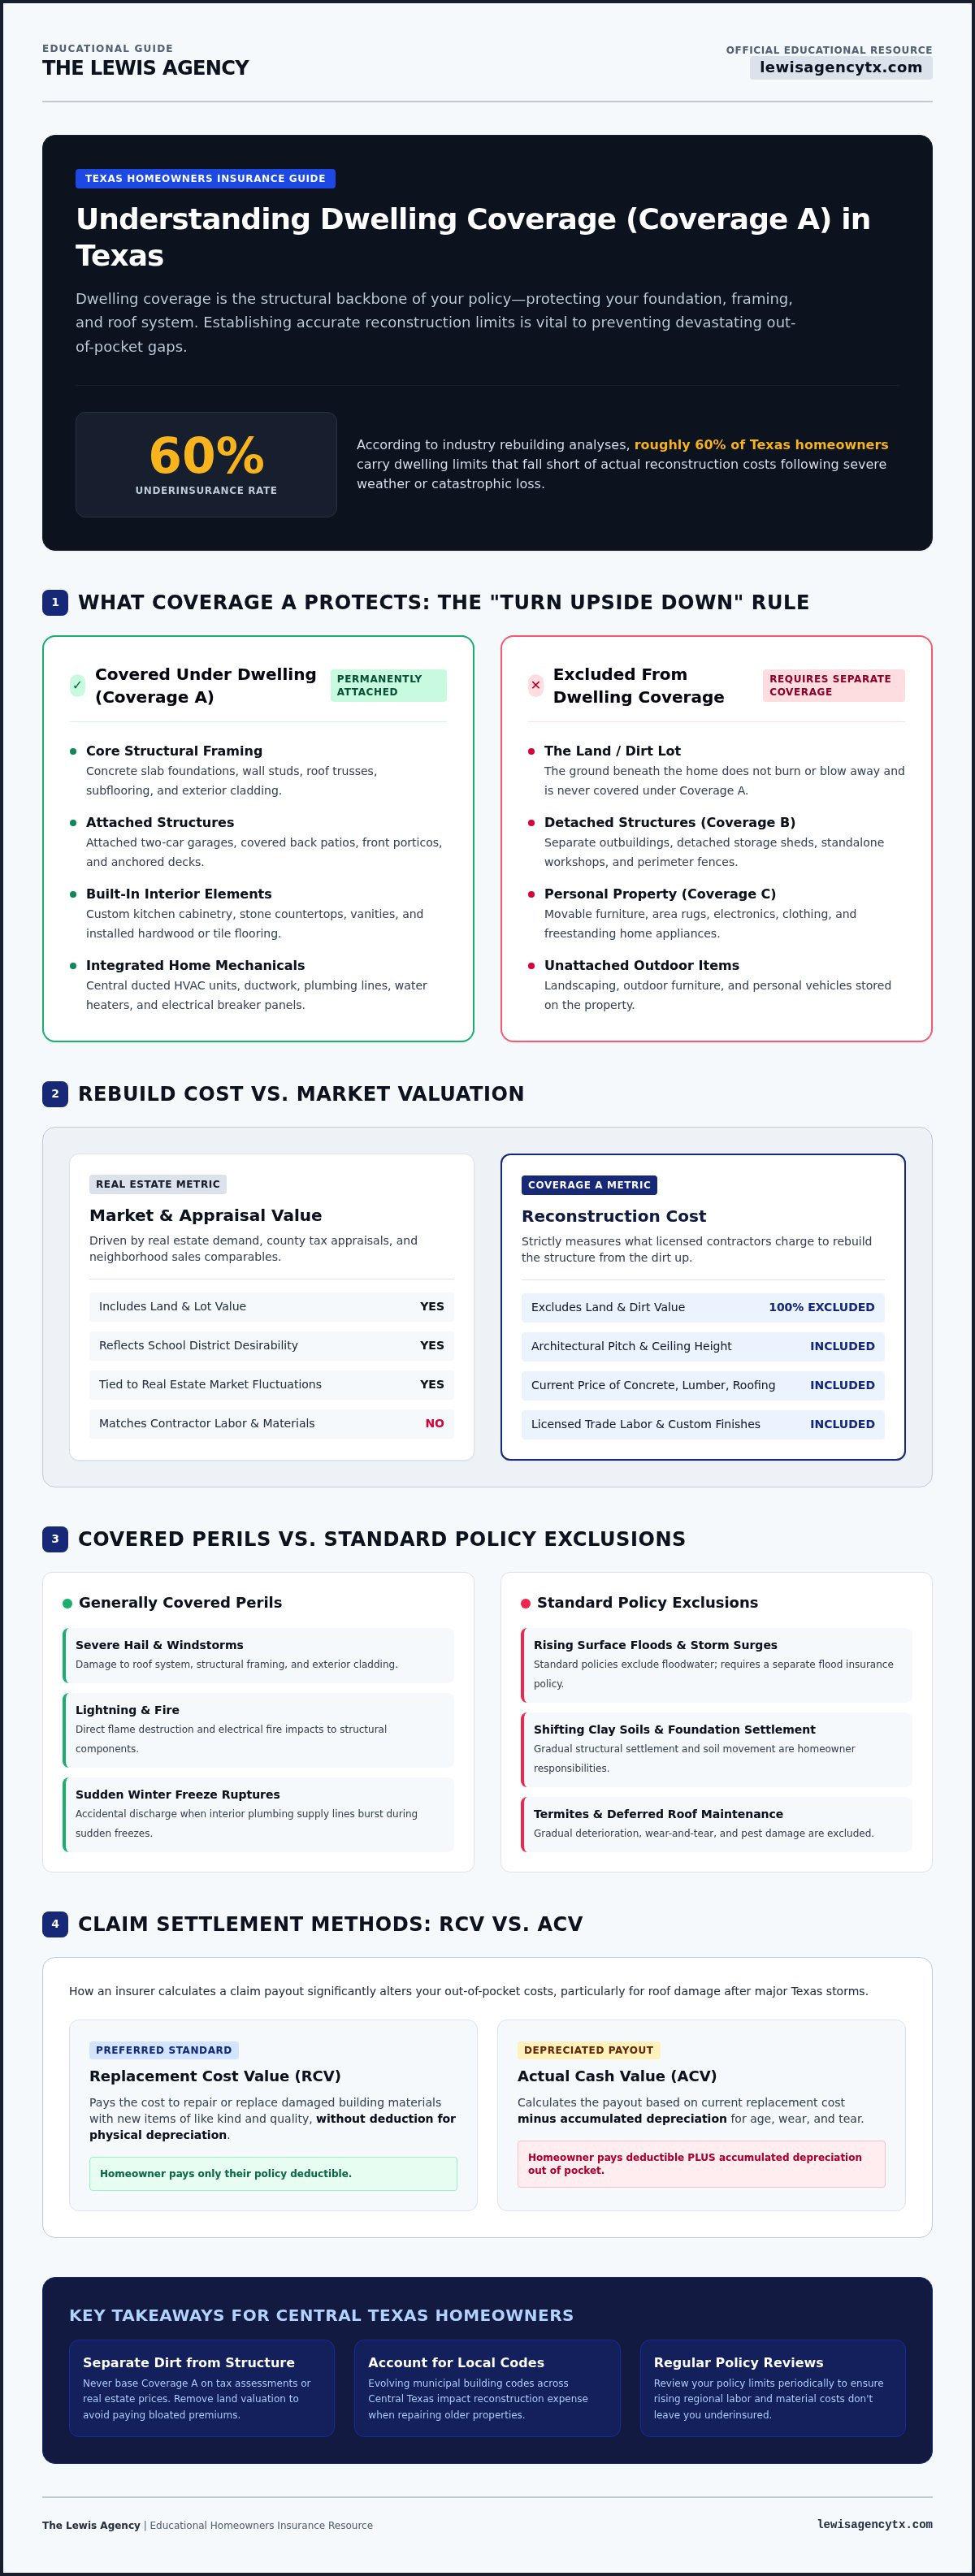
How to Review and Adjust Your Texas Dwelling Coverage Limits
Homes evolve over time, and regional construction expenses shift alongside them. Leaving a policy on autopilot for years creates a dangerous gap between your coverage limits and actual local building expenses. Maintaining the right dwelling coverage homeowners insurance Texas policy requires ongoing attention rather than a one-time estimate. Instead of relying on rough square-footage guesses, accurate structural evaluations utilize comprehensive replacement cost estimators that account for your home's unique layout, foundation, and interior craftsmanship.
Triggers That Require Adjusting Your Coverage A Limits
Everyday improvements and market shifts alter your replacement needs. You should reach out to adjust your Coverage A baseline whenever you experience one of these key milestones:
- Interior remodeling: Upgrading to custom solid wood cabinetry, luxury bathroom fixtures, or high-end stone countertops increases the physical cost required to restore damaged rooms.
- Added square footage: Finishing a bonus room over your garage, enclosing a back patio, or constructing an attached guest suite expands your total rebuild footprint.
- Mechanical installations: Adding permanent infrastructure like whole-home standby generators, multi-stage HVAC systems, or built-in water filtration systems adds substantial replacement value.
- Regional cost shifts: General changes in subcontractor availability and supply chain pricing across Williamson and Travis counties can quietly leave older policy limits behind.
Working with The Lewis Agency on Your Coverage
Having experienced local guidance makes evaluating structural protection straightforward and stress-free. As a dedicated Allstate agency serving Central Texas communities like Austin, Round Rock, Cedar Park, Leander, and Pflugerville, The Lewis Agency understands how regional weather exposures and municipal building standards affect your home.
Agent Chris Lewis takes the time to sit down with you, examine your home's specific building features, and ensure your structural limits and deductibles work together effectively. When you want clear answers and personalized attention, schedule a consultation with The Lewis Agency to review your Texas homeowners policy and ensure your coverage matches your family's needs.
Protect Your Central Texas Home with the Right Structural Limits
Securing adequate dwelling coverage homeowners insurance Texas policies offer isn't about matching your neighbor's policy or relying on county tax appraisals. It's about making sure your Coverage A limit realistically reflects the current materials, specialized labor, and building codes required to restore your home after an unexpected catastrophe. Balancing replacement cost provisions with manageable percentage deductibles ensures you aren't caught off guard when severe weather rolls across the state.
You don't have to decipher these complex structural details by yourself. As a dedicated local Allstate agency serving Austin, Round Rock, Cedar Park, Leander, and Pflugerville, The Lewis Agency provides personalized coverage reviews tailored to regional construction trends. Agent Chris Lewis brings experienced, neighborly guidance to every conversation, helping you evaluate your property's specific rebuild requirements with total clarity.
Take the uncertainty out of your homeowners policy. Review your Texas homeowners coverage with The Lewis Agency today, and enjoy the lasting confidence that comes from knowing your home is thoroughly protected.
Frequently Asked Questions
How do I know if my Texas dwelling coverage limit is high enough?
Your limit is high enough if it matches a professional replacement cost calculation rather than your home's purchase price. A detailed replacement cost estimate examines your square footage, roof pitch, custom finishes, and local trade wages across Central Texas cities like Round Rock and Leander. Annual reviews ensure your dwelling coverage homeowners insurance Texas policy limit keeps pace with shifts in material costs and regional building expenses.
Is dwelling coverage based on the county property tax appraisal value in Texas?
No, dwelling coverage is never based on county property tax appraisal numbers. County appraisals evaluate the market value of your property, which includes both the physical house and the underlying parcel of land. Rebuild insurance strictly covers the labor, equipment, and building materials needed to reconstruct the structural dwelling. Because your land doesn't disappear during a loss, tying your policy limit to tax records results in inaccurate coverage.
What happens if my home costs more to rebuild than my dwelling coverage limit?
If rebuild expenses exceed your limit, you must pay the remaining balance out of pocket. Standard policies pay claims only up to the stated Coverage A limit on your declarations page. However, adding an extended replacement cost endorsement provides an additional percentage buffer above your base limit if localized disasters cause sudden surges in labor and lumber costs. Reviewing your policy prevents catastrophic out-of-pocket shortfalls during major community rebuilding phases.
Does dwelling insurance cover roof damage caused by severe Texas hailstorms?
Yes, standard policies generally cover hail damage to roofs, but specific settlement terms depend on your policy language. Hail is typically a covered peril, but your claim payout depends on whether your policy pays replacement cost or actual cash value based on roof age. Texas policies also apply separate wind and hail deductibles, which require an out-of-pocket percentage payment based on your total dwelling limit before claim funds are released.
Can I lower my dwelling coverage to reduce my homeowners insurance premium?
You shouldn't artificially lower your Coverage A limit simply to reduce your premium. Insurers generally require coverage equal to at least 80% of replacement costs to avoid coinsurance penalties on partial claims. Dropping your structural limit below true rebuild expenses exposes your family to major out-of-pocket liabilities. Instead of cutting essential dwelling protection, explore adjusting your policy deductibles or reviewing eligible policy credits with your local agent.
Does dwelling insurance cover foundation damage caused by shifting Texas soil?
Standard policies exclude foundation damage caused by normal soil expansion, contraction, or settling. The expansive clay soils common across Austin, Pflugerville, and Williamson County frequently cause ground movement, but standard Texas home policies treat this as gradual wear. However, if foundation cracking results directly from an accidental, sudden plumbing freeze or interior pipe rupture, limited coverage may apply depending on your specific policy endorsements and water damage riders.
What is the difference between dwelling coverage and other structures coverage?
Dwelling coverage protects your primary residence and permanently attached features, while other structures coverage protects unattached outbuildings. Your dwelling limit pays for repairs to your house, roof, foundation, and attached garage. Other structures coverage, known as Coverage B, specifically covers separate physical assets on your property grounds, such as detached storage sheds, standalone workshops, gazebos, and perimeter fencing, typically set as a default percentage of your dwelling limit.
Article by
Chris Lewis
Chris Lewis is the owner of The Lewis Agency, an Allstate insurance agency serving Austin and Central Texas. With more than 25 years of insurance experience, Chris focuses on helping Central Texas homeowners better understand their insurance coverage, including deductibles, roofs and hail, severe weather risks, water damage and other important coverage considerations. He created LewisAgencyTX.com to provide practical homeowners insurance education and help homeowners better understand their coverage before they need it.